1What is the current size of the US pet care and services market?
The US pet care and services market was valued at $62.10 billion in 2025 and is estimated to reach $66.27 billion in 2026, growing at a CAGR of 6.72% to reach $91.74 billion by 2031.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 US Pet Care and Services Market
 by Product and Service Type (Products(Pet Food, Pet Healthcare, Pet Grooming Products, Pet Accessories), Services(Veterinary Care, Pet Grooming, Pet Boarding & Daycare, Pet Training, Pet Insurance)), by Pet Type (Cat, Dog, More), by Sales and Service Channel (Offline, Online), by Northeast, by South, by Midwest, by West Forecast 2026-2034
Research Analyst


 Related Reports

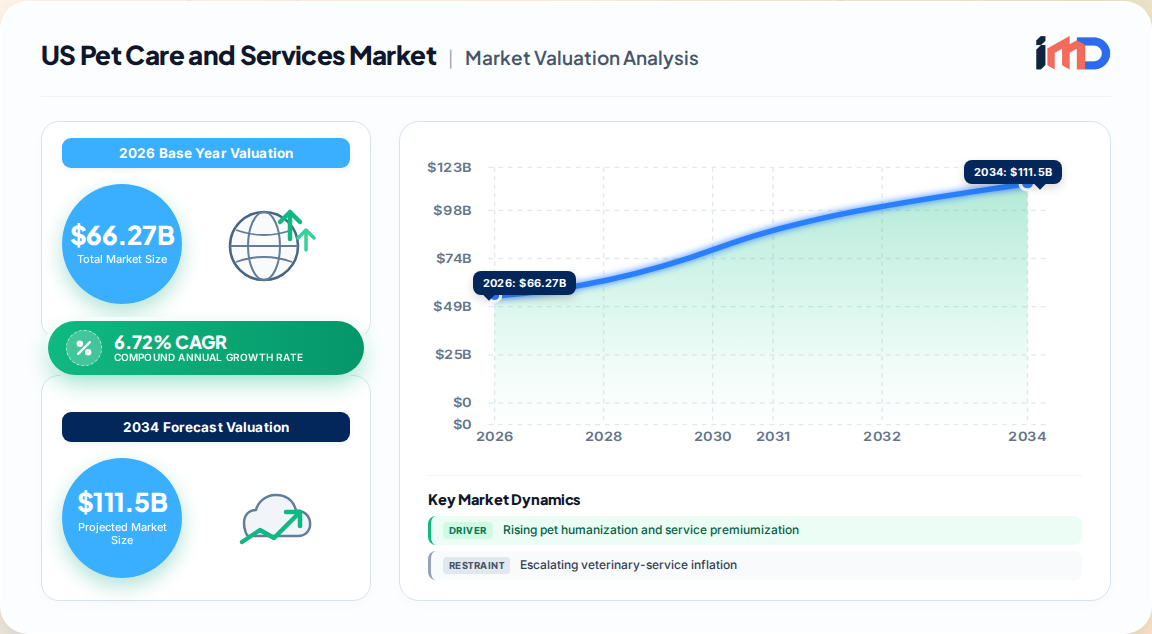
The US pet care and services market is undergoing a structural transformation. Valued at $62.10 billion in 2025, the market is projected to reach $66.27 billion in 2026 and expand to $91.74 billion by 2031, registering a CAGR of 6.72% over the forecast period. This growth is underpinned by deep-seated pet humanization, premiumization of nutrition and healthcare, and rapid digital adoption across sales and service channels.
With 95 million US households owning a pet in 2024, the addressable base is nearly universal. Yet the market is not merely growing in volume; it is shifting in value composition. Pet products commanded 62.45% of revenue in 2025, but services are accelerating at a 6.98% CAGR through 2031, signaling a rebalancing toward recurring, high-margin service models. Dogs remain the largest species segment at 63.42% share, while cats are the faster-growing cohort at 7.11% CAGR.
Our proprietary driver-impact modeling identifies five forces shaping the market's trajectory, each with a quantifiable effect on the forecast CAGR.
| Driver | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Rising pet humanization & service premiumization | +1.8% | National, urban centers | Long term (≥4 years) |
| Surge in e-commerce & subscription models | +1.5% | National, tech-forward states | Short term (≤2 years) |
| Expanding pet-insurance coverage & awareness | +1.2% | CA, NY, FL | Medium term (2–4 years) |
| AI-enabled veterinary tele-health investment | +0.9% | Metropolitan areas | Medium term (2–4 years) |
| Employer-sponsored pet benefits | +0.6% | National, tech companies | Long term (≥4 years) |
Pet humanization is the single most powerful driver. Average monthly pet spend reached $318 in 2024, and 67% of owners are willing to pay more for perceived health benefits. This premium-price elasticity is visible across veterinary, grooming, and boarding subcategories, where consumers increasingly demand human-grade standards.
On the restraint side, veterinary-service inflation is the most significant headwind, exerting a -1.4% impact on CAGR. Pet services prices have outpaced general inflation by 60% since 2005 and rose 8% year-over-year to August 2025. Veterinary visits fell 3% in 2023, indicating income sensitivity and deferred care. The veterinary-workforce shortage (-1.1% impact) compounds this: high debt burdens (over $200,000) and burnout create functional staff shortages, with up to 75% of pets potentially lacking necessary care by 2030.
The market is segmented by product/service type, pet type, and sales channel. Each axis reveals distinct growth vectors.
By Product and Service Type
By Pet Type
By Sales and Service Channel
| Channel | 2025 Share | 2031 CAGR |
|---|---|---|
| Offline | 64.10% | 5.9% (est.) |
| Online | 35.90% | 7.55% |
The US pet care and services market is moderately concentrated, with global conglomerates and specialized players competing across the value chain. Key companies include Mars, Incorporated (Royal Canin, Pedigree, Banfield), Nestlé S.A. (Purina), PetSmart LLC, Hill's Pet Nutrition, Inc., and ViaGen LC.
Consolidation is a defining trend. Corporate groups are integrating veterinary clinics, telehealth platforms, and insurance offerings to capture lifetime customer value. Zoetis' 32,000 sq ft reference lab in Louisville exemplifies investment in scalable, data-driven care. Meanwhile, employer-sponsored "paw-ternity" programs and pet benefits are pioneering new B2B2C channels.
E-commerce titans and subscription models are shifting value toward data-rich direct-to-consumer relationships. Traditional brick-and-mortar players must evolve beyond product sales to integrated digital ecosystems and value-added services. AI-enabled tele-health reduces burnout costs (estimated at $2 billion annually) but favors large consolidators over independents due to capital intensity.
The US market exhibits distinct regional patterns.
Investment opportunities are concentrated in:
The value chain spans raw material suppliers, manufacturers, distributors, service providers, and end consumers. Key dynamics include:
Supply chain risks include veterinary workforce shortages, regulatory scrutiny of consolidation, and data-privacy concerns in connected pet devices. Companies are responding with vertical integration, M&A, and technology investment.
The regulatory environment is evolving to address market growth and consumer protection.
The US pet care and services market will reach $91.74 billion by 2031, growing at 6.72% CAGR. To capture value, stakeholders should prioritize:
The market's resilience is anchored in the human-animal bond, which shows no signs of weakening. Companies that align with pet humanization and deliver convenience, transparency, and premium care will outperform.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.72% from 2020-2034 |
| Segmentation |
|
By Pet Type
By Sales and Service Channel
| By Geography |
|
The US pet care and services market was valued at $62.10 billion in 2025 and is estimated to reach $66.27 billion in 2026, growing at a CAGR of 6.72% to reach $91.74 billion by 2031.
Pet products commanded 62.45% of revenue in 2025, with pet food being the largest sub-segment. However, services are growing faster at 6.98% CAGR, driven by veterinary care, grooming, and insurance.
Rising pet humanization (+1.8% CAGR impact), e-commerce and subscription models (+1.5%), expanding pet insurance coverage (+1.2%), and AI-enabled veterinary tele-health (+0.9%) are the primary growth drivers.
Cats are projected to grow at a 7.11% CAGR through 2031, faster than dogs (which hold 63.42% share), driven by urbanization and lower ownership costs.
Escalating veterinary-service inflation (-1.4% CAGR impact) and veterinary-workforce shortage (-1.1%) are the top restraints, alongside high premium cancellations in pet insurance and data-privacy concerns.
Key companies include Mars, Incorporated, Nestlé S.A. (Purina), PetSmart LLC, Hill's Pet Nutrition, Inc., and ViaGen LC, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Veterinary Officer | 25% |
| Director of Pet Nutrition R&D | 20% |
| Head of Pet Insurance Product | 20% |
| VP of E-commerce Operations | 20% |
| Procurement Director | 15% |
| Company Type | Representation (%) |
|---|---|
| Veterinary Clinics & Hospitals | 30% |
| Pet Food & Product Manufacturers | 25% |
| Pet Insurance Providers | 15% |
| E-commerce & Retail Platforms | 20% |
| Grooming, Boarding & Training Services | 10% |