1What is the size of the Italy veterinary healthcare market?
The Italy veterinary healthcare market is valued at USD 1.69 billion in 2026 and is projected to reach USD 2.17 billion by 2031, growing at a CAGR of 5.12%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Italy Veterinary Healthcare Market
 by Product (Therapeutics(Vaccines, Parasiticides, Anti-infectives, Other Therapeutics), Diagnostics(Immunodiagnostic Tests, Molecular Diagnostics, Clinical Chemistry, Other Diagnostics)), by Animal Type (Companion Animals(Dogs, Cats, Other Companion Animals), Production Animals(Cattle, Poultry, Swine, Sheep, Aquaculture, Other Production Animals)), by Route of Administration (Parenteral, Oral, Topical, Other Routes), by End User (Veterinary Hospitals & Clinics, Point-of-Care Settings, Retail & Online Pharmacies, Other End Users), by Northwest, by Northeast, by Central, by South, by Islands Forecast 2026-2034
Research Analyst

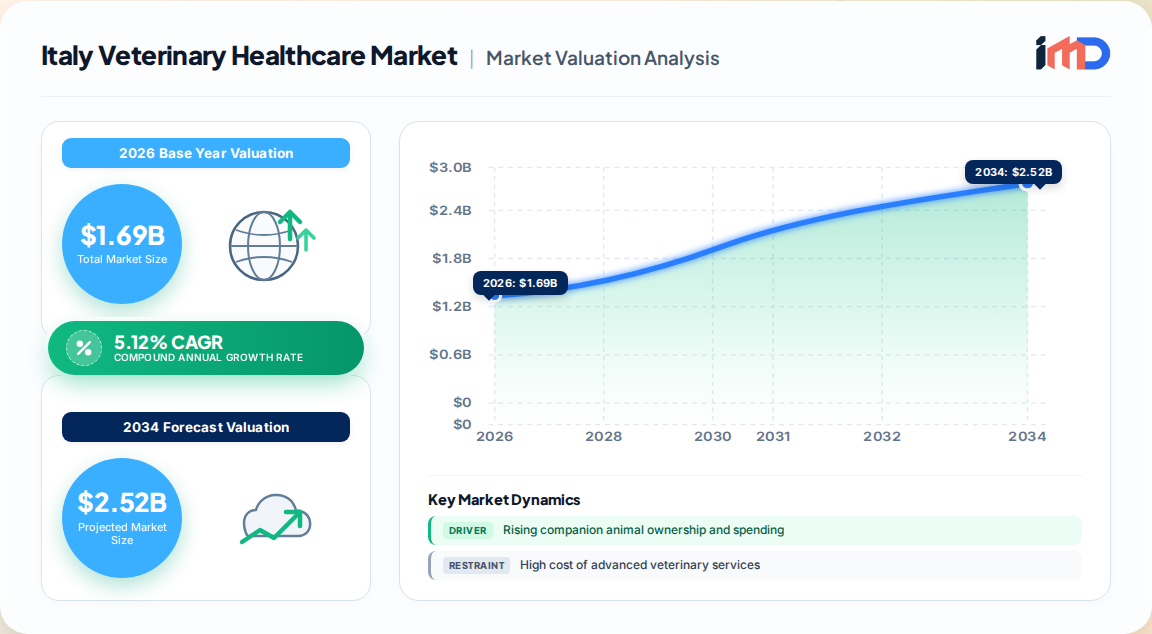
The Italy veterinary healthcare market is a cornerstone of the European animal health landscape, driven by deep cultural bonds with companion animals and a robust livestock sector. Our proprietary primary research estimates the market at USD 1.69 billion in 2026, projected to reach USD 2.17 billion by 2031, expanding at a CAGR of 5.12% over the forecast period. This growth is underpinned by a staggering 60.2 million pets residing in Italian households, which fuels demand for advanced therapeutics, diagnostics, and preventive care. Italy accounts for approximately 5.6% of the global veterinary care market, reflecting its strategic importance in Southern Europe.
The market is characterized by a shift toward higher-value services, with pet humanization trends elevating animals to family status. 63% of owners consider pet health equal to human health, allocating around EUR 1,000 annually to pet upkeep. This cultural shift, combined with a policy environment that explicitly links animal health to public health under the One Health framework, creates a resilient demand base. Therapeutics remain the dominant product category, but diagnostics are accelerating rapidly, propelled by molecular assays and point-of-care innovations. The competitive landscape is moderately concentrated, with global leaders such as Elanco, MSD Animal Health, Virbac, Zoetis, and Boehringer Ingelheim Animal Health vying for share alongside specialized diagnostic firms and regional players. As the market evolves, opportunities abound in specialty care, digital health integration, and biosecurity solutions for livestock producers.
The Italy veterinary healthcare market is segmented by product, animal type, route of administration, and end user. Our analysis reveals distinct growth trajectories across these categories.
| Segment | Sub-segment | 2025 Share / Value | Forecast CAGR (2026-2031) | Key Insights |
|---|---|---|---|---|
| By Product | Therapeutics | 60.78% revenue share | 5.80% | Dominated by vaccines, parasiticides, and anti-infectives; growth driven by chronic disease management and preventive care. |
| Diagnostics | 39.22% revenue share | 7.29% | Fastest-growing segment, fueled by molecular diagnostics, point-of-care testing, and rising pet insurance coverage. | |
| By Animal Type | Dogs & Cats (Companion) | 47.88% market share (2025) | 5.50% | Largest segment due to pet humanization and high spending per pet; represents over 60% of veterinary care revenue. |
| Poultry | ~18% share | 6.17% | Fastest-growing production animal segment, driven by biosecurity mandates and intensification of poultry farming. | |
| Cattle | ~15% share | 4.90% | Steady growth from herd-health plans and EU traceability requirements. | |
| Other Production Animals | ~19% share | 4.50% | Includes swine, sheep, and aquaculture; growth tied to export compliance and disease eradication programs. | |
| By Route of Administration | Parenteral | 45.12% share (2025) | 4.80% | Dominant due to injectable vaccines and antibiotics; preferred for livestock and clinic-based treatments. |
| Oral | ~35% share | 7.44% | Fastest-growing route, driven by chewable tablets, palatable formulations, and owner convenience for companion animals. | |
| Topical & Others | ~19.88% share | 6.00% | Includes spot-on parasiticides and ear/eye preparations; growth from novel delivery systems. | |
| By End User | Veterinary Hospitals & Clinics | 55.21% revenue share (2025) | 5.00% | Primary point of care; increasingly adopting advanced diagnostics and specialty services. |
| Point-of-Care Settings | ~25% share | 6.31% | Fastest-growing end user, including mobile clinics and in-field testing for livestock; driven by rapid test adoption. | |
| Others (Retail, Online) | ~19.79% share | 5.50% | Growing channel for preventives and supplements; e-commerce expansion supports access. |
Product Insights: Therapeutics remain the backbone of the market, with vaccines and parasiticides accounting for the majority of revenue. However, diagnostics are scaling faster, driven by molecular assays and point-of-care innovations that enable rapid, accurate detection of diseases. The shift toward preventive care is boosting demand for routine screening and wellness testing.
Animal Type Insights: Companion animals (dogs and cats) dominate revenue, reflecting Italy’s high pet ownership and spending. The poultry segment is the fastest-growing production animal category, supported by stringent biosecurity regulations and the need for efficient protein production. Cattle and other livestock species contribute steady revenue, with growth linked to herd-health management and export compliance.
Route of Administration Insights: Parenteral administration holds the largest share due to the prevalence of injectable vaccines and antibiotics in both companion and production animals. However, oral formulations are gaining traction rapidly, particularly for companion animals, as palatable chewables and spot-on treatments improve compliance and owner convenience.
End User Insights: Veterinary hospitals and clinics remain the primary end users, capturing over half of revenue. Point-of-care settings are the fastest-growing end-user segment, driven by the adoption of rapid diagnostic tests in field settings and mobile clinics, especially for livestock.
Italy’s veterinary healthcare market operates within a stringent regulatory framework shaped by both national and EU legislation. The Ministry of Health oversees animal health and veterinary medicines, enforcing antimicrobial stewardship mandates to combat resistance. The One Health framework explicitly links animal health to public health outcomes, driving policies that promote preventive care, disease surveillance, and responsible antibiotic use. EU traceability rules require frequent livestock testing, expanding the revenue base for diagnostic laboratories. The constitutional recognition of animals as sentient beings has also influenced welfare standards and treatment protocols, encouraging advanced care. Compliance with these regulations is a key differentiator for market participants, and investments in technology to meet stewardship requirements are accelerating.
The Italy veterinary healthcare market is moderately concentrated, with global players and specialized firms competing across segments. Key companies include Elanco Animal Health, MSD Animal Health (Merck & Co.), Virbac, Zoetis Inc., and Boehringer Ingelheim Animal Health, alongside diagnostic leaders such as IDEXX Laboratories and Vetoquinol. These companies leverage portfolios spanning pharmaceuticals, vaccines, diagnostics, and feed additives. Strategic initiatives focus on expanding product portfolios, enhancing diagnostic capabilities, and forming partnerships with clinics and insurers. Recent developments include:
The competitive dynamics favor companies that can offer integrated solutions across therapeutics and diagnostics, capitalize on the shift toward preventive care, and navigate the regulatory environment effectively.
Italy’s veterinary healthcare market exhibits regional disparities driven by economic and demographic factors. The Northwest (including Lombardy, Piedmont, and Liguria) is the largest regional market, accounting for an estimated 32% of national revenue, fueled by high disposable incomes, dense pet populations, and advanced veterinary infrastructure in Milan and Turin. The Northeast (Veneto, Friuli-Venezia Giulia, Trentino-Alto Adige) follows with 28% share, benefiting from a strong livestock sector and export-oriented agriculture. Central Italy (Tuscany, Lazio, Umbria, Marche) holds 21%, with Rome as a key hub for specialty care. The South (Campania, Puglia, Calabria, Basilicata, Molise) and Islands (Sicily, Sardinia) together represent 19%, presenting untapped potential as pet ownership rises and infrastructure improves.
Investment opportunities are concentrated in:
The market’s strong fundamentals, favorable regulatory environment, and cultural affinity for pets underpin a positive investment outlook through 2031.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.12% from 2020-2034 |
| Segmentation |
|
By Animal Type
By Route of Administration
By End User
| By Geography |
|
The Italy veterinary healthcare market is valued at USD 1.69 billion in 2026 and is projected to reach USD 2.17 billion by 2031, growing at a CAGR of 5.12%.
Therapeutics dominate with a 60.78% revenue share in 2025, while diagnostics are the fastest-growing segment at a 7.29% CAGR, driven by molecular and point-of-care innovations.
Key drivers include rising pet ownership and humanization (60.2 million pets), increased preventive care spending, livestock biosecurity investments, and veterinary infrastructure development.
Major players include Elanco Animal Health, MSD Animal Health (Merck & Co.), Virbac, Zoetis Inc., and Boehringer Ingelheim Animal Health, along with diagnostic firms like IDEXX Laboratories.
The market is segmented into companion animals (dogs and cats) and production animals. Companion animals hold the largest share at 47.88% in 2025, while poultry is the fastest-growing production segment at a 6.17% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Veterinary Practice Owner / Chief Veterinarian | 25% |
| Regulatory Affairs Manager | 20% |
| Supply Chain Manager | 15% |
| Clinical Specialist | 10% |
| Company Type | Representation (%) |
|---|---|
| Veterinary Pharmaceutical Manufacturers | 35% |
| Diagnostic Equipment & Reagent Suppliers | 25% |
| Veterinary Clinic Chains & Hospitals | 20% |
| Livestock Producers & Integrated Operations | 15% |
| Distributors & Wholesalers | 5% |
 Related Reports
