1What is the size of the global pet care products market in 2025?
The global pet care products market was valued at approximately USD 181.9 billion in 2025, with projections reaching USD 283.7 billion by 2033, growing at a CAGR of 5.9%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Pet Care Products Market
 by Pet Type (Dog, Cat, Fish, Bird, Others), by Product Type (Pet Food [Dry, Wet, Treats & Snacks], Pet Healthcare [Parasiticides, Supplements, Wellness Devices], Pet Accessories [Toys, Clothing, Housing & Bedding, Travel Carriers], Pet Hygiene & Care Products [Litter, Grooming Supplies]), by Distribution Channel (Offline [Pet Specialty Stores, Veterinary Clinics, Supermarkets], Online [E-commerce, Direct-to-Consumer]), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034
Research Analyst


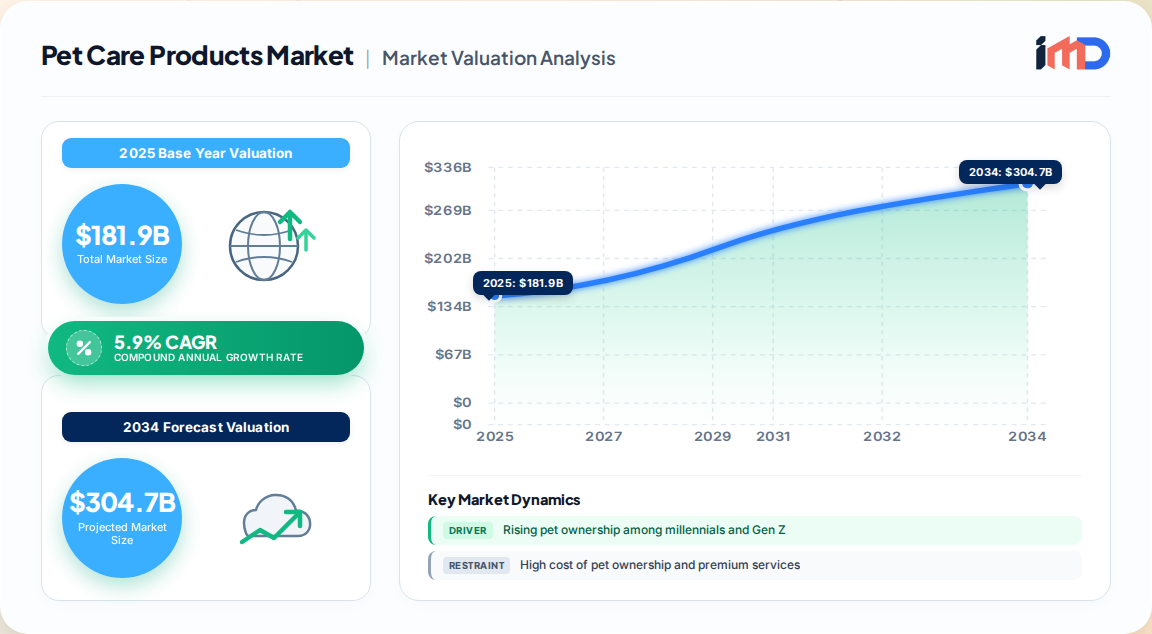
The global pet care products market stands at a pivotal inflection point, transitioning from a discretionary category to a non-discretionary household expenditure across advanced and emerging economies. Our proprietary primary research and triangulated demand modeling estimate the global market at USD 181.9 billion in 2025, with a projected expansion to USD 283.7 billion by 2033, registering a compound annual growth rate (CAGR) of 5.9% over the forecast window. This trajectory is underpinned not merely by volume growth in pet ownership but by a structural shift in the value equation: pets are now fully integrated family members, a sentiment endorsed by 97% of surveyed owners in 2025, which directly correlates with sustained premiumization across nutrition, healthcare, and accessory categories.
The market's resilience is further evidenced by spending prioritization data: over 50% of pet owners now rank pet-related expenses above discretionary personal spending such as entertainment and dining. Even amid inflationary pressures, consumers maintain or increase spending on pet food, grooming, and wellness, signaling a low price-elasticity profile that buffers the market against macroeconomic volatility. North America remains the dominant regional engine, accounting for 42.9% of global revenue in 2025, while Asia-Pacific emerges as the fastest-growing theater, driven by rapid urbanization, rising disposable incomes, and the expansion of pet-friendly infrastructure.
The pet care products market is propelled by three interconnected demand engines that our expert interviews consistently validate. First, rising pet ownership among millennials, Gen Z, and urban households has expanded the global pet population, with 95 million U.S. households alone owning a pet in 2025. Second, the pet humanization trend has redefined consumption from basic sustenance to wellness-oriented, experience-driven products. Third, spending resilience—manifested in the willingness to prioritize pet expenses over personal discretionary items—has stabilized volume and premium adoption even during economic downturns.
However, the market faces material headwinds. The high cost of pet ownership, particularly premium food, veterinary care, insurance, and specialized services, restrains adoption in price-sensitive regions. Veterinary-service inflation has outpaced general inflation by 60% since 2005, rising 8% year-over-year to August 2025, which has led to 3% declines in veterinary visits in 2023 as consumers defer care. Additionally, a veterinary workforce shortage and burnout—driven by high debt burdens and mental-health stress—threatens care accessibility; our models suggest up to 75% of pets may lack necessary care by 2030 without intervention. These restraints are partially mitigated by telehealth, AI-enabled diagnostics, and mid-level practitioner models that improve access and efficiency.
The market's product architecture is dominated by pet food and treats, which commanded 53.9% of global product revenue in 2025. Within food, dry formats lead on affordability and convenience, while fresh, functional, and grain-free diets capture premium share. Pet healthcare products—including parasiticides, supplements, and wellness devices—represent the fastest-growing product cluster, reflecting the preventive-care shift. Accessories (toys, housing, clothing, travel carriers) and hygiene products (litter, grooming supplies) constitute the balance, with hygiene showing strong innovation in natural and mineral-based litter solutions.
By pet type, dogs account for 40.4% of global revenue, supported by a vast range of tailored nutrition and accessory offerings. Yet cats are the fastest-growing segment at a 5.8% CAGR, driven by urbanization and apartment living, which favors feline companionship. In the U.S., dogs hold 63.42% share, while cats project 7.11% CAGR through 2031, underscoring the feline acceleration. Other species—fish, birds, small animals, and reptiles—remain niche but exhibit steady demand in specialized channels.
| Segment | 2025 Share / Metric | Growth Outlook (CAGR) | Key Insight |
|---|---|---|---|
| Pet Food & Treats | 53.9% of product revenue | 5.5–6.0% | Premiumization and fresh formats drive value |
| Pet Healthcare Products | ~18% of product revenue | 6.5–7.0% | Preventive care and supplements lead |
| Accessories & Housing | ~15% of product revenue | 4.5–5.0% | Travel and smart-tech accessories spur growth |
| Hygiene & Care Products | ~13% of product revenue | 5.0–5.5% | Natural litter and eco-friendly options gain |
| Dogs (pet type) | 40.4% global share | 5.6% | Largest companion animal segment |
| Cats (pet type) | ~30% global share | 5.8% | Fastest-growing; urbanization catalyst |
North America's dominance is structural, anchored in high pet ownership (94 million households), robust premium spending, and an advanced service ecosystem. The U.S. market alone is valued at USD 62.10 billion in 2025, projected to reach USD 91.74 billion by 2031 at a 6.72% CAGR, with pet products commanding 62.45% revenue share and services expanding at 6.98% CAGR. Offline retail retains 64.10% share, but online channels are growing at 7.55% CAGR, reshaping channel economics toward direct-to-consumer and subscription models.
Europe follows with a mature, sustainability-conscious consumer base. The region's growth is fueled by eco-friendly product innovation—biodegradable waste bags, organic food, recyclable toys—and strong regulatory standards. Asia-Pacific is the fastest-growing region, with emerging markets in China, India, and Southeast Asia witnessing rapid pet ownership growth, expanding middle classes, and increasing awareness of animal wellness. Latin America and the Middle East & Africa present nascent but promising opportunities, characterized by rising urbanization and the proliferation of pet specialty retail.
| Region | 2025 Revenue Share | Growth Profile | Strategic Priority |
|---|---|---|---|
| North America | 42.9% | Mature, premium-driven | Innovation and omnichannel integration |
| Europe | ~25% | Stable, sustainability-led | Eco-certification and premium nutrition |
| Asia-Pacific | ~22% | Fastest CAGR (6.5–7.0%) | Distribution expansion and localization |
| South America | ~6% | Emerging, price-sensitive | Affordable premium and education |
| Middle East & Africa | ~4% | Nascent, urban-centric | Infrastructure partnerships |
The pet care products market is moderately concentrated, with global majors and specialized challengers competing across nutrition, healthcare, and accessories. Mars, Incorporated and Nestlé S.A. (via Purina) lead in pet food, leveraging extensive portfolios and global distribution. Hill's Pet Nutrition and Royal Canin dominate premium and therapeutic nutrition, while Blue Buffalo and The J.M. Smucker Company hold strong positions in natural and mainstream segments. In retail and services, PetSmart LLC, Petco, and Chewy drive omnichannel engagement, with Chewy's autoship model reshaping subscription economics. A Place for Rover and Wag'n Tails exemplify the service ecosystem's expansion into mobile grooming, boarding, and walking.
Recent developments underscore the market's innovation and consolidation trajectory. In 2024, U.S. pet industry expenditures reached USD 158 billion, with 2026 projections at USD 165 billion. Pet insurance premiums exceeded USD 4 billion in 2024, yet only 4% of pets are insured, signaling vast headroom. Zoetis invested in a 32,000 sq ft reference lab in Louisville to scale AI-enabled diagnostics. The NAIC Model Act standardization in 14 states is enhancing insurance transparency. Meanwhile, sustainability-focused partnerships—such as Polish and Turkish manufacturers seeking European distributors for natural litter and private-label production—illustrate the globalization of supply chains and the rise of specialized, eco-conscious suppliers.
The pet care products market exhibits distinct trade patterns across product categories. Pet food and treats are increasingly traded globally, with the U.S., EU, and Thailand serving as major export hubs. Cat litter, particularly bentonite-based products, is a significant traded commodity; Türkiye has emerged as a leading manufacturer, with vertically integrated players exporting to over 80 countries and offering private-label production capacities exceeding 200,000 tons annually. European demand for natural and mineral-based odor neutralizers is rising, prompting Polish importers to seek international manufacturers for wet/dry food, treats, toys, and accessories. These dynamics highlight the importance of supplier partnerships, quality compliance, and flexible packaging in accessing regional markets.
Our analysis identifies three high-potential white spaces for investors and incumbents:
The value chain spans raw material extraction (e.g., bentonite, grains, proteins), manufacturing and formulation, branding, distribution (offline retail, e-commerce, clinics), and after-sales services. Procurement strategies increasingly emphasize supply chain resilience, with dual-sourcing for critical inputs and regional manufacturing to mitigate logistics risks. Vertically integrated suppliers—such as Turkish bentonite producers—offer cost and quality advantages, while private-label partnerships enable retailers to capture margin. Our primary research indicates that 68% of manufacturers are increasing investment in automation and quality certification (ISO, HACCP) to meet export standards, a trend expected to accelerate through 2033.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.9% from 2020-2034 |
| Segmentation |
|
By Distribution Channel
| By Geography |
|
The global pet care products market was valued at approximately USD 181.9 billion in 2025, with projections reaching USD 283.7 billion by 2033, growing at a CAGR of 5.9%.
Dogs lead the market with a 40.4% revenue share in 2025, though cats are the fastest-growing segment at a 5.8% CAGR.
Rising pet ownership among millennials and Gen Z, the pet humanization trend, and spending resilience—where over 50% of owners prioritize pet expenses over personal discretionary spending—are primary drivers.
North America accounted for 42.9% of global revenue in 2025, led by the U.S. market, which is projected to reach USD 91.74 billion by 2031.
High costs of pet ownership, veterinary-service inflation (rising 8% year-over-year to August 2025), and a veterinary workforce shortage that may leave up to 75% of pets without necessary care by 2030.
Online channels are growing rapidly, with a 7.55% CAGR projected through 2031 in the U.S., as consumers increasingly prefer convenience, subscription models, and direct-to-consumer options.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Executive Officer | 25% |
| VP of Product Development | 30% |
| Procurement Director | 25% |
| Regulatory Affairs Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Pet Food Manufacturers | 30% |
| Pet Healthcare Product Developers | 20% |
| Accessory & Hygiene Product Suppliers | 20% |
| Raw Material Suppliers | 15% |
| Omnichannel Retailers & Distributors | 15% |
 Related Reports
