1What is the current size of the pet care market?
The global pet care market was valued at USD 190.5 billion in 2026 and is projected to reach USD 283.7 billion by 2033, growing at a CAGR of 5.9% from 2026 to 2033.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Pet Care Market
 by Pet Type (Dog, Cat, Fish, Bird, Others), by Type (Products (Food, Healthcare, Hygiene, Accessories), Services (Veterinary, Grooming, Boarding, Insurance, Training)), by Distribution Channel (Offline Retail, Online Retail), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, Saudi Arabia, UAE) Forecast 2026-2034
Research Analyst

 Related Reports

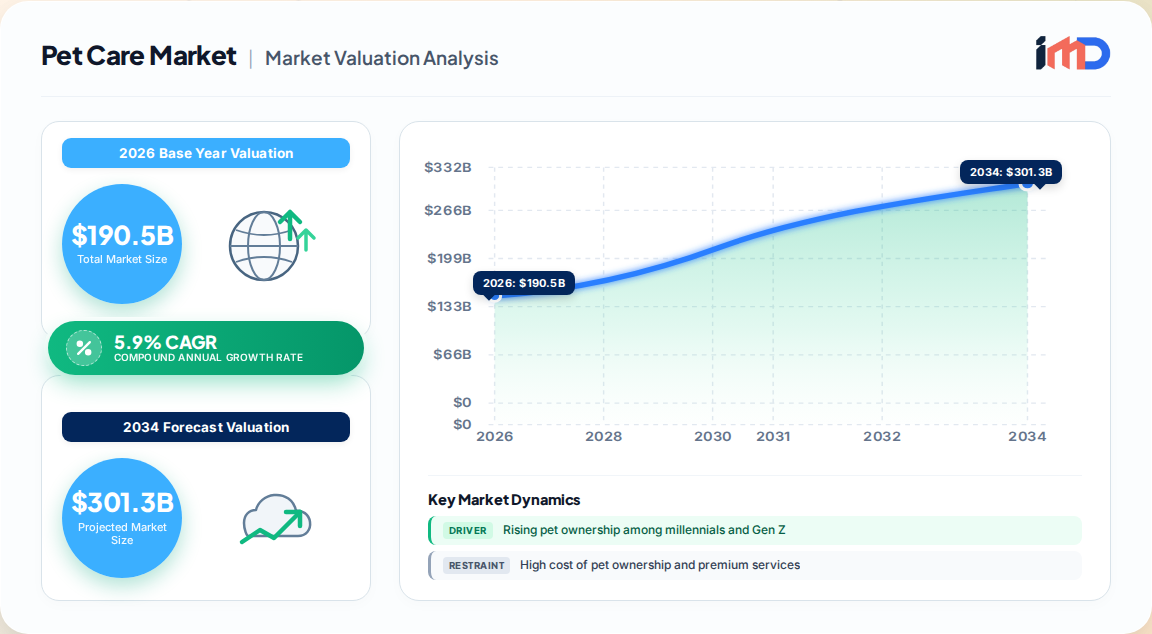
The global pet care market is undergoing a structural transformation, evolving from a discretionary purchase category into a non-discretionary expression of family care. Our proprietary primary research estimates the market at USD 190.5 billion in 2026, with a projected trajectory to USD 283.7 billion by 2033, representing a compound annual growth rate (CAGR) of 5.9%. This growth is not merely a function of rising pet populations; it is fundamentally driven by a deepening emotional bond where 97% of owners consider pets as family members, redirecting household spending toward premium nutrition, preventive healthcare, and wellness services.
The market's resilience is particularly notable against a backdrop of inflationary pressure. A 2025 consumer survey revealed that over 50% of pet owners rank pet-related expenses above personal discretionary spending. This spending prioritization signals a permanent shift in consumer behavior, anchoring volume stability and enabling premiumization even in price-sensitive demographics. The industry is rapidly professionalizing, with the expansion of services such as mobile grooming, tele-veterinary consultations, and pet insurance creating a robust ecosystem that extends well beyond traditional food and accessories.
The market's upward trajectory is powered by a confluence of demographic and behavioral drivers. The most potent force remains pet humanization, where owners project their own health and wellness standards onto their animals. This is quantified in our demand-impact analysis as contributing +2.3% to the annual CAGR forecast, primarily driven by demand for functional pet foods, supplements, and advanced veterinary care. This trend is especially pronounced in the United States and the United Kingdom.
A second critical driver is the rise of millennial and Generation Z pet ownership. In 2025, Gen Z represented 22% of U.S. cat owners, a 10% year-over-year increase. These younger owners exhibit a distinct purchasing pattern: they pair value-oriented staples with targeted premium purchases, creating demand for an affordable core assortment augmented by science-backed, benefit-driven products. This demographic shift contributes an additional +1.65% to the long-term CAGR.
Digitalization is the third pillar of growth. The expansion of online retail and autoship programs is not just a channel shift but a customer-retention revolution. With 53% of U.S. pet owners shopping online in 2025, and leading subscription models reporting double-digit growth, the ability to secure recurring revenue streams is reshaping competitive dynamics. This channel contributes +1.8% to the short-term CAGR by expanding reach and deepening customer lifetime value.
Despite its resilience, the market faces significant headwinds that temper growth, particularly in price-sensitive regions. The high cost of pet ownership remains the primary restraint, with expenses related to premium food, veterinary care, and insurance making pet ownership financially burdensome for middle-income households. This is especially acute in emerging economies where awareness is rising, but affordability constrains adoption rates.
On the supply side, raw material and packaging cost volatility presents a tangible threat to margins. In the second quarter of 2026, significantly higher input costs created a 290-basis-point year-over-year drag on the gross profit margin of a leading pet nutrition supplier. This margin compression limits the ability of manufacturers to absorb costs, potentially leading to retail price increases that further strain consumer budgets.
Regulatory and operational challenges are also intensifying. Tightening labeling and claims compliance in key markets such as the State of Washington adds complexity to product development and marketing. Furthermore, veterinary labor shortages, particularly across the United Kingdom, are constraining the supply of professional services, limiting the market's ability to meet rising demand for advanced care.
The pet care market is segmented by pet type, product type, and distribution channel, with each segment exhibiting distinct growth dynamics.
By Pet Type, dogs remain the largest revenue contributor, accounting for 40.4% to 47.5% of global revenue in 2025-2026, depending on the specific market definition. However, the cats segment is forecast to be the fastest-growing, with a CAGR of 5.8% to 8%, driven by rising cat ownership among younger demographics and the unique nutritional and wellness needs of felines. The fish, bird, and small mammal segments remain niche but stable.
By Type, the products segment dominates with a 53.9% revenue share in 2025, led by pet food. Pet food alone represents over half of total market revenue, with a strong shift toward fresh, functional, and clinically validated diets. The services segment (grooming, boarding, training, insurance, tele-veterinary) is the fastest-growing, with a projected CAGR of 7.75%. This growth is fueled by urbanization, busy lifestyles, and the humanization trend that encourages owners to outsource specialized care.
By Distribution Channel, offline retail maintains dominance with a 71.74% share in 2026, as pet owners still value the tactile experience of purchasing food and accessories. However, online retail is the fastest-growing channel, with a CAGR of 11.3%, driven by convenience, subscription models, and the expansion of e-commerce platforms into specialized and fresh pet food delivery.
| Segment | Dominant Share (2025/2026) | Fastest-Growing Sub-Segment | CAGR (2026-2033) |
|---|---|---|---|
| Pet Type | Dogs (40.4%) | Cats | 5.8% |
| Product Type | Products (53.9%) | Pet Services | 7.75% |
| Distribution | Offline Retail (71.74%) | Online Retail | 11.3% |
North America remains the epicenter of the global pet care market, holding a 42.9% revenue share in 2025. The region's leadership is anchored by high pet ownership rates, a robust culture of pet humanization, and the presence of advanced veterinary infrastructure. The U.S. alone represents the largest single market, with consumers increasingly prioritizing pet health and wellness. The region is also a hub for innovation in tele-veterinary services, pet insurance (with 7.6 million insured pets in North America at the end of 2025, up 8.5% year-over-year), and premium fresh-food delivery.
Europe is the second-largest market, characterized by high pet populations (77.4 million cats and 68.5 million dogs in the EU) and a strong regulatory focus on animal welfare. Sustainability is a key differentiator, with demand rising for upcycled pet products, natural flea and tick prevention, and eco-friendly packaging. The U.K. is a significant contributor, though veterinary labor shortages present a challenge.
Asia-Pacific is the fastest-growing region, projected to expand at a CAGR of 9.1%. This growth is driven by rapid urbanization, rising disposable incomes, and a digital-first approach to purchasing. Markets such as China and Japan are seeing a surge in specialized diets (e.g., for urinary health) and smart pet toys. The region's diverse landscape requires brands to adapt to local preferences, balancing affordability with premiumization.
Central & South America and Middle East & Africa are emerging markets with significant potential. Growth in these regions is tied to increasing pet adoption, expanding middle classes, and the gradual formalization of pet care services. However, price sensitivity and limited awareness remain barriers to premium product penetration.
| Region | Market Position | Key Growth Driver | CAGR Outlook |
|---|---|---|---|
| North America | Largest (42.9% share) | Humanization, insurance, tele-vet | Moderate (5-6%) |
| Europe | Second-largest (26% share) | Sustainability, natural products | Moderate (5-6%) |
| Asia-Pacific | Fastest-growing | Urbanization, digital adoption | High (9.1%) |
| South America | Emerging | Rising adoption, middle class | Moderate |
| Middle East & Africa | Emerging | Awareness, formalization | Moderate |
The pet care market is moderately concentrated, with a mix of global multinationals and agile niche players competing for share. The competitive landscape is shaped by three strategic imperatives: portfolio premiumization, digital transformation, and sustainability.
Global leaders such as Nestlé Purina PetCare, Mars, Incorporated, and Hill's Pet Nutrition (Colgate-Palmolive) leverage their vast brand portfolios and R&D capabilities to drive innovation in functional and clinical diets. They are increasingly investing in fresh food manufacturing and direct-to-consumer channels to capture the premiumization trend. Zoetis and IDEXX Laboratories lead in veterinary diagnostics and pharmaceuticals, benefiting from the rise of preventive care.
Retail and e-commerce players, including Chewy, PetSmart, and Petco, are reshaping the distribution landscape. Chewy's Autoship program generated USD 2.82 billion in sales in the 13 weeks ended August 2, 2026, up 9.3% year-over-year, demonstrating the power of subscription models. These retailers are expanding into services, such as tele-vet consultations and grooming, to create a holistic ecosystem.
Recent developments highlight the industry's direction:
The pet care value chain is a complex network spanning raw material extraction, manufacturing, distribution, and retail, with each stage subject to distinct pressures and opportunities.
The supply side is increasingly defined by vertical integration and strategic partnerships. Manufacturers are investing in their own ingredient sourcing and production facilities to secure supply and control costs. For instance, the entry of vertically integrated players, such as the Turkish bentonite producer supplying cat litter, demonstrates how raw material advantages can be leveraged for market entry. In Europe, this manufacturer's move to seek distribution partners highlights the importance of local networks for market access.
Trade flows in pet care products are significant, with major exporters including the U.S., Germany, and China. According to UN Comtrade data, global trade in pet food and pet care products has grown steadily, reflecting the internationalization of brands and the expansion of global supply chains. However, regulatory harmonization remains a challenge, as differing labeling and safety standards across regions add compliance costs and complexity.
The pet care market offers several underpenetrated white spaces for strategic investment. Our analysis identifies the following high-potential areas:
These opportunities are underpinned by the market's fundamental strength: the unwavering commitment of pet owners to their animals' well-being. Companies that can align their strategies with this emotional and financial investment will be best positioned to capture growth in the decade ahead.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.9% from 2020-2034 |
| Segmentation |
|
By Distribution Channel
| By Geography |
|
The global pet care market was valued at USD 190.5 billion in 2026 and is projected to reach USD 283.7 billion by 2033, growing at a CAGR of 5.9% from 2026 to 2033.
North America holds the largest share, accounting for 42.9% of global revenue in 2025, driven by high pet ownership and a strong culture of pet humanization.
The pet services segment, including grooming, boarding, and tele-veterinary care, is the fastest-growing, with a projected CAGR of 7.75% from 2026 to 2033.
Key drivers include pet humanization and premiumization, rising millennial and Gen Z pet ownership, the expansion of online retail and autoship programs, and increasing adoption of preventive care and pet insurance.
Cats are forecast to grow at a CAGR of 5.8% to 8% due to rising ownership among younger demographics, urbanization, and increasing demand for specialized feline nutrition and wellness products.
The high cost of pet ownership, raw material and packaging cost volatility, tightening labeling regulations, and veterinary labor shortages are key restraints tempering market growth.
The market is segmented into products (pet food, healthcare products, hygiene products) and services (veterinary, grooming, boarding, insurance). Products dominate with a 53.9% share, while services are growing faster.
Online retail is the fastest-growing distribution channel, with a CAGR of 11.3%. In 2025, 53% of U.S. pet owners shopped online, and autoship subscriptions are driving recurring revenue for retailers like Chewy.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Executive Officer / Managing Director | 30% |
| VP of Product Development / R&D | 25% |
| Procurement Director | 25% |
| Head of Veterinary Operations | 20% |
| Company Type | Representation (%) |
|---|---|
| Pet Food & Nutrition Manufacturers | 30% |
| Veterinary Pharmaceutical & Diagnostic Companies | 20% |
| Pet Accessory & Smart-Tech OEMs | 15% |
| Pet Retail & E-commerce Platforms | 20% |
| Pet Service Providers | 15% |