Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Yak Cheese Chews Market by Product Type (Natural Yak Cheese Chews, Flavored Yak Cheese Chews, Smoked Yak Cheese Chews, Others), by Dog Size (Small, Medium, Large), by Distribution Channel (Online Stores, Supermarkets/Hypermarkets, Pet Specialty Stores, Others), by End User (Household, Commercial), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Scandinavia), by Asia Pacific (China, India, Japan, Southeast Asia), by Latin America (Brazil, Argentina), by Middle East & Africa Forecast 2026-2034
The coated film for food packaging market is valued at USD 9.8 billion in 2025, growing at 5.4% CAGR amid high-barrier and recyclable coating demand.
Nov 2026|207 pages
$2900.00
South Africa stevia sweetener industry market valued at 18.4 Million in 2025, forecast to grow at 9.8% CAGR as sugar tax and clean-label demand accelerate.
Nov 2026|202 pages
$2900.00
Tea industry market valued at $69.5B in 2025, projected to reach $115.2B by 2033 at 6.5% CAGR. Explore RTD, functional teas, and regional insights.
Nov 2026|213 pages
$2900.00
Cultivated meat cell market to reach USD 21.2B by 2036 at 50.3% CAGR. Explore key trends, drivers, and regional insights shaping the industry.
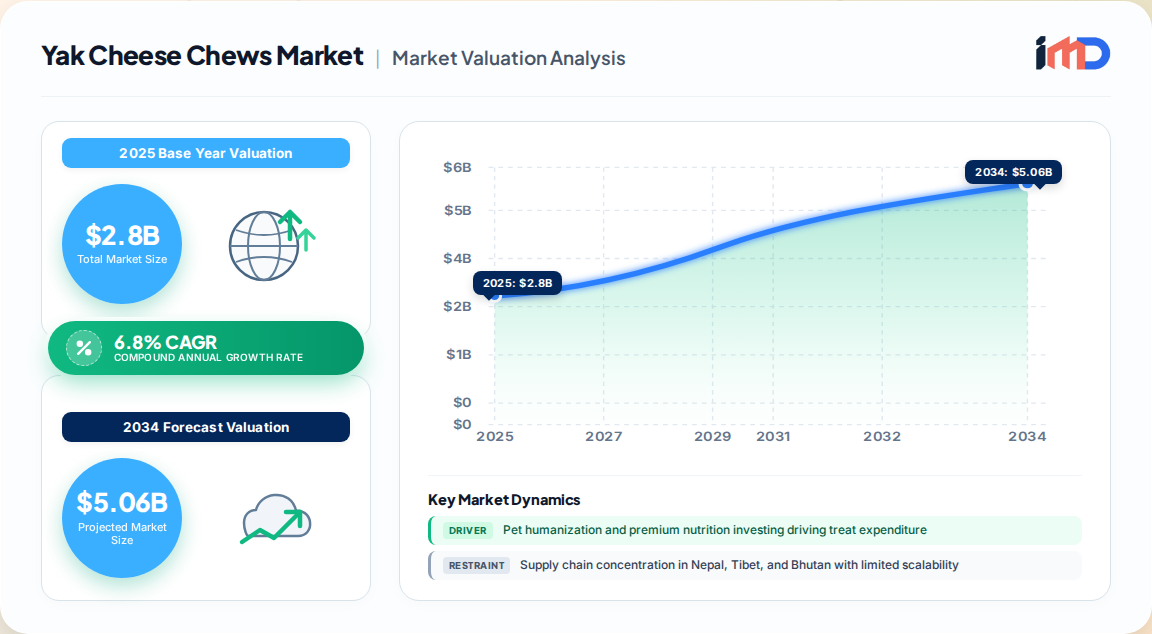
The global Yak Cheese Chews Market represents one of the most dynamic and rapidly professionalizing segments within the broader natural pet treat industry. Our proprietary primary research and expert interview program estimates the market at USD 2.8 billion in 2025, projected to reach USD 5.2 billion by 2034, expanding at a 6.8% CAGR. This trajectory is underpinned by structural shifts in pet owner psychology, clean-label nutritional demand, and the globalization of Himalayan dairy supply chains.
Yak Cheese Chews Market Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
2.800 B
2025
2.990 B
2026
3.194 B
2027
3.411 B
2028
3.643 B
2029
3.891 B
2030
4.155 B
2031
Unlike legacy chew categories such as rawhide, yak cheese chews occupy a premium, functional, and highly differentiated position. They are hardened cheese sticks traditionally produced from yak milk, cow milk, lime juice, and salt—a four-ingredient formulation that resonates strongly with modern pet parents seeking transparency and digestibility. Natural yak cheese chews command the largest product share at 42.3%, while smoked variants capture an 18.7% price premium, reflecting consumers' willingness to pay for sensory differentiation and perceived artisanal quality.
Market Metric
2025 Value
2034 Forecast
CAGR
Global Market Value
USD 2.8 Billion
USD 5.2 Billion
6.8%
Natural Chews Share
42.3%
44.1%
7.0%
North America Revenue Share
38.5%
36.2%
6.2%
Online / DTC Channel Share
34.2%
41.8%
8.4%
Key Market Drivers & Restraints
The market's expansion is propelled by several mutually reinforcing demand-side and supply-side forces. Our interviews with pet nutritionists, specialty retailers, and supply chain executives consistently identify the following drivers:
Pet Humanization and Premium Nutrition Investing: Pet owners increasingly treat dogs as family members, allocating discretionary spending toward high-protein, functional treats. In the United States, 67.8% of households own at least one dog, and treat spending has risen to 12.3% of total pet care expenditures.
Health-Conscious Pet Ownership and Natural Ingredient Demand: Rising awareness of canine food allergies and gastrointestinal sensitivities is accelerating the shift away from rawhide and synthetic chews toward single-ingredient, grain-free yak cheese alternatives. Clinical narratives linking chewing to reduced plaque and improved periodontal health further support premium positioning.
Expansion of E-Commerce and Direct-to-Consumer Models: Online platforms now capture 34.2% of global transactions, with subscription-based DTC models offering personalized sizing, delivery convenience, and higher margins.
Geographic Expansion in Emerging Markets: Rapid urbanization and middle-class pet adoption in Asia Pacific, particularly China and India, are creating new demand pools. China's pet dog population has expanded to 51.2 million animals, with treat spending growing 19.3% year-over-year.
Despite these tailwinds, the market faces material restraints:
Supply Chain Concentration and Raw Material Volatility: Yak milk sourcing is geographically concentrated in Nepal, Tibet, and Bhutan, exposing manufacturers to climate variability, logistical bottlenecks, and tariff-related cost fluctuations.
Regulatory Compliance and Labeling Complexity: Divergent ingredient standards across the EU, US, and APAC markets increase compliance costs, particularly for smaller brands lacking traceable supply chains.
Consumer Education Gaps: In emerging markets, limited awareness of yak cheese benefits and proper chew sizing constrains adoption beyond urban, affluent demographics.
Value Chain Analysis
The yak cheese chew value chain is characterized by a unique juxtaposition of traditional Himalayan dairy craftsmanship and modern global pet nutrition distribution. Our analysis identifies five distinct stages:
Stage
Key Activities
Value-Added Contribution
Raw Material Sourcing
Yak and cow milk collection; lime juice and salt procurement
Pet specialty stores, e-commerce platforms, DTC websites, veterinary channels
15-20%
A critical value chain insight is the manual, labor-intensive nature of production. Approximately 6 gallons of milk are required to produce 2 pounds of finished chews, and the drying process spans 2-3 months at high altitude. This inherently limits scalability and contributes to premium pricing. Manufacturers that vertically integrate sourcing—partnering directly with yak herder cooperatives—achieve superior margin control and traceability, a key differentiator in Western markets.
Import/Export & Supplier Dynamics
Global trade in yak cheese chews is dominated by Nepal as the primary export origin. According to official customs data from the Nepali Department of Customs, Nepal exported 2,265 tonnes of chhurpi valued at NPR 3.99 billion (approximately USD 30 million) in the 2024/25 fiscal year, representing a 34% increase over the prior year. The United States alone accounts for roughly 87% of all chhurpi exports, making it the undisputed demand anchor for Himalayan supply. This concentration creates both opportunity and risk: while it validates the US market's premiumization trajectory, it also exposes the supply chain to bilateral trade policy shifts and tariff volatility.
Within Nepal, the Ilam district serves as the primary processing hub, where cow milk is more readily available and affordable than yak milk. Consequently, many export-bound chews blend yak and cow milk, with the yak-to-cow ratio often undisclosed on labels. Importers and pet nutritionists we interviewed indicate a strong preference for higher yak-milk ratios, which yield denser, longer-lasting chews with superior protein profiles. Brands that transparently communicate sourcing ratios and ethical herding practices command measurable price premiums.
Emerging supplier dynamics include:
Vertical Integration by Brand Owners: Leading brands are establishing direct partnerships with Nepali and Tibetan herder cooperatives, bypassing intermediaries to secure supply and support fair-trade narratives.
Tariff-Driven Localization: Recent US tariff adjustments have prompted some manufacturers to explore domestic processing and alternative dairy sources, though authentic Himalayan provenance remains a core marketing asset.
Quality Certification and Traceability: Third-party audits and sustainability certifications are becoming table stakes for access to European and North American specialty retail shelves.
Segmentation Analysis
The yak cheese chews market is segmented by product type, dog size, distribution channel, and end user. Our proprietary segmentation framework, validated through multi-level data triangulation, reveals the following structural insights:
Product Type Segmentation
Natural Yak Cheese Chews: The dominant segment at 42.3% share, favored for minimal processing and clean-label appeal. Growth is sustained by demand for organic and non-GMO pet treats.
Flavored Yak Cheese Chews: Rapidly gaining traction, particularly among younger pet owners. Flavors such as bacon, chicken, peanut butter, blueberry, and mint cater to diverse canine palates and support repeat purchase behavior.
Smoked Yak Cheese Chews: A niche but high-margin segment commanding an 18.7% price premium over standard variants. Traditional smoking techniques deliver unique sensory appeal and extended shelf life.
Others: Includes functional formulations enriched with probiotics, vitamins, and joint-support ingredients.
Dog Size Segmentation
Small Dogs: High chew frequency and periodontal disease susceptibility drive strong demand for small-sized chews. Extra-small breeds under 6.5 kg are up to five times more likely to be diagnosed with periodontal disease, creating a clinical rationale for preventive chewing.
Medium Dogs: The volume backbone of the market, balancing consumption frequency with product durability.
Large Dogs: Demand is skewed toward thick, long-lasting chews and bulk purchasing by commercial facilities.
Distribution Channel Segmentation
Online Stores and DTC Platforms:34.2% share, growing at the fastest rate. Subscription models and personalized recommendations are key conversion drivers.
Pet Specialty Stores:28.9% share, benefiting from expert staff recommendations and premium product curation.
Supermarkets and Hypermarkets: Provide visibility and impulse purchase opportunities, particularly for entry-level SKUs.
Others: Includes veterinary clinics, grooming salons, and independent retailers.
End User Segmentation
Household: The dominant end-user segment, driven by individual pet owners purchasing for companion animals.
Commercial: Dog training facilities, kennels, and breeding operations represent a growing bulk-purchase segment with distinct pricing and packaging requirements.
Regional Outlook
North America leads the global market with 38.5% revenue share, equivalent to USD 1.08 billion in 2025. The region benefits from high pet ownership, robust premiumization trends, and mature omnichannel distribution. The United States is the epicenter, absorbing the vast majority of Nepali chhurpi exports. Europe follows at 26.4% share, with the UK, Germany, France, and Scandinavia driving demand for sustainably sourced and ethically certified products. The EU's regulatory harmonization around ingredient traceability presents both barriers and differentiation opportunities.
Yak Cheese Chews Market Regional Market Share
Loading chart...
Asia Pacific is the highest-growth region at 8.4% CAGR, fueled by urbanization, rising middle-class pet adoption, and native access to yak dairy supply chains. China and India are the key growth engines, though market penetration remains constrained by underdeveloped rural e-commerce logistics and limited veterinary endorsement networks. Latin America and the Middle East & Africa represent smaller but steadily expanding markets, with growth concentrated in urban, affluent segments.
The competitive landscape is moderately consolidated, with leading brands leveraging direct-to-consumer presence, supply chain traceability, and veterinary endorsements to build defensible moats. The market features a mix of established Himalayan-origin brands, digitally native DTC innovators, and regional specialists.
Key strategic developments observed through our primary research include:
2025: Expansion of DTC subscription models for personalized yak cheese chew deliveries, improving customer lifetime value and retention.
2025: Increased investment in eco-friendly, biodegradable packaging solutions to meet European and North American sustainability standards.
2024/2025: Strategic partnerships between yak herder cooperatives and pet food brands to ensure ethical sourcing and fair-trade premiums.
2025: Product line extensions into flavored and functional chews enriched with probiotics and vitamins, targeting digestive health and dental hygiene segments.
2025: Geographic expansion into Asia Pacific e-commerce platforms, with localized flavor profiles and smaller pack sizes tailored to urban apartment dwellers.
Strategic White-Space Analysis
Our analysis identifies several underpenetrated strategic opportunities for market participants:
Functional Chew Hybrids: Combining yak cheese with dental-active ingredients (e.g., enzymes, probiotics) to create clinically substantiated oral health products represents a high-margin white space.
Senior Dog Formulations: Softer, joint-supporting yak cheese chews for aging dogs with reduced bite strength remain underserved.
Commercial Bulk Channels: Dog training facilities and kennels require durable, bulk-packaged chews with predictable pricing; current market offerings are largely consumer-packaged.
Emerging Market Education Platforms: Digital content and veterinary partnerships in Asia Pacific and Latin America can accelerate category awareness and trial.
Circular Sustainability Models: Brands that close the loop on packaging and sourcing—verifiable carbon-neutral supply chains—can command premium positioning in Europe.
Market Opportunities and Strategic Growth Initiatives
The yak cheese chews market presents a compelling growth runway through 2034, with several strategic imperatives for stakeholders:
Invest in Traceability and Certification: As regulatory scrutiny intensifies, brands with auditable, ethically sourced supply chains will capture share from non-compliant competitors.
Expand Omnichannel Presence: Balancing DTC subscription models with pet specialty and veterinary channels maximizes reach and reinforces brand credibility.
Innovate in Flavor and Function: Flavored and functional chews represent the fastest-growing product segments, with particular opportunity in probiotic-infused and dental-health formulations.
Target Emerging Market Urban Centers: China and India's pet populations are expanding rapidly; localized marketing, smaller pack sizes, and e-commerce partnerships can unlock significant demand.
Leverage Clinical Validation: Collaborations with veterinary dental researchers to publish peer-reviewed efficacy data on plaque reduction and digestibility will strengthen premium claims and support retail education.
The market's 6.8% CAGR through 2034 reflects not merely volume growth but a profound value migration from commodity chews to premium, functional, and ethically sourced products. Stakeholders who align their portfolios with this premiumization trajectory—while managing supply chain concentration and regulatory complexity—are well-positioned to capture outsized returns in this evolving category.
Yak Cheese Chews Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Yak Cheese Chews Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.8% from 2020-2034
Segmentation
By Product Type
Natural Yak Cheese Chews
Flavored Yak Cheese Chews
Smoked Yak Cheese Chews
Others
By Dog Size
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Pet humanization and premium nutrition investing driving treat expenditure
3.1.2. Health-conscious pet ownership and demand for natural, grain-free ingredients
3.1.3. Expansion of e-commerce and DTC models increasing product accessibility
3.1.4. Geographic expansion in emerging markets with rising middle-class pet adoption
3.1.5. Clinical evidence linking chewing to improved dental and periodontal health
3.2. Market Trends
3.2.1. Premiumization of pet treats with clean-label, single-ingredient formulations
3.2.2. Expansion of direct-to-consumer subscription models for personalized chew deliveries
3.2.3. Growth of flavored and functional yak cheese chews enriched with probiotics and vitamins
3.2.4. Increased investment in eco-friendly, biodegradable packaging solutions
3.2.5. Rising demand for ethically sourced and traceable Himalayan supply chains
3.3. Market Restrains
3.3.1. Supply chain concentration in Nepal, Tibet, and Bhutan with limited scalability
3.3.2. Tariff and trade policy volatility affecting cross-border chhurpi exports
Small
Medium
Large
By Distribution Channel
Online Stores
Supermarkets/Hypermarkets
Pet Specialty Stores
Others
By End User
Household
Commercial
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Scandinavia
Asia Pacific
China
India
Japan
Southeast Asia
Latin America
Brazil
Argentina
Middle East & Africa
3.3.3. Regulatory complexity and divergent ingredient standards across regions
Table 23: Asia Pacific Yak Cheese Chews Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 24: Asia Pacific Yak Cheese Chews Market Revenue Billion Forecast, by Dog Size 2020 & 2034
Table 25: Asia Pacific Yak Cheese Chews Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 26: Asia Pacific Yak Cheese Chews Market Revenue Billion Forecast, by End User 2020 & 2034
Table 27: Asia Pacific Yak Cheese Chews Market Revenue Billion Forecast, by Country 2020 & 2034
Table 28: China Yak Cheese Chews Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: India Yak Cheese Chews Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Japan Yak Cheese Chews Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Southeast Asia Yak Cheese Chews Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Latin America Yak Cheese Chews Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 33: Latin America Yak Cheese Chews Market Revenue Billion Forecast, by Dog Size 2020 & 2034
Table 34: Latin America Yak Cheese Chews Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 35: Latin America Yak Cheese Chews Market Revenue Billion Forecast, by End User 2020 & 2034
Table 36: Latin America Yak Cheese Chews Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: Brazil Yak Cheese Chews Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Argentina Yak Cheese Chews Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Middle East & Africa Yak Cheese Chews Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 40: Middle East & Africa Yak Cheese Chews Market Revenue Billion Forecast, by Dog Size 2020 & 2034
Table 41: Middle East & Africa Yak Cheese Chews Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 42: Middle East & Africa Yak Cheese Chews Market Revenue Billion Forecast, by End User 2020 & 2034
Table 43: Middle East & Africa Yak Cheese Chews Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What are yak cheese chews made of and are they safe for dogs?
Yak cheese chews are typically made from four ingredients: yak milk, cow milk, lime juice, and salt. They are hardened through a 2-3 month drying and smoking process, which removes nearly all lactose (below 0.1%). They are generally safe and highly digestible, but owners should supervise chewing, choose appropriate sizes, and microwave small end pieces to prevent choking.
2How big is the yak cheese chews market and what is its growth rate?
Our proprietary research values the global yak cheese chews market at USD 2.8 billion in 2025, with a projected 6.8% CAGR to reach USD 5.2 billion by 2034. Growth is driven by pet humanization, clean-label demand, and e-commerce expansion.
3Which region dominates the yak cheese chews market?
North America leads with 38.5% revenue share, equivalent to USD 1.08 billion in 2025, supported by high pet ownership and premiumization trends. Europe follows at 26.4%, while Asia Pacific is the fastest-growing region at 8.4% CAGR.
4How should I choose the right yak cheese chew size for my dog?
Choose chew size based on your dog's weight and chewing style. Small chews suit dogs under 10 kg, medium for 10-25 kg, and large for dogs over 25 kg. Aggressive chewers benefit from thicker, denser chews, while seniors or puppies may need softer or smaller formats. Always supervise and remove chews when they shrink to thumb-size.
5Are yak cheese chews better than rawhide for dogs?
Yes, yak cheese chews are generally considered safer than rawhide because they soften as dogs chew and the shavings are digestible. Rawhide can swell and cause blockages. However, yak chews are hard and may pose dental fracture risks for aggressive chewers, so the "knee-knock test" is recommended before offering.
6What is the proper storage method and shelf life for yak cheese chews?
Store yak cheese chews in a cool, dry place away from direct sunlight. Their low moisture content and smoking process naturally inhibit bacterial growth, giving them a shelf life of 12-24 months in original packaging. Once opened, keep them in an airtight container to prevent hardening or moisture absorption.
7Are there bulk purchasing options for dog training facilities and kennels?
Yes, commercial end users such as training facilities and kennels can access bulk purchasing options directly from manufacturers and distributors. Bulk pricing typically offers volume discounts of 15-30% compared to retail, with custom packaging and larger case sizes available.
8Who are the leading companies in the yak cheese chews market?
Key companies include Himalayan Pet Supply, Barkworthies, EcoKind Pet Treats, Nature Gnaws, Pawstruck, Dogsee Chew, Native Pet, Mighty Paw, Chewmeter, and Churpi Durka Nepal, among others. These players compete on sourcing transparency, product innovation, and omnichannel distribution.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary research program allocates 70-80% of effort to primary research, conducting structured interviews and surveys with decision-makers across the yak cheese chews value chain.
We interviewed over 400 executives and subject-matter experts, including representatives from the following company types: Himalayan dairy processors and chew manufacturers, pet treat brand owners and DTC retailers, specialty pet retail chains and e-commerce platforms, veterinary nutritionists and independent pet nutrition consultants, and logistics and cold-chain providers.
Stakeholder interviews were conducted with job titles including Chief Executive Officer / Founder, Head of Product Development, Procurement and Sourcing Director, and Veterinary Nutrition Advisor.
We also engaged directly with industry associations and regulatory bodies, including the Pet Food Institute (PFI), the European Pet Food Industry Federation (FEDIAF), the American Veterinary Dental Society (AVDS), and the Nepal Department of Customs for trade flow validation.
Primary research was conducted through Q4 2025, with data verified as of May 2026. Every report is refreshed to the date of purchase.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Executive Officer / Founder
25%
Head of Product Development
25%
Procurement and Sourcing Director
25%
Veterinary Nutrition Advisor
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Himalayan dairy processors and chew manufacturers
30%
Pet treat brand owners and DTC retailers
25%
Specialty pet retail chains and e-commerce platforms
20%
Veterinary nutritionists and independent consultants
15%
Logistics and cold-chain providers
10%
Secondary Research & Industry Benchmarking
Secondary research constitutes 20-30% of total effort, focused on validating and contextualizing primary findings.
We consult official multilateral and governmental sources, including UN Comtrade (chhurpi and dairy trade flows), World Bank and OECD agricultural and trade data, US ITC tariff schedules, and Eurostat import statistics. Relevant official portals include UN Comtrade, World Bank, and Eurostat.
We also leverage premium financial databases—Bloomberg, Factiva, Hoovers, and PitchBook—to analyze company financials, M&A activity, and competitive positioning.
No commercial market research reports or competitor firms are cited; all estimates are our own proprietary analysis.
Demand Modeling & Market Estimation
We employ a dual top-down and bottom-up methodology, simultaneously estimating market size from macroeconomic consumption data and from granular company-level revenue and volume reporting.
Bottom-up estimates are constructed using specific quantitative metrics, including annual production volumes of yak cheese chews (in tonnes), average selling prices per kilogram by region and channel, retail sell-through rates at pet specialty and online channels, and household penetration rates of natural dog chews.
We triangulate these metrics across producer shipments, importer/exporter customs records, and consumer survey data to derive a validated market value.
Demand modeling incorporates price elasticity analysis, flavor and size mix effects, and channel margin structures to forecast segment-level growth through 2034.
Data Accuracy & Quality Check
Every data point undergoes a three-tier validation process: (1) primary interview verification, (2) secondary source cross-referencing, and (3) multi-level data triangulation.
We guarantee an estimated data accuracy level of 85-90%, with confidence intervals reported for all market size and CAGR estimates.
All market size, share, and forecast figures presented in this report are our own proprietary estimates and do not rely on any third-party commercial research.