Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Vietnam Facility Management Industry Market Size & Outlook 2031
Vietnam Facility Management Industry
Real Estate and Construction / MARKET REPORT
Vietnam Facility Management Industry | Insight Market Data
Vietnam Facility Management Industry by Service Type (Hard Services(Asset Management, MEP Maintenance, HVAC, Electrical, Plumbing), Soft Services(Cleaning, Security, Office Support, Landscaping, Catering)), by Offering Type (In-House, Outsourced(Single FM, Bundled FM, Integrated FM)), by End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Industrial and Process, Healthcare, Others), by Northern Vietnam (Hanoi, Bac Ninh, Hai Phong), by Central Vietnam (Da Nang, Hue), by Southern Vietnam (Ho Chi Minh City, Binh Duong, Dong Nai) Forecast 2026-2034
Executive Overview: Vietnam Facility Management Industry Market
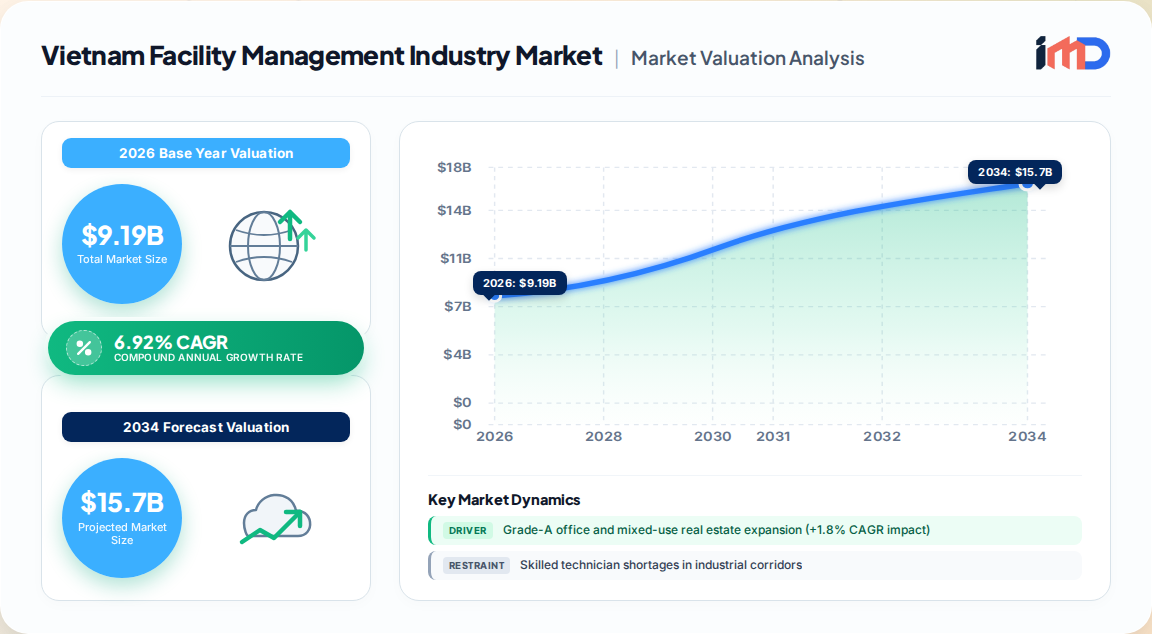
The Vietnam facility management (FM) industry market represents a rapidly professionalizing ecosystem that coordinates hard services (MEP maintenance, asset management), soft services (cleaning, security, workplace support), and integrated delivery models across the country's built environment. Our proprietary primary research and expert interview program estimates the market at USD 9.19 billion in 2026, expanding to USD 12.84 billion by 2031 at a 6.92% CAGR. This places Vietnam among Southeast Asia's fastest-growing FM markets, underpinned by an industrial construction boom, Grade-A office completions, and state infrastructure concessions that stipulate lifecycle operations.
Vietnam Facility Management Industry Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.595 B
2025
9.190 B
2026
9.826 B
2027
10.51 B
2028
11.23 B
2029
12.01 B
2030
12.84 B
2031
The structural transformation is unambiguous: FM is shifting from labor-led, single-service contracting toward bundled and integrated contracts that demand uptime guarantees, ESG reporting, and digital telemetry. Outsourced penetration is projected to rise from 74% in 2025 to 80% by 2031, while integrated contracts climb from 24% to 30% of revenue. Vietnam had more than 600 certified green buildings covering nearly 17 million square metres by Q3 2025, and over 400 industrial zones were operating or under development. These assets form the addressable base for recurring, compliance-intensive facility services.
Fastest-growing service type: Soft services at 7.32% CAGR
Fastest-growing delivery model: Outsourced FM at 7.46% CAGR
Fastest-growing end-user vertical: Institutional and public infrastructure at 7.28% CAGR
Market concentration: Low, with 4,280+ active providers
Market Drivers: Industrialization, China+1, and Grade-A Real Estate
Vietnam's FM demand is being reshaped by five measurable forces. Our driver impact model assigns the following contributions to forecast CAGR:
Driver
Impact on CAGR
Geographic Relevance
Timeline
Grade-A office and mixed-use stock expansion
+1.8%
Ho Chi Minh City, Hanoi, Da Nang
Medium term (2–4 years)
Manufacturing and logistics growth (China+1, FTAs)
+1.5%
Binh Duong, Dong Nai, Bac Ninh, Hai Phong
Long term (≥4 years)
Hyperscale data-center build-out
+1.2%
HCMC, Hanoi, Binh Duong spillover
Short term (≤2 years)
Smart-city and infrastructure PPP initiatives
+1.0%
National; early gains in HCMC, Hanoi, Da Nang
Long term (≥4 years)
Cost-optimization outsourcing in state and private enterprises
+0.9%
Hanoi, HCMC SOEs
Medium term (2–4 years)
Green-building and energy-efficiency certification demand
+0.6%
Grade-A towers in HCMC, Hanoi
Medium term (2–4 years)
Grade-A inventory in Ho Chi Minh City and Hanoi climbed 18% between 2024 and 2025, adding more than 1.2 million m² of premium space requiring sophisticated MEP upkeep and life-safety compliance. Developers are pre-negotiating five-to-ten-year integrated contracts, often linking payment to LEED or LOTUS certification milestones that deliver 10–15% rental premiums.
Foreign capital of USD 22.8 billion flowed into manufacturing in 2025, stimulating the build-out of 15 million m² of factories and logistics hubs across Binh Duong, Bac Ninh, and Hai Phong. Semiconductor assembly, battery production, and textile finishing lines mandate ISO-class cleanrooms, hazardous-waste handling, and 24/7 HVAC monitoring, expanding the hard-services wallet. Reduced tariffs under RCEP and the EU-Vietnam Free Trade Agreement — which eliminated 99% of tariffs and entered into force on 1 August 2020 — lock in long-run export competitiveness and a steady pipeline of facilities requiring uptime above 98% and environmental compliance audits.
Data-center capacity is rising 25% annually as cloud and telecom providers race to serve Vietnam's digital economy. The newly commissioned 30-MW Viettel IDC site and the upcoming 20-MW CMC Telecom campus specify 99.99% uptime, demanding redundant chillers, N+1 power, and real-time BMS integration. Each additional megawatt adds roughly USD 1.5 million in annual facility-services revenue, making hyperscale projects a high-margin niche. Twenty-four municipalities are piloting smart-city programs, with USD 67 billion earmarked through 2030 for metros, airports, and IoT-enabled civic buildings; PPP concessions transfer 15-to-25-year operations risk to private consortiums.
Restraints and Challenges: Labor, Integration Costs, and Cybersecurity
Skilled labor shortages: Technician density is concentrated in HCMC and Hanoi, but industrial corridors face chronic gaps in HVAC, electrical, and BMS specialists. Wage inflation for certified technicians is pressuring margins in single-service contracts.
High upfront integration costs: Bundling legacy systems into integrated FM platforms requires capital for CMMS deployment, IoT sensors, and staff retraining — a barrier for mid-tier providers.
Cybersecurity risks in connected buildings: As BMS and IoT telemetry proliferate, data governance and OT security become board-level concerns; providers lacking certified controls face exclusion from Grade-A and data-center contracts.
Fragmented competitive structure: With 4,280+ players, price competition in soft services remains intense, and consolidation is only beginning.
Regulatory complexity: Green-building mandates (LOTUS, EDGE) and PPP performance clauses require contractual sophistication that many domestic providers lack.
Service Type and Delivery Model Segmentation
Hard services led with 58.34% of market share in 2025, reflecting sustained capital spending on HVAC, electrical, and mechanical systems maintenance across industrial and commercial assets. Soft services are advancing at 7.32% CAGR through 2031 — the fastest pace among service types — as occupant-experience standards rise and landlords bundle cleaning, security, and workplace support into single scopes.
By offering type, in-house teams controlled 53.67% of market size in 2025, but outsourced FM is projected to expand at 7.46% CAGR to 2031. Within outsourcing, single FM remains the largest contract category, but bundled and integrated FM are gaining share as clients consolidate technical, soft-service, energy, and workplace contracts under single governance. Integrated contracts are projected to represent 30% of market revenue by 2031, up from 24% in 2025.
Segment
2025 Share / Metric
2031 Outlook
Hard services
58.34% share
Largest, steady growth
Soft services
7.32% CAGR
Fastest-growing service type
In-house FM
53.67% share
Declining share
Outsourced FM
7.46% CAGR
80% penetration by 2031
Integrated contracts
24% of revenue
30% of revenue
Managed floor area
205.0 million m²
279.5 million m²
End-User Industry Analysis: Commercial, Industrial, and Institutional
Commercial real estate captured 36.27% of total spending in 2025, driven by Grade-A offices, retail, and mixed-use developments. Institutional and public infrastructure is forecast to post the quickest growth at 7.28% CAGR between 2026 and 2031, supported by PPP concessions, hospitals, universities, and smart-city civic buildings. Industrial and process facilities — factories, logistics hubs, cleanrooms, and data centers — represent the most compliance-intensive vertical, with uptime requirements above 98% and environmental audits embedded in contracts.
Demand is concentrated in Ho Chi Minh City, Hanoi, and the northern and southern industrial corridors. More than 400 industrial zones were operating or under development by 2025, while the managed floor-area base is projected to rise from approximately 205.0 million m² in 2025 to 279.5 million m² by 2031. Average service revenue per managed square metre is increasing through inflation, digital monitoring, and higher compliance intensity — a positive value-intensity effect that supports the 6.92% CAGR despite slower floor-area growth of approximately 5.3%.
Regional Outlook: Northern, Central, and Southern Vietnam
Southern Vietnam, anchored by Ho Chi Minh City and the Binh Duong–Dong Nai industrial belt, accounts for the largest share of FM revenue. The region benefits from the deepest technician density, the highest concentration of Grade-A offices, and spillover demand from hyperscale data centers. Northern Vietnam, centered on Hanoi and the Bac Ninh–Hai Phong manufacturing corridor, is the fastest-growing region, propelled by electronics and semiconductor FDI and a wave of new Grade-A office completions. Central Vietnam, led by Da Nang, is emerging as a regional headquarters and tourism hub, stretching FM demand beyond the Hanoi–HCMC corridor.
Vietnam Facility Management Industry Regional Market Share
Loading chart...
Southern Vietnam: ~45% of market revenue; HCMC and industrial corridors; Grade-A offices, data centers, logistics.
Northern Vietnam: ~38% of market revenue; Hanoi and Bac Ninh–Hai Phong; electronics, semiconductor, and industrial parks.
Central Vietnam: ~17% of market revenue; Da Nang and Hue; hospitality, regional HQs, public infrastructure.
Competitive Landscape and Strategic Developments
The Vietnam FM market is low-concentration, with 4,280+ providers ranging from international integrated FM majors to domestic single-service specialists. Competitive advantage is shifting toward providers with national technician networks, computerized maintenance management systems (CMMS), energy-management expertise, transparent KPI reporting, and the financial capacity to mobilize complex multi-site contracts. International players bring global best practices and ESG reporting capability; domestic providers offer cost competitiveness and local labor relationships.
2025: A 30-MW Viettel IDC site commissioned, specifying 99.99% uptime and N+1 power — a benchmark for critical-environment FM.
2025: Vietnam surpassed 600 certified green buildings covering nearly 17 million m², raising the bar for energy-performance contracting.
2026: The EU-Vietnam Free Trade Agreement tariff phase-out continued, with Vietnam removing the remainder of EU duties by 2030, reinforcing export manufacturing demand.
2026: Integrated FM contract share reached 25%, up from 24% in 2025, as large clients consolidated suppliers.
Value Chain and Procurement Dynamics
The FM value chain in Vietnam comprises five tiers: (1) asset owners and developers (real estate, industrial park operators, government PPP sponsors); (2) FM providers (integrated, bundled, single-service); (3) subcontractors (cleaning, security, landscaping, MEP specialists); (4) technology and equipment suppliers (BMS, IoT sensors, HVAC OEMs, CMMS platforms); and (5) labor and training institutions. Value is migrating toward providers that own the client interface and data layer while subcontracting commoditized soft services.
Procurement is increasingly outcome-based, with contracts tying compensation to measurable KPIs such as guaranteed energy-efficiency baselines, asset uptime percentages, and occupant satisfaction metrics. Landlords pre-negotiate five-to-ten-year integrated contracts, often linking payment to LEED or LOTUS certification milestones. Public procurement under PPP concessions transfers 15-to-25-year operations risk to private consortiums, creating long-duration revenue visibility for capable providers.
Strategic White-Space Analysis
Critical-environment FM for data centers: With capacity rising 25% annually and each megawatt adding ~USD 1.5 million in annual services revenue, providers with N+1 power and AI-enabled cooling optimization expertise face a high-margin niche with limited competition.
Energy-as-a-Service (EaaS) and green certification: Only a handful of providers can deliver LOTUS/EDGE-aligned energy-performance contracting; this is a first-mover opportunity as green-building stock expands.
Central Vietnam expansion: Da Nang's regional HQ and hospitality growth is underserved relative to Hanoi and HCMC, offering route-density advantages for early movers.
Integrated FM for state-owned enterprises: Cost-optimization outsourcing in SOEs is nascent; providers with transparent KPI reporting and change-management capability can capture first-generation bundled contracts.
Vietnam Facility Management Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Vietnam Facility Management Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.92% from 2020-2034
Segmentation
By Service Type
Hard Services
Asset Management
MEP Maintenance
HVAC
Electrical
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Grade-A office and mixed-use real estate expansion (+1.8% CAGR impact)
3.1.2. Manufacturing and logistics growth via China+1 and FTAs (+1.5%)
3.1.3. Hyperscale data-center build-out (+1.2%)
3.1.4. Government smart-city and infrastructure PPP initiatives (+1.0%)
3.1.5. Cost-optimization outsourcing in state and private enterprises (+0.9%)
3.1.6. Green-building and energy-efficiency certification demand (+0.6%)
3.2. Market Trends
3.2.1. Shift from single-service contracts to bundled and integrated FM models
3.2.2. IoT monitoring and AI energy optimization moving from pilot to early scale
3.2.3. Green-building certification (LOTUS, EDGE) linked to contract payment milestones
3.2.4. Outsourced FM penetration rising from 74% to 80% by 2031
3.2.5. Hyperscale data-center build-out driving critical-environment FM demand
3.3. Market Restrains
3.3.1. Skilled technician shortages in industrial corridors
3.3.2. High upfront integration costs for digital FM platforms
3.3.3. Cybersecurity risks in connected buildings
Plumbing
Soft Services
Cleaning
Security
Office Support
Landscaping
Catering
By Offering Type
In-House
Outsourced
Single FM
Bundled FM
Integrated FM
By End-User Industry
Commercial
Hospitality
Institutional and Public Infrastructure
Industrial and Process
Healthcare
Others
By Geography
Northern Vietnam
Hanoi
Bac Ninh
Hai Phong
Central Vietnam
Da Nang
Hue
Southern Vietnam
Ho Chi Minh City
Binh Duong
Dong Nai
3.3.4. Fragmented competitive structure with 4,280+ players
3.3.5. Regulatory complexity in PPP and green-building compliance
3.4. Market Restraints
3.4.1. Skilled technician shortages in industrial corridors
3.4.2. High upfront integration costs for digital FM platforms
3.4.3. Cybersecurity risks in connected buildings
3.4.4. Fragmented competitive structure with 4,280+ players
3.4.5. Regulatory complexity in PPP and green-building compliance
3.5. Market Challenges
3.5.1. Labor cost inflation and technician retention
3.5.2. Capital mobilization for complex multi-site contracts
3.5.3. Standardizing service quality across fragmented subcontractor networks
3.5.4. Meeting 99.99% uptime requirements in data-center FM
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Hard Services
5.1.1.1. Asset Management
5.1.1.2. MEP Maintenance
5.1.1.3. HVAC
5.1.1.4. Electrical
5.1.1.5. Plumbing
5.1.2. Soft Services
5.1.2.1. Cleaning
5.1.2.2. Security
5.1.2.3. Office Support
5.1.2.4. Landscaping
5.1.2.5. Catering
5.2. Market Analysis, Insights and Forecast - by Offering Type
5.2.1. In-House
5.2.2. Outsourced
5.2.2.1. Single FM
5.2.2.2. Bundled FM
5.2.2.3. Integrated FM
5.3. Market Analysis, Insights and Forecast - by End-User Industry
5.3.1. Commercial
5.3.2. Hospitality
5.3.3. Institutional and Public Infrastructure
5.3.4. Industrial and Process
5.3.5. Healthcare
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Northern Vietnam
5.4.2. Central Vietnam
5.4.3. Southern Vietnam
6. Northern Vietnam Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Hard Services
6.1.1.1. Asset Management
6.1.1.2. MEP Maintenance
6.1.1.3. HVAC
6.1.1.4. Electrical
6.1.1.5. Plumbing
6.1.2. Soft Services
6.1.2.1. Cleaning
6.1.2.2. Security
6.1.2.3. Office Support
6.1.2.4. Landscaping
6.1.2.5. Catering
6.2. Market Analysis, Insights and Forecast - by Offering Type
6.2.1. In-House
6.2.2. Outsourced
6.2.2.1. Single FM
6.2.2.2. Bundled FM
6.2.2.3. Integrated FM
6.3. Market Analysis, Insights and Forecast - by End-User Industry
6.3.1. Commercial
6.3.2. Hospitality
6.3.3. Institutional and Public Infrastructure
6.3.4. Industrial and Process
6.3.5. Healthcare
6.3.6. Others
7. Central Vietnam Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Hard Services
7.1.1.1. Asset Management
7.1.1.2. MEP Maintenance
7.1.1.3. HVAC
7.1.1.4. Electrical
7.1.1.5. Plumbing
7.1.2. Soft Services
7.1.2.1. Cleaning
7.1.2.2. Security
7.1.2.3. Office Support
7.1.2.4. Landscaping
7.1.2.5. Catering
7.2. Market Analysis, Insights and Forecast - by Offering Type
7.2.1. In-House
7.2.2. Outsourced
7.2.2.1. Single FM
7.2.2.2. Bundled FM
7.2.2.3. Integrated FM
7.3. Market Analysis, Insights and Forecast - by End-User Industry
7.3.1. Commercial
7.3.2. Hospitality
7.3.3. Institutional and Public Infrastructure
7.3.4. Industrial and Process
7.3.5. Healthcare
7.3.6. Others
8. Southern Vietnam Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Hard Services
8.1.1.1. Asset Management
8.1.1.2. MEP Maintenance
8.1.1.3. HVAC
8.1.1.4. Electrical
8.1.1.5. Plumbing
8.1.2. Soft Services
8.1.2.1. Cleaning
8.1.2.2. Security
8.1.2.3. Office Support
8.1.2.4. Landscaping
8.1.2.5. Catering
8.2. Market Analysis, Insights and Forecast - by Offering Type
8.2.1. In-House
8.2.2. Outsourced
8.2.2.1. Single FM
8.2.2.2. Bundled FM
8.2.2.3. Integrated FM
8.3. Market Analysis, Insights and Forecast - by End-User Industry
8.3.1. Commercial
8.3.2. Hospitality
8.3.3. Institutional and Public Infrastructure
8.3.4. Industrial and Process
8.3.5. Healthcare
8.3.6. Others
9. Competitive Analysis
9.1. Company Profiles
9.1.1. ISS A/S
9.1.1.1. Company Overview
9.1.1.2. Products
9.1.1.3. Company Financials
9.1.1.4. SWOT Analysis
9.1.2. Sodexo
9.1.2.1. Company Overview
9.1.2.2. Products
9.1.2.3. Company Financials
9.1.2.4. SWOT Analysis
9.1.3. CBRE Group
9.1.3.1. Company Overview
9.1.3.2. Products
9.1.3.3. Company Financials
9.1.3.4. SWOT Analysis
9.1.4. JLL
9.1.4.1. Company Overview
9.1.4.2. Products
9.1.4.3. Company Financials
9.1.4.4. SWOT Analysis
9.1.5. Cushman & Wakefield
9.1.5.1. Company Overview
9.1.5.2. Products
9.1.5.3. Company Financials
9.1.5.4. SWOT Analysis
9.1.6. Compass Group
9.1.6.1. Company Overview
9.1.6.2. Products
9.1.6.3. Company Financials
9.1.6.4. SWOT Analysis
9.1.7. Aramark
9.1.7.1. Company Overview
9.1.7.2. Products
9.1.7.3. Company Financials
9.1.7.4. SWOT Analysis
9.1.8. Veolia
9.1.8.1. Company Overview
9.1.8.2. Products
9.1.8.3. Company Financials
9.1.8.4. SWOT Analysis
9.1.9. ENGIE
9.1.9.1. Company Overview
9.1.9.2. Products
9.1.9.3. Company Financials
9.1.9.4. SWOT Analysis
9.1.10. Johnson Controls
9.1.10.1. Company Overview
9.1.10.2. Products
9.1.10.3. Company Financials
9.1.10.4. SWOT Analysis
9.2. Market Entropy
9.2.1. Company's Key Areas Served
9.2.2. Recent Developments
9.3. Company Market Share Analysis, 2026
9.3.1. Top 5 Companies Market Share Analysis
9.3.2. Top 3 Companies Market Share Analysis
9.4. List of Potential Customers
List of Figures
Figure 1: Global Vietnam Facility Management Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Northern Vietnam Vietnam Facility Management Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 3: Northern Vietnam Vietnam Facility Management Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 4: Northern Vietnam Vietnam Facility Management Industry Revenue (Billion), by Offering Type 2026 & 2034
Figure 5: Northern Vietnam Vietnam Facility Management Industry Revenue Share (%), by Offering Type 2026 & 2034
Figure 6: Northern Vietnam Vietnam Facility Management Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 7: Northern Vietnam Vietnam Facility Management Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 8: Northern Vietnam Vietnam Facility Management Industry Revenue (Billion), by Country 2026 & 2034
Figure 9: Northern Vietnam Vietnam Facility Management Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Central Vietnam Vietnam Facility Management Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 11: Central Vietnam Vietnam Facility Management Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 12: Central Vietnam Vietnam Facility Management Industry Revenue (Billion), by Offering Type 2026 & 2034
Figure 13: Central Vietnam Vietnam Facility Management Industry Revenue Share (%), by Offering Type 2026 & 2034
Figure 14: Central Vietnam Vietnam Facility Management Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 15: Central Vietnam Vietnam Facility Management Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 16: Central Vietnam Vietnam Facility Management Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Central Vietnam Vietnam Facility Management Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Southern Vietnam Vietnam Facility Management Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 19: Southern Vietnam Vietnam Facility Management Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 20: Southern Vietnam Vietnam Facility Management Industry Revenue (Billion), by Offering Type 2026 & 2034
Figure 21: Southern Vietnam Vietnam Facility Management Industry Revenue Share (%), by Offering Type 2026 & 2034
Figure 22: Southern Vietnam Vietnam Facility Management Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 23: Southern Vietnam Vietnam Facility Management Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 24: Southern Vietnam Vietnam Facility Management Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Southern Vietnam Vietnam Facility Management Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Vietnam Facility Management Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Vietnam Facility Management Industry Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 3: Global Vietnam Facility Management Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 4: Global Vietnam Facility Management Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Northern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 6: Northern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 7: Northern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 8: Northern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Hanoi Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Bac Ninh Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Hai Phong Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Central Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 13: Central Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 14: Central Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 15: Central Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Da Nang Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Hue Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Southern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 19: Southern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 20: Southern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 21: Southern Vietnam Vietnam Facility Management Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Ho Chi Minh City Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Binh Duong Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Dong Nai Vietnam Facility Management Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the Vietnam facility management industry market?
Our proprietary research estimates the Vietnam facility management industry market at USD 8.59 billion in 2025, growing to USD 9.19 billion in 2026 and USD 12.84 billion by 2031, at a 6.92% CAGR.
2Which segment is the fastest-growing in the Vietnam FM market?
Soft services are the fastest-growing service type at 7.32% CAGR through 2031, while outsourced facility management is the fastest-growing delivery model at 7.46% CAGR, rising from 74% penetration in 2025 to 80% by 2031.
3What are the key drivers of the Vietnam facility management market?
Key drivers include Grade-A office and mixed-use real estate expansion (+1.8% CAGR impact), manufacturing and logistics growth via China+1 and FTAs (+1.5%), hyperscale data-center build-out (+1.2%), and government smart-city and PPP initiatives (+1.0%).
4Which region dominates the Vietnam facility management market?
Southern Vietnam, anchored by Ho Chi Minh City and the Binh Duong–Dong Nai industrial corridor, accounts for approximately 45% of market revenue, followed by Northern Vietnam at ~38% and Central Vietnam at ~17%.
5How many providers operate in the Vietnam FM market?
The market is highly fragmented with more than 4,280 active providers, ranging from international integrated FM majors to domestic single-service specialists, resulting in low market concentration.
6What role does the EU-Vietnam Free Trade Agreement play in FM demand?
The EU-Vietnam FTA, in force since 1 August 2020, eliminated 99% of tariffs and locks in export competitiveness for manufacturing, driving factory and logistics construction that generates recurring hard-services demand with uptime requirements above 98%.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, including structured interviews, CATI surveys, and on-site facility audits across Vietnam's industrial corridors, Grade-A office towers, and PPP projects.
We interview 4–5 specific company types across the FM value chain: integrated facility service providers, single-service subcontractors (cleaning, security, MEP), industrial park and real estate developers, technology vendors (BMS/IoT/CMMS), and public infrastructure concessionaires.
Stakeholder job titles interviewed include Chief Operating Officer (FM providers), Head of Property Management (developers), Procurement Director (industrial tenants), and Facility/Engineering Manager (Grade-A offices).
Primary interviews are supplemented by on-site asset audits measuring managed floor area, contract duration, SLA structures, and technology adoption levels.
20–30% of research effort draws on secondary benchmarking from official multilateral and governmental sources, including the World Bank WITS, EU Access2Markets, UN Comtrade, and Vietnam's General Statistics Office.
We triangulate with recognized non-profit technical standards and industry associations, including the International Facility Management Association (IFMA), Royal Institution of Chartered Surveyors (RICS), Vietnam Green Building Council (VGBC), and International Energy Agency (IEA) building-efficiency benchmarks.
Financial databases used for company-level validation include Bloomberg, Factiva, Hoovers, and PitchBook, alongside official .gov and .org disclosures.
Demand Modeling & Market Estimation
We deploy top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation. The bottom-up model aggregates provider revenues by segment and region; the top-down model applies FM penetration rates to the professionally managed floor-area base.
Specific quantitative metrics used in the bottom-up calculation include: (1) managed floor area (205.0 million m² in 2025); (2) average service revenue per managed square metre; (3) outsourced FM penetration rate (74% in 2025, rising to 80% by 2031); and (4) integrated contract share of revenue (24% in 2025, rising to 30% by 2031).
Segment-level CAGRs are modeled using driver impact coefficients (+1.8% for Grade-A stock, +1.5% for manufacturing FDI, +1.2% for data centers, +1.0% for PPPs, +0.9% for SOE outsourcing, +0.6% for green certification).
Data Accuracy & Quality Check
Every report is updated to the date of purchase, incorporating the latest available FDI disbursement, construction completion, and contract-award data.
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-level triangulation, cross-validation of primary interview responses against secondary benchmarks, and outlier screening.
Final estimates are reviewed by our Senior Analyst Panel and calibrated against historical performance (6.19% CAGR during 2020–2025) to ensure forecast coherence.
Related Reports
Property And Casualty Reinsurance Market valued at USD 398.3 Billion in 2024, projected to reach USD 1,245.46 Billion by 2035 at a 10.92% CAGR.
Nov 2026|245 pages
$2900.00
IP valuation market valued at $14.16 Billion in 2026, reaching $30.75 Billion by 2034 at a 10.18% CAGR, driven by M&A and IP-backed finance.
Nov 2026|216 pages
$2900.00
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.
Nov 2026|241 pages
$2900.00
India construction equipment market at $9.98B in 2027 to reach $14.46B by 2032, CAGR 7.70%. Earthmoving leads; electric/hybrid fastest-growing.