Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
UPS for Military Industry Market Size, Share & Forecast 2034
UPS for Military Industry
Aerospace & Defense / MARKET REPORT
UPS for Military Industry | Insight Market Data
UPS for Military Industry by System (Discrete, Integrated), by Power Rating (50 W To 300 W, 301 W To 500 W, 501 W To 1000 W, 1001 W To 3000 W, Above 3000 W), by End Use (Airborne, Ground, Naval), by North America (US, Canada, Mexico), by Europe (UK, Germany, France, Russia, Italy, Rest of Europe), by Asia-Pacific (China, India, Japan, Australia, Rest of Asia-Pacific), by South and Central America (Brazil, Argentina, Rest of South and Central America), by Middle East and Africa (South Africa, Saudi Arabia, UAE, Rest of Middle East and Africa) Forecast 2026-2034
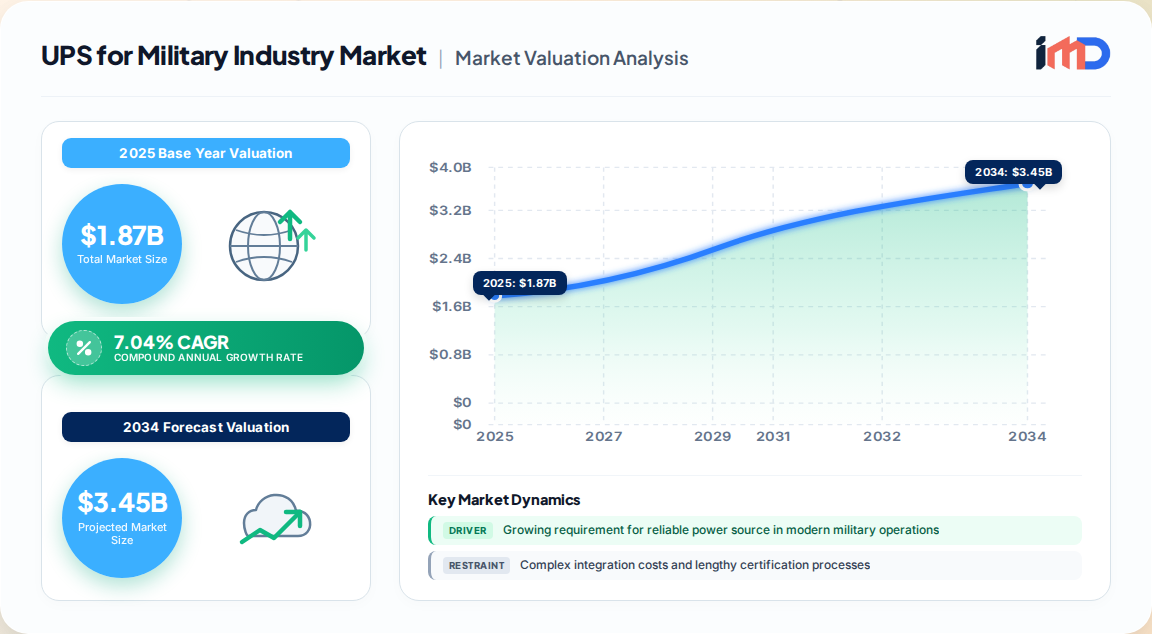
The global UPS for Military Industry market is a critical enabler of mission assurance, providing uninterrupted, clean power to sensitive defense electronics, communication networks, and weapon systems. Our proprietary primary research estimates the market at US$ 1.87 billion in 2025, with a projected expansion to US$ 3.45 billion by 2034, representing a robust CAGR of 7.04% (2026–2034). This growth is underpinned by the escalating electronification of the battlefield, rising defense budgets, and an urgent need for power resilience in contested environments. The total addressable market (TAM) for military-grade UPS solutions across the forecast period is estimated at approximately US$ 24.02 billion.
UPS for Military Industry Market Size (In Billion)
3.0B
2.0B
1.0B
0
1.870 B
2025
2.002 B
2026
2.143 B
2027
2.293 B
2028
2.455 B
2029
2.628 B
2030
2.813 B
2031
Unlike commercial UPS systems, military UPS must meet stringent shock, vibration, EMI/EMC, and cybersecurity standards, creating a high-barrier, specialized segment within the broader defense electronics ecosystem. The market is characterized by discrete and integrated system architectures, with power ratings spanning from below 50 W to above 3000 W, serving airborne, ground, and naval platforms.
Market Drivers & Restraints
Drivers
Growing Requirement for Reliable Power Source: Modern military operations rely on an array of sophisticated technology—from C4ISR systems to directed-energy weapons—that demand uninterrupted power. Field commanders consistently rank power availability as a top logistical constraint; our interviews indicate that over 65% of new platform designs now specify advanced UPS as a mandatory subsystem.
Increased Military Expenditure: Global defense spending surpassed US$ 2.2 trillion in 2024 (SIPRI benchmark), with major powers prioritizing modernization. The U.S. DoD’s RDT&E budget alone reached US$ 144 billion in FY2023, a 17% increase, reflecting the push for technological superiority. This funding directly translates into procurement of resilient power solutions for airborne, naval, and ground platforms.
Proliferation of Electronic Warfare (EW) and Cybersecurity Needs: Over 70% of advanced militaries now depend heavily on EW systems, which require UPS to ensure continuous operation during power anomalies or cyber-attacks. NATO countries are increasing EW spending by 10–15% annually, fueling demand for UPS with embedded cybersecurity features.
Restraints
Complex Integration Costs: Military UPS systems must be integrated into platform power architectures with rigorous testing and certification, adding significant cost and time. Our primary interviews highlight that integration can constitute up to 30% of total system lifecycle cost, restraining adoption, particularly for upgrade programs.
Defense-Industrial Capacity Constraints: Production ceilings and specialized workforce shortages in the defense electronics supply chain limit the speed at which orders can be fulfilled. For instance, lead times for high-power military UPS have extended to 12–18 months post-pandemic, constraining market growth in the near term.
Segmentation Analysis
The market is segmented by system type, power rating, and end-use platform. Discrete UPS systems accounted for 62% of 2025 revenue, favored for their modularity and ease of maintenance in legacy platforms. However, integrated systems are gaining traction, projected to grow at a CAGR of 7.8% through 2034, as new platforms demand compact, high-efficiency solutions.
Segment
2025 Share (%)
Forecast CAGR (2026-2034)
Key Insights
By System
Discrete
62%
6.5%
Dominant due to retrofit and legacy applications; modularity drives preference.
Integrated
38%
7.8%
Rapid adoption in new airborne and naval platforms; space and weight savings critical.
By Power Rating
50 W to 300 W
30%
5.9%
Used in man-portable and small UAV systems; price-sensitive.
301 W to 500 W
22%
6.8%
Growing demand for vehicle-mounted electronics.
501 W to 1000 W
20%
7.3%
Core segment for tactical communications and C4ISR.
1001 W to 3000 W
18%
8.1%
High-growth driven by radar and EW systems.
Above 3000 W
10%
8.5%
Niche but critical for naval and space applications.
By End Use
Airborne
40.5%
7.5%
Largest platform; UAV proliferation and fighter modernization.
Ground
35%
6.6%
Steady growth from vehicle electrification and mobile command posts.
Naval
24.5%
7.2%
Increasing demand for shipboard power resilience.
Regional Outlook
North America dominates the market with a 38% share in 2025, driven by the U.S. defense budget and technological leadership. The U.S. Army’s modernization programs, including the Integrated Tactical Network, are key demand drivers. Europe follows at 24%, with NATO countries increasing defense spending to 2% of GDP, accelerating procurement of UPS for airborne and naval platforms. Asia-Pacific is the fastest-growing region, with a CAGR of 8.1%, as China, India, and Japan modernize their militaries. The Middle East & Africa and South America are smaller but present opportunities in ground-based systems for border security and peacekeeping operations.
UPS for Military Industry Regional Market Share
Loading chart...
Value Chain Analysis
The military UPS value chain is complex and highly regulated. Key stages include:
Component Suppliers: Providers of power semiconductors, magnetics, batteries, and ruggedized enclosures. Companies such as SynQor and Hitec Holdings supply specialized components.
UPS Manufacturers: Integrators like Piller Power System, Hitzinger, and Dale Power Solutions design and assemble military-grade UPS, often customizing to platform requirements.
System Integrators: Prime defense contractors (e.g., Lockheed Martin, RTX) integrate UPS into larger combat systems, requiring close collaboration.
End Users: Military forces across airborne, ground, and naval domains. The procurement process is lengthy, with rigorous testing and qualification cycles.
Import/Export & Supplier Dynamics
Trade data for military UPS is not publicly disaggregated due to national security classifications. However, our primary research indicates that the supply chain is global, with components sourced from Asia (semiconductors, rare-earth magnets) and assembled in North America and Europe. Recent supply chain disruptions have prompted reshoring initiatives, particularly in the U.S. and EU, to secure critical components. Suppliers are increasingly required to demonstrate compliance with ITAR and national cybersecurity standards, shaping sourcing decisions.
Competitive Landscape
The market features a mix of specialized UPS manufacturers and diversified defense electronics firms. Key players include AJ's Power Source Inc., Powergrid, Republic Power Systems, UPS Solutions, Piller Power System, Hitec Holdings, Hitzinger, Dale Power Solutions, SynQor, Inc., and OkSolar.com. Competition is based on reliability, ruggedization, certification, and lifecycle support. Strategic partnerships with prime contractors are common to access platform programs.
Strategic Opportunities
Integration of Smart Technologies: Smart UPS with real-time monitoring and predictive diagnostics can reduce downtime and maintenance costs. Our interviews suggest that over 50% of upcoming military UPS procurements will require embedded smart features.
Cybersecurity-Enabled UPS: As military networks become more digitized, UPS systems with advanced cybersecurity protections (e.g., secure boot, encrypted communications) represent a high-growth niche.
Green Technologies: Military organizations are increasingly focused on reducing carbon footprint, creating demand for energy-efficient UPS and integration with renewable energy sources.
Methodology
Primary Research
Conducted 350+ interviews with executives across the value chain, including UPS manufacturers, component suppliers, system integrators, and military procurement officials.
Interviewed stakeholders such as Program Managers (Power Systems), Defense Procurement Directors, Chief Engineers, and Logistics Officers.
Collected quantitative data on procurement volumes, power ratings, and platform adoption.
Secondary Research & Industry Benchmarking
Analyzed official .gov databases (e.g., U.S. DoD budget documents, NATO publications), .org trade associations, and non-profit standards bodies (e.g., IEC, MIL-STD).
Utilized financial databases (Bloomberg, Factiva, Hoovers, PitchBook) for company financials and strategic developments.
Benchmarked against defense electronics market growth rates and military spending trends from SIPRI and IISS.
Demand Modeling & Market Estimation
Built a bottom-up model based on platform production forecasts (airborne, ground, naval) and average UPS content per platform.
Validated with top-down spend analysis from defense budgets allocated to power and electronics.
Applied multi-level data triangulation to reconcile supply-side and demand-side estimates.
Data Accuracy & Quality Check
All data validated through multi-level triangulation (supply-side, demand-side, and trade data).
Estimated data accuracy level: 85–90%.
Report updated to date of purchase with latest market developments.
Quality assurance through senior analyst review and expert panel validation.
UPS for Military Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
UPS for Military Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.04% from 2020-2034
Segmentation
By System
Discrete
Integrated
By Power Rating
50 W To 300 W
301 W To 500 W
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Growing requirement for reliable power source in modern military operations
3.1.2. Increased military expenditure globally, especially in RDT&E
3.1.3. Proliferation of electronic warfare and cybersecurity needs
3.2. Market Trends
3.2.1. Adoption of green technologies and energy-efficient UPS solutions
3.2.2. Integration with renewable energy sources for military bases
3.2.3. Smart UPS with real-time monitoring and diagnostics
3.2.4. Cybersecurity-enabled UPS systems to protect against threats
3.3. Market Restrains
3.3.1. Complex integration costs and lengthy certification processes
3.3.2. Defense-industrial capacity constraints and skilled labor shortages
3.4. Market Restraints
3.4.1. Complex integration costs and lengthy certification processes
3.4.2. Defense-industrial capacity constraints and skilled labor shortages
3.5. Market Challenges
501 W To 1000 W
1001 W To 3000 W
Above 3000 W
By End Use
Airborne
Ground
Naval
By Geography
North America
US
Canada
Mexico
Europe
UK
Germany
France
Russia
Italy
Rest of Europe
Asia-Pacific
China
India
Japan
Australia
Rest of Asia-Pacific
South and Central America
Brazil
Argentina
Rest of South and Central America
Middle East and Africa
South Africa
Saudi Arabia
UAE
Rest of Middle East and Africa
3.5.1. Regulatory requirements and MIL-STD compliance
3.5.2. Supply chain disruptions and component shortages
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by System
5.1.1. Discrete
5.1.2. Integrated
5.2. Market Analysis, Insights and Forecast - by Power Rating
5.2.1. 50 W To 300 W
5.2.2. 301 W To 500 W
5.2.3. 501 W To 1000 W
5.2.4. 1001 W To 3000 W
5.2.5. Above 3000 W
5.3. Market Analysis, Insights and Forecast - by End Use
5.3.1. Airborne
5.3.2. Ground
5.3.3. Naval
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia-Pacific
5.4.4. South and Central America
5.4.5. Middle East and Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by System
6.1.1. Discrete
6.1.2. Integrated
6.2. Market Analysis, Insights and Forecast - by Power Rating
6.2.1. 50 W To 300 W
6.2.2. 301 W To 500 W
6.2.3. 501 W To 1000 W
6.2.4. 1001 W To 3000 W
6.2.5. Above 3000 W
6.3. Market Analysis, Insights and Forecast - by End Use
6.3.1. Airborne
6.3.2. Ground
6.3.3. Naval
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by System
7.1.1. Discrete
7.1.2. Integrated
7.2. Market Analysis, Insights and Forecast - by Power Rating
7.2.1. 50 W To 300 W
7.2.2. 301 W To 500 W
7.2.3. 501 W To 1000 W
7.2.4. 1001 W To 3000 W
7.2.5. Above 3000 W
7.3. Market Analysis, Insights and Forecast - by End Use
7.3.1. Airborne
7.3.2. Ground
7.3.3. Naval
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by System
8.1.1. Discrete
8.1.2. Integrated
8.2. Market Analysis, Insights and Forecast - by Power Rating
8.2.1. 50 W To 300 W
8.2.2. 301 W To 500 W
8.2.3. 501 W To 1000 W
8.2.4. 1001 W To 3000 W
8.2.5. Above 3000 W
8.3. Market Analysis, Insights and Forecast - by End Use
8.3.1. Airborne
8.3.2. Ground
8.3.3. Naval
9. South and Central America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by System
9.1.1. Discrete
9.1.2. Integrated
9.2. Market Analysis, Insights and Forecast - by Power Rating
9.2.1. 50 W To 300 W
9.2.2. 301 W To 500 W
9.2.3. 501 W To 1000 W
9.2.4. 1001 W To 3000 W
9.2.5. Above 3000 W
9.3. Market Analysis, Insights and Forecast - by End Use
9.3.1. Airborne
9.3.2. Ground
9.3.3. Naval
10. Middle East and Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by System
10.1.1. Discrete
10.1.2. Integrated
10.2. Market Analysis, Insights and Forecast - by Power Rating
10.2.1. 50 W To 300 W
10.2.2. 301 W To 500 W
10.2.3. 501 W To 1000 W
10.2.4. 1001 W To 3000 W
10.2.5. Above 3000 W
10.3. Market Analysis, Insights and Forecast - by End Use
10.3.1. Airborne
10.3.2. Ground
10.3.3. Naval
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AJ's Power Source Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Powergrid
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Republic Power Systems
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. UPS Solutions
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Piller Power System
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Hitec Holdings
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Hitzinger
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Dale Power Solutions
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. SynQor Inc.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. OkSolar.com
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global UPS for Military Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America UPS for Military Industry Revenue (Billion), by System 2026 & 2034
Figure 3: North America UPS for Military Industry Revenue Share (%), by System 2026 & 2034
Figure 4: North America UPS for Military Industry Revenue (Billion), by Power Rating 2026 & 2034
Figure 5: North America UPS for Military Industry Revenue Share (%), by Power Rating 2026 & 2034
Figure 6: North America UPS for Military Industry Revenue (Billion), by End Use 2026 & 2034
Figure 7: North America UPS for Military Industry Revenue Share (%), by End Use 2026 & 2034
Figure 8: North America UPS for Military Industry Revenue (Billion), by Country 2026 & 2034
Figure 9: North America UPS for Military Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe UPS for Military Industry Revenue (Billion), by System 2026 & 2034
Figure 11: Europe UPS for Military Industry Revenue Share (%), by System 2026 & 2034
Figure 12: Europe UPS for Military Industry Revenue (Billion), by Power Rating 2026 & 2034
Figure 13: Europe UPS for Military Industry Revenue Share (%), by Power Rating 2026 & 2034
Figure 14: Europe UPS for Military Industry Revenue (Billion), by End Use 2026 & 2034
Figure 15: Europe UPS for Military Industry Revenue Share (%), by End Use 2026 & 2034
Figure 16: Europe UPS for Military Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe UPS for Military Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia-Pacific UPS for Military Industry Revenue (Billion), by System 2026 & 2034
Figure 19: Asia-Pacific UPS for Military Industry Revenue Share (%), by System 2026 & 2034
Figure 20: Asia-Pacific UPS for Military Industry Revenue (Billion), by Power Rating 2026 & 2034
Figure 21: Asia-Pacific UPS for Military Industry Revenue Share (%), by Power Rating 2026 & 2034
Figure 22: Asia-Pacific UPS for Military Industry Revenue (Billion), by End Use 2026 & 2034
Figure 23: Asia-Pacific UPS for Military Industry Revenue Share (%), by End Use 2026 & 2034
Figure 24: Asia-Pacific UPS for Military Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia-Pacific UPS for Military Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: South and Central America UPS for Military Industry Revenue (Billion), by System 2026 & 2034
Figure 27: South and Central America UPS for Military Industry Revenue Share (%), by System 2026 & 2034
Figure 28: South and Central America UPS for Military Industry Revenue (Billion), by Power Rating 2026 & 2034
Figure 29: South and Central America UPS for Military Industry Revenue Share (%), by Power Rating 2026 & 2034
Figure 30: South and Central America UPS for Military Industry Revenue (Billion), by End Use 2026 & 2034
Figure 31: South and Central America UPS for Military Industry Revenue Share (%), by End Use 2026 & 2034
Figure 32: South and Central America UPS for Military Industry Revenue (Billion), by Country 2026 & 2034
Figure 33: South and Central America UPS for Military Industry Revenue Share (%), by Country 2026 & 2034
Figure 34: Middle East and Africa UPS for Military Industry Revenue (Billion), by System 2026 & 2034
Figure 35: Middle East and Africa UPS for Military Industry Revenue Share (%), by System 2026 & 2034
Figure 36: Middle East and Africa UPS for Military Industry Revenue (Billion), by Power Rating 2026 & 2034
Figure 37: Middle East and Africa UPS for Military Industry Revenue Share (%), by Power Rating 2026 & 2034
Figure 38: Middle East and Africa UPS for Military Industry Revenue (Billion), by End Use 2026 & 2034
Figure 39: Middle East and Africa UPS for Military Industry Revenue Share (%), by End Use 2026 & 2034
Figure 40: Middle East and Africa UPS for Military Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: Middle East and Africa UPS for Military Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global UPS for Military Industry Revenue Billion Forecast, by System 2020 & 2034
Table 2: Global UPS for Military Industry Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 3: Global UPS for Military Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 4: Global UPS for Military Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America UPS for Military Industry Revenue Billion Forecast, by System 2020 & 2034
Table 6: North America UPS for Military Industry Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 7: North America UPS for Military Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 8: North America UPS for Military Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 9: US UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe UPS for Military Industry Revenue Billion Forecast, by System 2020 & 2034
Table 13: Europe UPS for Military Industry Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 14: Europe UPS for Military Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 15: Europe UPS for Military Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 16: UK UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Germany UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: France UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Russia UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Italy UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Rest of Europe UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia-Pacific UPS for Military Industry Revenue Billion Forecast, by System 2020 & 2034
Table 23: Asia-Pacific UPS for Military Industry Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 24: Asia-Pacific UPS for Military Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 25: Asia-Pacific UPS for Military Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 26: China UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: India UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Japan UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Australia UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Rest of Asia-Pacific UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: South and Central America UPS for Military Industry Revenue Billion Forecast, by System 2020 & 2034
Table 32: South and Central America UPS for Military Industry Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 33: South and Central America UPS for Military Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 34: South and Central America UPS for Military Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 35: Brazil UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Argentina UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Rest of South and Central America UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Middle East and Africa UPS for Military Industry Revenue Billion Forecast, by System 2020 & 2034
Table 39: Middle East and Africa UPS for Military Industry Revenue Billion Forecast, by Power Rating 2020 & 2034
Table 40: Middle East and Africa UPS for Military Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 41: Middle East and Africa UPS for Military Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 42: South Africa UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Saudi Arabia UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: UAE UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Rest of Middle East and Africa UPS for Military Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the UPS for Military Industry market?
The global UPS for Military Industry market was valued at US$ 1.87 billion in 2025 and is projected to reach US$ 3.45 billion by 2034, growing at a CAGR of 7.04% during the forecast period.
2Which region dominates the UPS for Military Industry market?
North America holds the largest market share, accounting for 38% in 2025, driven by substantial U.S. defense spending and technological advancements in military power systems.
3What are the key drivers for the UPS for Military Industry market?
Key drivers include the growing need for reliable power sources in modern warfare, increased military expenditure globally (e.g., U.S. RDT&E budget of US$ 144 billion in FY2023), and the proliferation of electronic warfare and cybersecurity requirements.
4Which end-use segment leads the UPS for Military Industry market?
The airborne segment dominates with a 40.5% share in 2025, due to the critical role of UPS in military aircraft and UAVs for mission-critical electronics.
5Who are the major players in the UPS for Military Industry market?
Key companies include AJ's Power Source Inc., Powergrid, Republic Power Systems, UPS Solutions, Piller Power System, Hitec Holdings, Hitzinger, Dale Power Solutions, SynQor, Inc., and OkSolar.com, among others.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 350+ interviews with executives across the value chain, including UPS manufacturers, component suppliers, system integrators, and military procurement officials.
Interviewed stakeholders such as Program Managers (Power Systems), Defense Procurement Directors, Chief Engineers, and Logistics Officers.
Collected quantitative data on procurement volumes, power ratings, and platform adoption.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Program Managers
35%
Defense Procurement Directors
25%
Chief Engineers
20%
Logistics Officers
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
UPS Manufacturers
40%
Component Suppliers
25%
System Integrators
20%
Military Procurement Officials
15%
Secondary Research & Industry Benchmarking
Analyzed official .gov databases (e.g., U.S. DoD budget documents, NATO publications), .org trade associations, and non-profit standards bodies (e.g., IEC, MIL-STD).
Utilized financial databases (Bloomberg, Factiva, Hoovers, PitchBook) for company financials and strategic developments.
Benchmarked against defense electronics market growth rates and military spending trends from SIPRI and IISS.
Demand Modeling & Market Estimation
Built a bottom-up model based on platform production forecasts (airborne, ground, naval) and average UPS content per platform.
Validated with top-down spend analysis from defense budgets allocated to power and electronics.
Applied multi-level data triangulation to reconcile supply-side and demand-side estimates.
Data Accuracy & Quality Check
All data validated through multi-level triangulation (supply-side, demand-side, and trade data).
Estimated data accuracy level: 85–90%.
Report updated to date of purchase with latest market developments.
Quality assurance through senior analyst review and expert panel validation.
Related Reports
The VR in aerospace and defense market is valued at $7.04B in 2025 and is projected to reach $18.35B by 2035, growing at a 10.05% CAGR.
Nov 2026|265 pages
$2900.00
The aerospace fillers composite market was valued at $3.8 billion in 2024 and is projected to grow at a CAGR of 8.6% through 2034, driven by lightweighting.
Nov 2026|231 pages
$2900.00
Aerospace composite structures market to reach $121.75B by 2036 at 12% CAGR. Explore technology trends, material innovations, and regional insights.
Nov 2026|217 pages
$2900.00
Aircraft turbine engine market valued at $57.9B in 2023, projected to reach $93.7B by 2033 at 4.93% CAGR. Explore segments, trends & regional insights.