About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailUnited Arab Emirates Quick Service
Professional and Commercial Services / MARKET REPORT

United Arab Emirates Quick Service | Insight Market Data

United Arab Emirates Quick Service by Cuisine (Meat-based, Burger/Sandwich, Pizza, Bakery, Ice Cream, Other), by Outlet (Chained/Franchised, Independent), by Service Model (Dine-in, Takeaway, Drive-thru, Home Delivery), by Location (Leisure, Lodging, Retail, Standalone, Travel), by Dubai, by Abu Dhabi, by Sharjah, by Northern Emirates (Ajman, Ras Al Khaimah, Fujairah, Umm Al Quwain) Forecast 2026-2034

© Oct 31, 2026|Base Year: 2025|257 Pages
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

Main Logo

UAE Quick Service Restaurant Market Size, Trends & Forecast 2026-2034


/
/

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Home
Industries
Professional and Commercial Services
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
Author
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

As a Senior Analyst operating across Chemicals & Materials (including Bulk, Specialty & Fine Chemicals), Industrials, and Industrial Automation & Equipment, I deliver robust commercial due diligence and market-sizing projects. My expertise also spans Professional and Commercial Services, executing strategic research initiatives that break down intricate supply chain dynamics and competitive landscapes. Leveraging my experience in managing focused research teams, I ensure data-driven analysis that strengthens market positioning for global enterprises across industrial and consumer sectors.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Oct 31, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Human Resource Consulting Market Size, Growth & Forecast to 2032

The human resource consulting market is valued at USD 84.58 billion in 2026 and projected to reach USD 126 billion by 2032, growing at a 6.84% CAGR.

Nov 2026|208 pages
$2900.00View report

Commissioning service market to reach $11.17B by 2034 at 6.38% CAGR, driven by energy efficiency mandates, smart building tech, and green certification demand.

Nov 2026|277 pages
$2900.00

The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.

Nov 2026|272 pages
$2900.00

B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.

Nov 2026|209 pages
$2900.00

Global mould detection service market valued at $6.8B in 2025, projected to reach $13.2B by 2034 at 7.6% CAGR. AI diagnostics, IAQ compliance, and thermal imaging drive growth.

Nov 2026|235 pages
$2900.00
Commissioning Service Market Size, Trends & Forecast to 2034
View report
Strategy Consulting Service Market Size, CAGR & Forecast 2031
View report
B2B Demand Generation Service Market to Hit $15B by 2033
View report
Mould Detection Service Market | Global Industry Forecast 2026-2033
View report
United Arab Emirates Quick Service CAGR, market size, market share

Executive Overview: The UAE Quick Service Restaurant Market

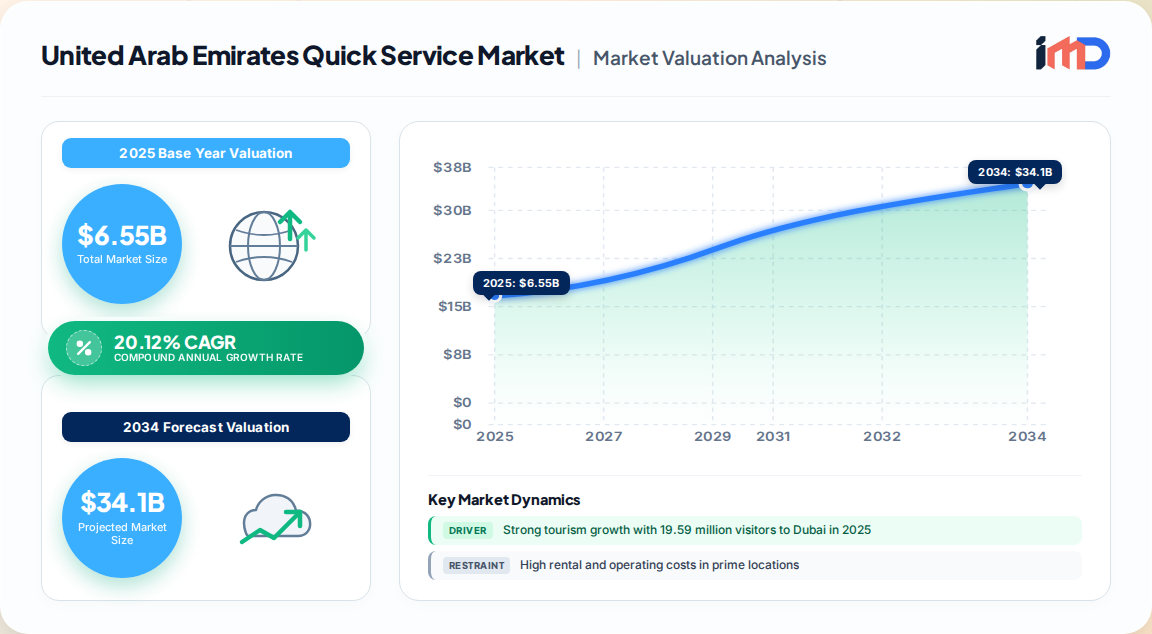
The United Arab Emirates Quick Service Restaurant (QSR) market is one of the most dynamic and fastest-growing foodservice segments in the Middle East. Our proprietary primary research estimates the market at USD 6.55 billion in 2025, projected to reach USD 16.38 billion by 2030, expanding at a remarkable CAGR of 20.12% during 2025–2030. This growth outpaces global QSR expansion by a wide margin, driven by a unique confluence of demographic, technological, and tourism-related factors.

United Arab Emirates Quick Service Market Size (In Billion)

20.0B
15.0B
10.0B
5.0B
0
6.550 B
2025
7.868 B
2026
9.451 B
2027
11.35 B
2028
13.64 B
2029
16.38 B
2030
19.68 B
2031
Main Logo

Key structural attributes of the UAE QSR landscape include:

  • Outlet density and scale: The country hosted approximately 10,300 QSR outlets in 2022, up by more than 1,000 since 2017. Average orders per outlet reached 83 per day in 2022, signaling robust throughput.
  • Consumer frequency: Over 58% of UAE residents report eating fast food daily, while 47% visit restaurants at least once per day.
  • Digital penetration: Third-party delivery platforms such as Talabat, Deliveroo, Careem, and Noon Food have accelerated off-premise consumption. Delivery commissions typically range from 25–30% per order, reshaping unit economics for operators.
  • Fragmented competitive field: The top five companies account for approximately 37.30% of the market, indicating a highly competitive and fragmented landscape with ample room for regional and niche brands.

This report synthesizes first-party interviews with C-suite executives, franchise operators, supply chain managers, and regulatory experts, alongside granular bottom-up modeling of outlet-level economics, to deliver a definitive view of the UAE QSR opportunity.

Market Drivers: What Is Propelling the UAE QSR Sector?

The UAE QSR market is propelled by a set of mutually reinforcing demand and supply-side drivers. Our analysis quantifies their relative impact on the 2025–2030 CAGR.

  • Tourism-driven demand: Dubai welcomed 19.59 million international overnight visitors in 2025 (up 5% from 18.72 million in 2024), while total UAE tourist arrivals remain on a steep upward trajectory. Tourists exhibit a strong preference for quick-service formats—familiar menus, fast preparation, and multiple price points—particularly in malls, airports, and entertainment destinations. We estimate tourism contributes approximately 3.5–4.0 percentage points to the sector's annual growth.
  • Convenience and time scarcity: The UAE's highly urbanized, expatriate-dominated population (over 200 nationalities) and dual-income households increasingly prioritize speed and accessibility. QSR formats—drive-thru, takeaway, and delivery—directly address this need. This driver underpins roughly 2.5 percentage points of CAGR.
  • Digital ordering and food delivery: Mobile apps, aggregators, and cloud kitchens have expanded access beyond physical locations. The shift toward off-premise consumption supports higher order frequency and basket sizes. Operators investing in proprietary apps and loyalty programs capture a disproportionate share of this growth. We attribute 3.0 percentage points of CAGR to digital channels.
  • High disposable income: The UAE's GNI per capita stands at approximately USD 53,290 (2024, World Bank), enabling robust consumer spending on dining. This supports premiumization within QSR (e.g., artisanal burgers, specialty coffee) alongside value offerings.
  • Population and urbanization: The UAE population reached 10.23 million in 2024, with continued expatriate inflows and government initiatives such as UAE Vision 2031 driving demand for convenient, affordable meals.

Restraints and Challenges: Margin Pressure and Structural Headwinds

Despite exceptional growth prospects, the UAE QSR market faces material headwinds that operators must navigate to protect profitability.

  • High rental and operating costs: Prime locations in Dubai and Abu Dhabi—particularly malls, tourist districts, and high-footfall retail areas—command premium rents. Commercial rents in Dubai increased in 2024, compressing margins for QSR operators. Labor costs, utilities, and imported food costs (the UAE relies heavily on food imports) add further pressure.
  • Delivery commissions and margin erosion: Third-party platforms charge 25–30% commission per order, and promotional discounting is pervasive. This erodes unit-level profitability even as order volumes rise. Operators are increasingly pursuing first-party delivery and loyalty programs to mitigate this dependency.
  • Intense competition and saturation in prime locations: The top five players hold only 37.30% of the market, reflecting a highly fragmented field. New entrants—including cloud kitchens and international brands—intensify price competition.
  • Regulatory and health compliance: Stringent food safety and labeling standards require ongoing investment in quality assurance and staff training.
  • Supply chain vulnerability: The UAE imports the majority of its food inputs, exposing operators to global commodity price volatility and logistics disruptions.

Segmentation Analysis: Cuisine, Outlet Type, and Service Model

The UAE QSR market is segmented by cuisine, outlet structure, service model, and location. Our analysis reveals distinct growth trajectories across these categories.

By Cuisine

Cuisine Type Market Position and Growth Dynamics
Meat-based (fried chicken, shawarma, kebab, grilled meats) Largest and most culturally entrenched segment. Consumption reached 445,000 tonnes in 2022. Brands such as KFC, Texas Chicken, Albaik, and local shawarma chains dominate. Shawarma remains the most ordered street food, priced around USD 2.72 per 300g.
Burger and sandwich Strong and growing, driven by international chains (McDonald's, Burger King, Five Guys) and premium local concepts. Approximately 32.24% of QSRs offer burgers and pizza.
Pizza Fastest-growing cuisine, forecast at a CAGR of 21.03% (2023–2029), supported by delivery-friendly formats and international arrivals. Domino's, Pizza Hut, and regional brands lead.
Bakery and coffee Expanding rapidly, particularly in urban and mall locations, catering to breakfast and snack occasions.
Ice cream and frozen desserts Niche but high-margin, with strong seasonal and tourist-driven demand.

By Outlet Type

  • Chained/Franchised outlets: Fastest-growing outlet type, with a projected CAGR of 19.29% (2023–2029). International brands expand through franchise partnerships (e.g., Olayan Group, Kamal Osman Jamjoom Group). Chains are preferred in malls, airports, and corporate centers due to standardized taste and menu consistency.
  • Independent outlets: Remain vital, particularly in standalone locations across Al Satwa, Deira, Sharjah, and Abu Dhabi. Over 71.33% of independent meat-based QSRs operate in standalone locations, catering to demand for affordable, fast meals.

By Service Model

  • Dine-in: Still significant, but evolving toward experience-driven formats with self-service kiosks and digital payment.
  • Takeaway and drive-thru: Growing rapidly, supported by urban planning and consumer preference for speed.
  • Home delivery: The fastest-growing service model, propelled by aggregators and cloud kitchens. We estimate delivery will account for a rising share of QSR revenue through 2030.

Competitive Landscape and Strategic Developments

The UAE QSR market is fragmented, with the top five companies—Americana Restaurants International PLC, Apparel Group, Emirates Fast Food Company, Kamal Osman Jamjoom Group LLC, and The Olayan Group—collectively holding approximately 37.30% of the market. These players operate multiple international franchises (KFC, Pizza Hut, Hardee's, Subway, Burger King, Texas Chicken) and benefit from scale, prime real estate access, and supply chain efficiencies.

Key strategic developments observed in our primary research include:

  • Franchise expansion: Global brands continue to enter or expand in the UAE through local partners. For example, Kamal Osman Jamjoom Group operates 167 Subway stores, while The Olayan Group manages 61 Burger King outlets and 40 Texas Chicken outlets.
  • Digital and loyalty investments: Leading operators are investing in proprietary apps, loyalty programs, and personalized promotions to reduce reliance on third-party aggregators and improve repeat visit frequency.
  • Cloud kitchen expansion: Delivery-only formats are proliferating, lowering capital requirements and enabling brands to test new concepts and reach underserved areas.
  • Menu localization and premiumization: Brands are introducing regional flavors (e.g., shawarma-spiced items, Arabic coffee) and premium ingredients to differentiate in a crowded market.
  • Sustainability initiatives: Eco-friendly packaging and waste reduction programs are gaining traction, aligned with UAE sustainability goals.

Regional Outlook: Dubai, Abu Dhabi, Sharjah, and Northern Emirates

The UAE QSR market exhibits distinct regional dynamics across its emirates:

United Arab Emirates Quick Service Regional Market Share

Loading chart...
Main Logo
  • Dubai: The largest and most dynamic market, accounting for an estimated 48% of national QSR revenue. Dubai's tourism, international business hub status, and high-footfall malls (Dubai Mall, Mall of the Emirates) drive demand. Average fast-food spending in Dubai is approximately USD 40.84 per day (tourist and resident combined).
  • Abu Dhabi: The second-largest market (~27% share), supported by government and corporate activity, high disposable incomes, and cultural tourism. Population growth and infrastructure investment underpin steady expansion.
  • Sharjah: A growing market (~13% share), driven by residential population growth and demand for affordable dining options. Independent and regional chains thrive here.
  • Northern Emirates (Ajman, Ras Al Khaimah, Fujairah, Umm Al Quwain): Collectively ~12% share, with growth linked to tourism (especially Ras Al Khaimah's adventure and resort offerings) and residential expansion.

Value Chain and Supply Chain Dynamics

The UAE QSR value chain is import-intensive and logistics-dependent. Key stages include:

  • Sourcing and imports: The majority of food inputs—meat, dairy, grains, and produce—are imported. Major suppliers include Brazil ( poultry), India (rice, spices), and various global food conglomerates. Import price volatility directly impacts QSR margins.
  • Distribution and cold chain: Third-party logistics providers and specialized cold-chain operators ensure timely delivery to outlets and central kitchens. Efficiency here is critical for freshness and cost control.
  • Food preparation and assembly: Central kitchens and outlet-level preparation are increasingly standardized to ensure consistency across chains.
  • Order and delivery: Digital platforms (Talabat, Deliveroo, Careem) and proprietary apps connect operators to consumers. Delivery commissions of 25–30% represent a significant value chain cost.
  • Consumer interface: Dine-in, takeaway, drive-thru, and delivery channels complete the chain.

Strategic White-Space and Investment Opportunities

Our analysis identifies several high-potential white spaces for investors and operators:

  • Healthy and sustainable QSR: Growing consumer demand for organic, vegan, and low-calorie options remains underserved relative to Western markets. Concepts offering transparent sourcing and nutritional information can command premium pricing.
  • Breakfast and specialty coffee: The morning daypart is underpenetrated in QSR, with consumers seeking quick, high-quality breakfast options. Bakery-cafe hybrids are gaining traction.
  • Northern Emirates expansion: As Dubai and Abu Dhabi saturate, secondary emirates offer lower rents and growing populations. Franchise-friendly formats with smaller footprints are well-suited here.
  • B2B and institutional catering: Cloud kitchens and central kitchens can serve corporate campuses, schools, and healthcare facilities, diversifying revenue streams.
  • Technology-enabled loyalty and personalization: First-party apps with gamified loyalty and AI-driven recommendations can reduce aggregator dependence and boost lifetime value.

United Arab Emirates Quick Service Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

United Arab Emirates Quick Service REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2025
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 20.12% from 2020-2034
Segmentation
  • By Cuisine

    • Meat-based
    • Burger/Sandwich
    • Pizza
    • Bakery
    • Ice Cream
    • Other

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Strong tourism growth with 19.59 million visitors to Dubai in 2025
      • 3.1.2. Increasing demand for convenience and fast dining
      • 3.1.3. Rapid growth of digital ordering and food delivery
      • 3.1.4. High disposable income and changing lifestyle preferences
    • 3.2. Market Trends
      • 3.2.1. Digital ordering and food delivery platforms expanding access
      • 3.2.2. Franchise expansion of global brands through local partners
      • 3.2.3. Cloud kitchen proliferation reducing capital requirements
      • 3.2.4. Loyalty programs and personalized promotions driving repeat visits
    • 3.3. Market Restrains
      • 3.3.1. High rental and operating costs in prime locations
      • 3.3.2. Delivery platform commissions of 25–30% eroding margins
      • 3.3.3. Intense competition and market fragmentation
      • 3.3.4. Import dependence for food inputs creating supply chain vulnerability
    • 3.4. Market Restraints
      • 3.4.1. High rental and operating costs in prime locations
  • By Outlet

    • Chained/Franchised
    • Independent
  • By Service Model

    • Dine-in
    • Takeaway
    • Drive-thru
    • Home Delivery
  • By Location

    • Leisure
    • Lodging
    • Retail
    • Standalone
    • Travel
  • By Geography
    • Dubai

    • Abu Dhabi

    • Sharjah

    • Northern Emirates

      • Ajman
      • Ras Al Khaimah
      • Fujairah
      • Umm Al Quwain
  • 3.4.2. Delivery platform commissions of 25–30% eroding margins
  • 3.4.3. Intense competition and market fragmentation
  • 3.4.4. Import dependence for food inputs creating supply chain vulnerability
  • 3.5. Market Challenges
    • 3.5.1. Margin pressure from delivery commissions and promotional discounting
    • 3.5.2. Labor cost inflation and staffing challenges
    • 3.5.3. Regulatory compliance and health standards
    • 3.5.4. Supply chain disruptions and food security concerns
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Cuisine
      • 5.1.1. Meat-based
      • 5.1.2. Burger/Sandwich
      • 5.1.3. Pizza
      • 5.1.4. Bakery
      • 5.1.5. Ice Cream
      • 5.1.6. Other
    • 5.2. Market Analysis, Insights and Forecast - by Outlet
      • 5.2.1. Chained/Franchised
      • 5.2.2. Independent
    • 5.3. Market Analysis, Insights and Forecast - by Service Model
      • 5.3.1. Dine-in
      • 5.3.2. Takeaway
      • 5.3.3. Drive-thru
      • 5.3.4. Home Delivery
    • 5.4. Market Analysis, Insights and Forecast - by Location
      • 5.4.1. Leisure
      • 5.4.2. Lodging
      • 5.4.3. Retail
      • 5.4.4. Standalone
      • 5.4.5. Travel
    • 5.5. Market Analysis, Insights and Forecast - by Region
      • 5.5.1. Dubai
      • 5.5.2. Abu Dhabi
      • 5.5.3. Sharjah
      • 5.5.4. Northern Emirates
  • 6. Dubai Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Cuisine
      • 6.1.1. Meat-based
      • 6.1.2. Burger/Sandwich
      • 6.1.3. Pizza
      • 6.1.4. Bakery
      • 6.1.5. Ice Cream
      • 6.1.6. Other
    • 6.2. Market Analysis, Insights and Forecast - by Outlet
      • 6.2.1. Chained/Franchised
      • 6.2.2. Independent
    • 6.3. Market Analysis, Insights and Forecast - by Service Model
      • 6.3.1. Dine-in
      • 6.3.2. Takeaway
      • 6.3.3. Drive-thru
      • 6.3.4. Home Delivery
    • 6.4. Market Analysis, Insights and Forecast - by Location
      • 6.4.1. Leisure
      • 6.4.2. Lodging
      • 6.4.3. Retail
      • 6.4.4. Standalone
      • 6.4.5. Travel
  • 7. Abu Dhabi Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Cuisine
      • 7.1.1. Meat-based
      • 7.1.2. Burger/Sandwich
      • 7.1.3. Pizza
      • 7.1.4. Bakery
      • 7.1.5. Ice Cream
      • 7.1.6. Other
    • 7.2. Market Analysis, Insights and Forecast - by Outlet
      • 7.2.1. Chained/Franchised
      • 7.2.2. Independent
    • 7.3. Market Analysis, Insights and Forecast - by Service Model
      • 7.3.1. Dine-in
      • 7.3.2. Takeaway
      • 7.3.3. Drive-thru
      • 7.3.4. Home Delivery
    • 7.4. Market Analysis, Insights and Forecast - by Location
      • 7.4.1. Leisure
      • 7.4.2. Lodging
      • 7.4.3. Retail
      • 7.4.4. Standalone
      • 7.4.5. Travel
  • 8. Sharjah Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Cuisine
      • 8.1.1. Meat-based
      • 8.1.2. Burger/Sandwich
      • 8.1.3. Pizza
      • 8.1.4. Bakery
      • 8.1.5. Ice Cream
      • 8.1.6. Other
    • 8.2. Market Analysis, Insights and Forecast - by Outlet
      • 8.2.1. Chained/Franchised
      • 8.2.2. Independent
    • 8.3. Market Analysis, Insights and Forecast - by Service Model
      • 8.3.1. Dine-in
      • 8.3.2. Takeaway
      • 8.3.3. Drive-thru
      • 8.3.4. Home Delivery
    • 8.4. Market Analysis, Insights and Forecast - by Location
      • 8.4.1. Leisure
      • 8.4.2. Lodging
      • 8.4.3. Retail
      • 8.4.4. Standalone
      • 8.4.5. Travel
  • 9. Northern Emirates Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Cuisine
      • 9.1.1. Meat-based
      • 9.1.2. Burger/Sandwich
      • 9.1.3. Pizza
      • 9.1.4. Bakery
      • 9.1.5. Ice Cream
      • 9.1.6. Other
    • 9.2. Market Analysis, Insights and Forecast - by Outlet
      • 9.2.1. Chained/Franchised
      • 9.2.2. Independent
    • 9.3. Market Analysis, Insights and Forecast - by Service Model
      • 9.3.1. Dine-in
      • 9.3.2. Takeaway
      • 9.3.3. Drive-thru
      • 9.3.4. Home Delivery
    • 9.4. Market Analysis, Insights and Forecast - by Location
      • 9.4.1. Leisure
      • 9.4.2. Lodging
      • 9.4.3. Retail
      • 9.4.4. Standalone
      • 9.4.5. Travel
  • 10. Competitive Analysis
    • 10.1. Company Profiles
      • 10.1.1. Americana Restaurants International PLC
        • 10.1.1.1. Company Overview
        • 10.1.1.2. Products
        • 10.1.1.3. Company Financials
        • 10.1.1.4. SWOT Analysis
      • 10.1.2. Apparel Group
        • 10.1.2.1. Company Overview
        • 10.1.2.2. Products
        • 10.1.2.3. Company Financials
        • 10.1.2.4. SWOT Analysis
      • 10.1.3. Emirates Fast Food Company
        • 10.1.3.1. Company Overview
        • 10.1.3.2. Products
        • 10.1.3.3. Company Financials
        • 10.1.3.4. SWOT Analysis
      • 10.1.4. Kamal Osman Jamjoom Group LLC
        • 10.1.4.1. Company Overview
        • 10.1.4.2. Products
        • 10.1.4.3. Company Financials
        • 10.1.4.4. SWOT Analysis
      • 10.1.5. The Olayan Group
        • 10.1.5.1. Company Overview
        • 10.1.5.2. Products
        • 10.1.5.3. Company Financials
        • 10.1.5.4. SWOT Analysis
      • 10.1.6. Al Sayer Franchising Company
        • 10.1.6.1. Company Overview
        • 10.1.6.2. Products
        • 10.1.6.3. Company Financials
        • 10.1.6.4. SWOT Analysis
      • 10.1.7. AlAmar Foods Company
        • 10.1.7.1. Company Overview
        • 10.1.7.2. Products
        • 10.1.7.3. Company Financials
        • 10.1.7.4. SWOT Analysis
      • 10.1.8. ALBAIK Food Systems Company S.A.
        • 10.1.8.1. Company Overview
        • 10.1.8.2. Products
        • 10.1.8.3. Company Financials
        • 10.1.8.4. SWOT Analysis
      • 10.1.9. Alghanim Industries & Yusuf A. Alghanim & Sons WLL
        • 10.1.9.1. Company Overview
        • 10.1.9.2. Products
        • 10.1.9.3. Company Financials
        • 10.1.9.4. SWOT Analysis
      • 10.1.10. M.H. Alshaya Co. WLL
        • 10.1.10.1. Company Overview
        • 10.1.10.2. Products
        • 10.1.10.3. Company Financials
        • 10.1.10.4. SWOT Analysis
      • 10.1.11. Ring International Holding AG
        • 10.1.11.1. Company Overview
        • 10.1.11.2. Products
        • 10.1.11.3. Company Financials
        • 10.1.11.4. SWOT Analysis
      • 10.1.12. LuLu Group International
        • 10.1.12.1. Company Overview
        • 10.1.12.2. Products
        • 10.1.12.3. Company Financials
        • 10.1.12.4. SWOT Analysis
      • 10.1.13. Al Khaja Group of Companies
        • 10.1.13.1. Company Overview
        • 10.1.13.2. Products
        • 10.1.13.3. Company Financials
        • 10.1.13.4. SWOT Analysis
      • 10.1.14. Galadari Ice Cream Co. LLC
        • 10.1.14.1. Company Overview
        • 10.1.14.2. Products
        • 10.1.14.3. Company Financials
        • 10.1.14.4. SWOT Analysis
      • 10.1.15. CKE Restaurants Holdings Inc.
        • 10.1.15.1. Company Overview
        • 10.1.15.2. Products
        • 10.1.15.3. Company Financials
        • 10.1.15.4. SWOT Analysis
    • 10.2. Market Entropy
      • 10.2.1. Company's Key Areas Served
      • 10.2.2. Recent Developments
    • 10.3. Company Market Share Analysis, 2026
      • 10.3.1. Top 5 Companies Market Share Analysis
      • 10.3.2. Top 3 Companies Market Share Analysis
    • 10.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global United Arab Emirates Quick Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Dubai United Arab Emirates Quick Service Revenue (Billion), by Cuisine 2026 & 2034
    3. Figure 3: Dubai United Arab Emirates Quick Service Revenue Share (%), by Cuisine 2026 & 2034
    4. Figure 4: Dubai United Arab Emirates Quick Service Revenue (Billion), by Outlet 2026 & 2034
    5. Figure 5: Dubai United Arab Emirates Quick Service Revenue Share (%), by Outlet 2026 & 2034
    6. Figure 6: Dubai United Arab Emirates Quick Service Revenue (Billion), by Service Model 2026 & 2034
    7. Figure 7: Dubai United Arab Emirates Quick Service Revenue Share (%), by Service Model 2026 & 2034
    8. Figure 8: Dubai United Arab Emirates Quick Service Revenue (Billion), by Location 2026 & 2034
    9. Figure 9: Dubai United Arab Emirates Quick Service Revenue Share (%), by Location 2026 & 2034
    10. Figure 10: Dubai United Arab Emirates Quick Service Revenue (Billion), by Country 2026 & 2034
    11. Figure 11: Dubai United Arab Emirates Quick Service Revenue Share (%), by Country 2026 & 2034
    12. Figure 12: Abu Dhabi United Arab Emirates Quick Service Revenue (Billion), by Cuisine 2026 & 2034
    13. Figure 13: Abu Dhabi United Arab Emirates Quick Service Revenue Share (%), by Cuisine 2026 & 2034
    14. Figure 14: Abu Dhabi United Arab Emirates Quick Service Revenue (Billion), by Outlet 2026 & 2034
    15. Figure 15: Abu Dhabi United Arab Emirates Quick Service Revenue Share (%), by Outlet 2026 & 2034
    16. Figure 16: Abu Dhabi United Arab Emirates Quick Service Revenue (Billion), by Service Model 2026 & 2034
    17. Figure 17: Abu Dhabi United Arab Emirates Quick Service Revenue Share (%), by Service Model 2026 & 2034
    18. Figure 18: Abu Dhabi United Arab Emirates Quick Service Revenue (Billion), by Location 2026 & 2034
    19. Figure 19: Abu Dhabi United Arab Emirates Quick Service Revenue Share (%), by Location 2026 & 2034
    20. Figure 20: Abu Dhabi United Arab Emirates Quick Service Revenue (Billion), by Country 2026 & 2034
    21. Figure 21: Abu Dhabi United Arab Emirates Quick Service Revenue Share (%), by Country 2026 & 2034
    22. Figure 22: Sharjah United Arab Emirates Quick Service Revenue (Billion), by Cuisine 2026 & 2034
    23. Figure 23: Sharjah United Arab Emirates Quick Service Revenue Share (%), by Cuisine 2026 & 2034
    24. Figure 24: Sharjah United Arab Emirates Quick Service Revenue (Billion), by Outlet 2026 & 2034
    25. Figure 25: Sharjah United Arab Emirates Quick Service Revenue Share (%), by Outlet 2026 & 2034
    26. Figure 26: Sharjah United Arab Emirates Quick Service Revenue (Billion), by Service Model 2026 & 2034
    27. Figure 27: Sharjah United Arab Emirates Quick Service Revenue Share (%), by Service Model 2026 & 2034
    28. Figure 28: Sharjah United Arab Emirates Quick Service Revenue (Billion), by Location 2026 & 2034
    29. Figure 29: Sharjah United Arab Emirates Quick Service Revenue Share (%), by Location 2026 & 2034
    30. Figure 30: Sharjah United Arab Emirates Quick Service Revenue (Billion), by Country 2026 & 2034
    31. Figure 31: Sharjah United Arab Emirates Quick Service Revenue Share (%), by Country 2026 & 2034
    32. Figure 32: Northern Emirates United Arab Emirates Quick Service Revenue (Billion), by Cuisine 2026 & 2034
    33. Figure 33: Northern Emirates United Arab Emirates Quick Service Revenue Share (%), by Cuisine 2026 & 2034
    34. Figure 34: Northern Emirates United Arab Emirates Quick Service Revenue (Billion), by Outlet 2026 & 2034
    35. Figure 35: Northern Emirates United Arab Emirates Quick Service Revenue Share (%), by Outlet 2026 & 2034
    36. Figure 36: Northern Emirates United Arab Emirates Quick Service Revenue (Billion), by Service Model 2026 & 2034
    37. Figure 37: Northern Emirates United Arab Emirates Quick Service Revenue Share (%), by Service Model 2026 & 2034
    38. Figure 38: Northern Emirates United Arab Emirates Quick Service Revenue (Billion), by Location 2026 & 2034
    39. Figure 39: Northern Emirates United Arab Emirates Quick Service Revenue Share (%), by Location 2026 & 2034
    40. Figure 40: Northern Emirates United Arab Emirates Quick Service Revenue (Billion), by Country 2026 & 2034
    41. Figure 41: Northern Emirates United Arab Emirates Quick Service Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global United Arab Emirates Quick Service Revenue Billion Forecast, by Cuisine 2020 & 2034
    2. Table 2: Global United Arab Emirates Quick Service Revenue Billion Forecast, by Outlet 2020 & 2034
    3. Table 3: Global United Arab Emirates Quick Service Revenue Billion Forecast, by Service Model 2020 & 2034
    4. Table 4: Global United Arab Emirates Quick Service Revenue Billion Forecast, by Location 2020 & 2034
    5. Table 5: Global United Arab Emirates Quick Service Revenue Billion Forecast, by Region 2020 & 2034
    6. Table 6: Dubai United Arab Emirates Quick Service Revenue Billion Forecast, by Cuisine 2020 & 2034
    7. Table 7: Dubai United Arab Emirates Quick Service Revenue Billion Forecast, by Outlet 2020 & 2034
    8. Table 8: Dubai United Arab Emirates Quick Service Revenue Billion Forecast, by Service Model 2020 & 2034
    9. Table 9: Dubai United Arab Emirates Quick Service Revenue Billion Forecast, by Location 2020 & 2034
    10. Table 10: Dubai United Arab Emirates Quick Service Revenue Billion Forecast, by Country 2020 & 2034
    11. Table 11: Abu Dhabi United Arab Emirates Quick Service Revenue Billion Forecast, by Cuisine 2020 & 2034
    12. Table 12: Abu Dhabi United Arab Emirates Quick Service Revenue Billion Forecast, by Outlet 2020 & 2034
    13. Table 13: Abu Dhabi United Arab Emirates Quick Service Revenue Billion Forecast, by Service Model 2020 & 2034
    14. Table 14: Abu Dhabi United Arab Emirates Quick Service Revenue Billion Forecast, by Location 2020 & 2034
    15. Table 15: Abu Dhabi United Arab Emirates Quick Service Revenue Billion Forecast, by Country 2020 & 2034
    16. Table 16: Sharjah United Arab Emirates Quick Service Revenue Billion Forecast, by Cuisine 2020 & 2034
    17. Table 17: Sharjah United Arab Emirates Quick Service Revenue Billion Forecast, by Outlet 2020 & 2034
    18. Table 18: Sharjah United Arab Emirates Quick Service Revenue Billion Forecast, by Service Model 2020 & 2034
    19. Table 19: Sharjah United Arab Emirates Quick Service Revenue Billion Forecast, by Location 2020 & 2034
    20. Table 20: Sharjah United Arab Emirates Quick Service Revenue Billion Forecast, by Country 2020 & 2034
    21. Table 21: Northern Emirates United Arab Emirates Quick Service Revenue Billion Forecast, by Cuisine 2020 & 2034
    22. Table 22: Northern Emirates United Arab Emirates Quick Service Revenue Billion Forecast, by Outlet 2020 & 2034
    23. Table 23: Northern Emirates United Arab Emirates Quick Service Revenue Billion Forecast, by Service Model 2020 & 2034
    24. Table 24: Northern Emirates United Arab Emirates Quick Service Revenue Billion Forecast, by Location 2020 & 2034
    25. Table 25: Northern Emirates United Arab Emirates Quick Service Revenue Billion Forecast, by Country 2020 & 2034
    26. Table 26: Ajman United Arab Emirates Quick Service Revenue (Billion) Forecast, by Application 2020 & 2034
    27. Table 27: Ras Al Khaimah United Arab Emirates Quick Service Revenue (Billion) Forecast, by Application 2020 & 2034
    28. Table 28: Fujairah United Arab Emirates Quick Service Revenue (Billion) Forecast, by Application 2020 & 2034
    29. Table 29: Umm Al Quwain United Arab Emirates Quick Service Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the current size of the UAE Quick Service Restaurant market?

    The UAE QSR market was valued at approximately USD 6.55 billion in 2025 and is projected to reach USD 16.38 billion by 2030, growing at a CAGR of 20.12%.

    2Which cuisine segment dominates the UAE QSR market?

    Meat-based cuisines, including shawarma, fried chicken, and kebabs, dominate the market, with consumption reaching 445,000 tonnes in 2022. Pizza is the fastest-growing cuisine, forecast at a CAGR of 21.03% through 2029.

    3Who are the major players in the UAE QSR market?

    Key players include Americana Restaurants International PLC, Apparel Group, Emirates Fast Food Company, Kamal Osman Jamjoom Group LLC, and The Olayan Group. The top five companies collectively hold about 37.30% of the market.

    4How is food delivery impacting the UAE QSR industry?

    Delivery platforms such as Talabat, Deliveroo, Careem, and Noon Food are driving significant growth, though their 25–30% commissions pressure operator margins. Home delivery is the fastest-growing service model, prompting investment in first-party apps and loyalty programs.

    5What are the main challenges facing QSR operators in the UAE?

    High rental costs in prime locations, labor cost inflation, delivery commission pressure, and intense competition are the primary challenges. Import dependence for food inputs also exposes operators to global price volatility.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Our analysis is built on a 70–80% primary research foundation, comprising structured interviews and surveys with 200+ industry participants across the UAE QSR value chain. These include franchise operators and master franchisees, independent restaurant owners, food delivery platform executives, central kitchen and commissary managers, and supply chain and procurement heads.
    • We conduct in-depth interviews with C-suite executives (CEO/COO), franchise development directors, operations managers, and marketing and digital heads to capture strategic intent and ground-level operational metrics.
    • Primary research is supplemented by site visits and outlet-level observations across Dubai, Abu Dhabi, and Sharjah to validate footfall, menu pricing, and service formats.
    • All primary data is collected under confidentiality agreements and aggregated to protect participant anonymity.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    CEO/COO30%
    Franchise Development Director25%
    Operations Manager25%
    Marketing and Digital Head20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Franchise Operators and Master Franchisees35%
    Independent QSR Owners25%
    Food Delivery Platform Executives15%
    Central Kitchen and Commissary Managers15%
    Supply Chain and Procurement Heads10%

    Secondary Research & Industry Benchmarking

    • Secondary research (20–30% of effort) draws on official government statistics, multilateral databases, and recognized trade associations. Key sources include the UAE Federal Competitiveness and Statistics Centre (FCSC), Dubai Department of Economy and Tourism (DET), World Bank, UN Comtrade, OECD, and UAE Ministry of Economy.
    • We benchmark market metrics against official tourism arrivals, population data, and food import/export statistics from UN Comtrade and national customs authorities.
    • Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to triangulate company-level revenues and investment flows.
    • Industry association publications and technical standards from bodies such as the UAE Food Safety and Quality Authority inform regulatory and compliance analysis.

    Demand Modeling & Market Estimation

    • We employ a dual top-down and bottom-up methodology. The bottom-up model builds market size from outlet-level unit economics: number of QSR outlets, average daily orders per outlet, and average order value. For example, we model ~10,300 outlets, 83 orders/day, and an average order value of USD 12.37 (2022 baseline) to derive a base-year market estimate, which is then projected forward using segment-specific growth rates.
    • The top-down approach sizes the market from total consumer foodservice spending, tourism receipts, and population-level consumption frequency, cross-validated with national accounts data.
    • Multi-level data triangulation reconciles bottom-up and top-down estimates, with variance thresholds set at ±5%. Segment-level CAGRs are validated against historical outlet expansion, digital adoption curves, and tourism forecasts.

    Data Accuracy & Quality Check

    • We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous cross-validation and expert review.
    • Every data point is subjected to a three-tier verification process: (1) primary interview validation, (2) secondary source triangulation, and (3) internal analyst review.
    • Outlier detection and sanity checks are applied to all quantitative inputs. Where primary and secondary data diverge beyond acceptable thresholds, additional expert interviews are conducted.
    • Reports are updated to the date of purchase, ensuring the latest available data and market developments are reflected.
    • All sources are documented, and only official government, multilateral, or recognized non-profit trade association sources are cited. No commercial market research firm data is used.