1What is the size of the UAE ecommerce market in 2026?
The UAE ecommerce market is valued at USD 12.30 Billion in 2026 and is projected to reach USD 21.01 Billion by 2031, growing at a CAGR of 11.29%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 United Arab Emirates Ecommerce Market
 by Business Model (B2C, B2B), by Device Type (Smartphone/Mobile, Desktop and Laptop, Others), by Payment Method (Credit/Debit Cards, Digital Wallets, BNPL, Others), by B2C Product Category (Beauty and Personal Care, Consumer Electronics, Fashion and Apparel, Food and Beverages, Furniture and Home, Others), by Dubai, by Abu Dhabi, by Sharjah, by Ajman, by Ras Al Khaimah, by Fujairah, by Umm Al Quwain Forecast 2026-2034

Research Analyst


 Related Reports

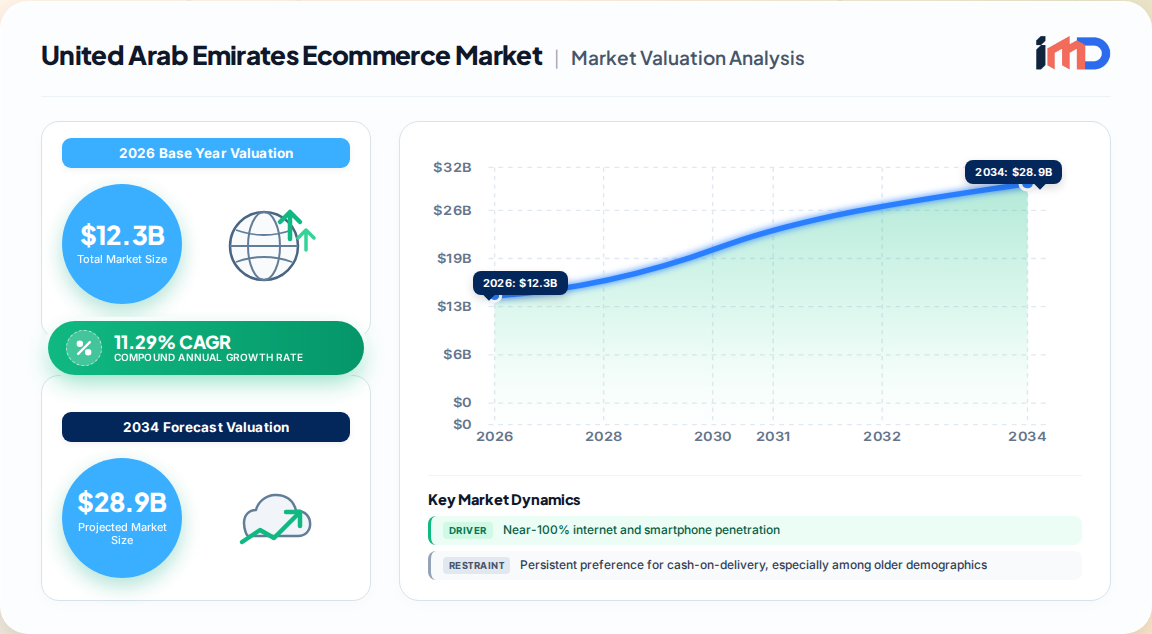
The United Arab Emirates ecommerce market is the most mature and digitally advanced retail ecosystem in the Gulf Cooperation Council (GCC), with our proprietary primary research valuing the market at USD 12.30 Billion in 2026. This represents a significant leap from USD 3.9 Billion in 2020, when the pandemic catalyzed a structural shift toward online purchasing. We project the market to reach USD 21.01 Billion by 2031, expanding at a robust CAGR of 11.29% over the forecast period (2026-2031).
This growth is underpinned by near-universal internet penetration (approaching 100% of the population), the highest smartphone adoption rate in the MENA region, and a regulatory environment actively fostering digital commerce through initiatives such as the Dubai Free Zones Council ecommerce regulations and the nationwide Aani instant-payment rail.
| Key Market Metric | 2026 Value | 2031 Projection |
|---|---|---|
| Market Size (USD) | 12.30 Billion | 21.01 Billion |
| CAGR (2026-2031) | 11.29% | - |
| B2C Buyer Penetration | ~78% | ~88% (est.) |
| Mobile Commerce Share of Revenue | ~65% | ~75% (est.) |
The UAE ecommerce market is propelled by a confluence of structural and behavioral drivers that are unique to the region's demographic and infrastructural profile.
Despite its advanced infrastructure, the UAE ecommerce market faces several persistent headwinds that temper growth and require strategic navigation.
The UAE ecommerce market is segmented by business model, device type, payment method, and B2C product category. Our analysis reveals distinct growth patterns across these segments.
By B2C Product Category
Fashion and apparel remains the largest B2C segment, accounting for 28.1% of the Middle East ecommerce market in 2024, driven by a cultural emphasis on style and social media trends. Consumer electronics and appliances, media products, computers, fashion accessories, women's apparel, cosmetics, and perfumes are the highest revenue-generating categories in the UAE. The food and beverage segment is projected to grow at the fastest CAGR of 18.9% through 2034, fueled by online grocery services and convenience-driven urban lifestyles.
| Product Category | Market Share (2024) | Growth Outlook |
|---|---|---|
| Fashion and Apparel | 28.1% (regional) | Steady growth, driven by social commerce |
| Consumer Electronics | ~20% (UAE est.) | Moderate, replacement cycles |
| Food and Beverage | ~12% (UAE est.) | Fastest growing, 18.9% CAGR (regional) |
| Beauty and Personal Care | ~10% (UAE est.) | High growth, influencer-driven |
| Furniture and Home | ~8% (UAE est.) | Emerging, AR visualization driving conversion |
By Payment Method
Credit and debit cards remain the dominant payment method, but digital wallets and BNPL are rapidly gaining share. The availability of diverse payment types is a key competitive differentiator, with platforms increasingly integrating multiple options to cater to consumer preferences.
By Device Type
Smartphones and mobile devices account for the majority of ecommerce transactions, reflecting the UAE's mobile-first consumer behavior. Desktop and laptop purchases remain relevant for certain categories such as consumer electronics and furniture, where consumers prefer larger screens for research and comparison.
The UAE ecommerce market is characterized by a dynamic and competitive landscape featuring global marketplace giants, strong homegrown champions, and nimble social commerce players. The market concentration is medium, with the top players holding significant but not overwhelming share.
| Company | Headquarters | Key Strength |
|---|---|---|
| Amazon.ae | UAE (global parent) | Global supply chain, Prime ecosystem |
| Noon.com | UAE | Regional focus, Arabic-first, local partnerships |
| Carrefour UAE | UAE (Majid Al Futtaim) | Omnichannel integration, hypermarket network |
| Lulu Group | UAE | Grocery and hypermarket dominance, online portal |
| Namshi | UAE | Fashion-focused, youth demographic |
| Sharaf DG | UAE | Electronics expertise, brand trust |
Within the UAE, ecommerce activity is concentrated in Dubai, which accounts for an estimated 38% of the national market, followed by Abu Dhabi at 27%. Sharjah, Ajman, Ras Al Khaimah, Fujairah, and Umm Al Quwain collectively represent the remaining share, with Sharjah emerging as a logistics and fulfillment hub due to its proximity to Dubai and lower operating costs.
Our research identifies several strategic white spaces for investors and ecommerce operators seeking to capitalize on the UAE market's growth trajectory.
The UAE's ecommerce market is heavily reliant on imports, with 58% of online purchases made from overseas vendors. This cross-border dependence shapes the supplier landscape and logistics requirements. Key import categories include consumer electronics, fashion apparel, beauty products, and luxury goods, sourced primarily from China, the United States, Europe, and India.
| Import Source | Key Categories | Logistics Advantage |
|---|---|---|
| China | Electronics, fashion, household | Free zone re-export, sea freight |
| USA | Luxury, cosmetics, electronics | Air freight, brand trust |
| Europe | Fashion, beauty, luxury | Air freight, premium positioning |
| India | Apparel, textiles, food | Sea freight, diaspora networks |
The UAE's free zones (Jebel Ali Free Zone, Dubai Internet City, Dubai CommerCity) play a critical role in facilitating cross-border ecommerce, offering tax incentives, streamlined customs procedures, and world-class logistics infrastructure. These free zones enable foreign direct investment and position the UAE as a regional distribution hub for ecommerce in the Middle East and Africa.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.29% from 2020-2034 |
| Segmentation |
|
By Payment Method
By B2C Product Category
| By Geography |
|
The UAE ecommerce market is valued at USD 12.30 Billion in 2026 and is projected to reach USD 21.01 Billion by 2031, growing at a CAGR of 11.29%.
Major players include Amazon.ae (formerly Souq.com), Noon.com, Carrefour UAE, Lulu Group, Namshi, and Sharaf DG, alongside traditional retailers expanding online.
Despite digital payment growth, nearly 45% of online shoppers in the region still prefer cash-on-delivery due to concerns about fraud, lack of return policies, and unfamiliarity with digital transactions, though this is declining with fintech adoption.
Approximately 58% of online purchases by UAE shoppers are made from overseas vendors, driven by trust in gateway security and reliable free shipping methods.
Fashion and apparel is the largest category, accounting for 28.1% of the regional market in 2024, followed by consumer electronics, food and beverage, beauty, and furniture.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Digital Officer | 25% |
| Ecommerce Director | 35% |
| Head of Omnichannel Strategy | 20% |
| Supply Chain Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Marketplace Operators | 30% |
| Omnichannel Retailers | 25% |
| Pure-Play Ecommerce Platforms | 20% |
| Logistics and Last-Mile Providers | 15% |
| Payment Gateways and BNPL Fintechs | 10% |