1What is the current size of the third-party chemical distribution market?
The global third-party chemical distribution market was valued at US$ 293.92 Billion in 2024 and is projected to reach US$ 392.01 Billion by 2031, growing at a CAGR of 4.20%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Third-Party Chemical Distribution Market
 by Commodity Chemicals (Coatings, Adhesives, Sealants, and Elastomers; Agrochemicals; Construction Chemicals; Specialty Polymer & Resins; Others), by Specialty Chemicals (Plastics & Polymers, Synthetic Rubbers, Explosives, Petrochemicals, Others), by End User (Automotive, Electronics, Construction, Oil & Gas, Pharmaceuticals, Others), by North America (US, Canada, Mexico), by Europe (Germany, UK, France, Russia, Italy, Rest of Europe), by Asia-Pacific (China, India, Japan, Australia, Rest of Asia-Pacific), by South and Central America (Brazil, Argentina, Rest of South and Central America), by Middle East and Africa (South Africa, Saudi Arabia, UAE, Rest of Middle East and Africa) Forecast 2026-2034

Senior Analyst


 Related Reports

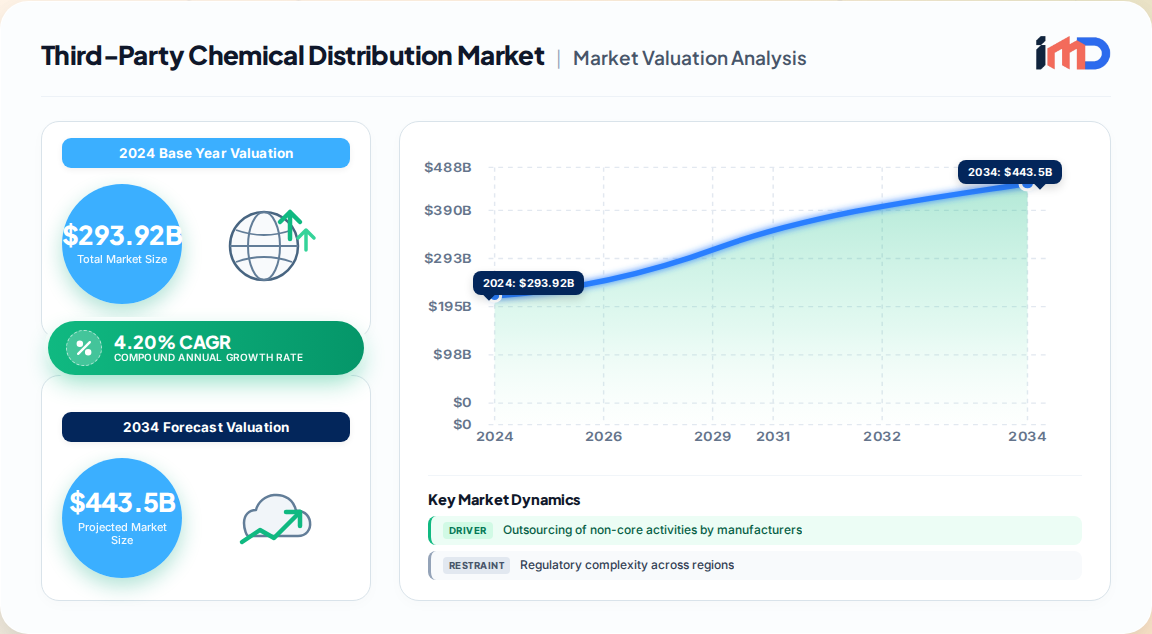
The global Third-Party Chemical Distribution Market is a critical enabler of the chemical industry value chain, bridging manufacturers with end-users across diverse sectors. Our proprietary primary research estimates the market at US$ 293.92 Billion in 2024, projected to reach US$ 392.01 Billion by 2031, registering a CAGR of 4.20% over the forecast period (2025–2031). This growth is underpinned by the increasing outsourcing of non-core logistics and value-added services by chemical producers, coupled with rising demand from end-use industries such as automotive, electronics, construction, oil & gas, and pharmaceuticals.
Third-party distributors provide essential services including transportation, warehousing, custom blending, repackaging, inventory management, and regulatory compliance support. The market is highly fragmented, with global players competing alongside regional specialists. Europe remains the largest regional market, accounting for approximately 35% of global share in 2025, driven by a mature industrial base and stringent regulatory frameworks like REACH. Asia-Pacific is identified as the fastest-growing region, propelled by rapid industrialization and expanding manufacturing footprints in countries such as China and India.
The third-party chemical distribution value chain comprises several key stages:
| Stage | Description | Key Participants |
|---|---|---|
| Upstream | Chemical manufacturers producing commodity and specialty chemicals | BASF, Dow, DuPont, SABIC |
| Distribution | Third-party distributors providing logistics, storage, and value-added services | Brenntag, Univar, IMCD, Azelis |
| Downstream | End-user industries purchasing chemicals | Automotive, Electronics, Construction, Pharma |
Distributors add value through custom blending, repackaging, just-in-time delivery, and regulatory support, effectively acting as an extension of manufacturers' sales and service arms. The increasing trend of outsourcing non-core activities is expected to deepen distributor penetration across end-use sectors.
Europe dominates the global third-party chemical distribution market, accounting for approximately 35% of global share in 2025. The region's leadership is attributed to a highly industrialized base, stringent safety and environmental regulations, and well-established logistics infrastructure. Germany, the UK, and France are key markets within Europe.
North America holds the second-largest share, supported by a mature chemical industry and a strong focus on supply chain efficiency. The United States represents a key market, with distributors investing in digital platforms and sustainable solutions.
Asia-Pacific is poised to be the fastest-growing region, with a projected CAGR above the global average. Rapid industrialization in China, India, and Southeast Asia, coupled with expanding manufacturing activities, is driving demand for third-party distribution services. Government initiatives promoting domestic manufacturing (e.g., "Make in India") further bolster market growth.
South America and the Middle East & Africa represent emerging markets with growing investment opportunities, albeit from a smaller base. Brazil and Argentina are prominent markets in South America, while Saudi Arabia and the UAE lead in the Middle East.
The market is highly competitive, featuring a mix of global majors and regional specialists. Key players include Azelis, BARENTZ, Brenntag North America, Inc., ICC Chemical Corporation, IMCD N.V., Jebsen and Jessen Pte Ltd., Petrochem, Protea Chemicals, REDA Chemicals, and Univar Inc. These companies are actively pursuing growth strategies such as mergers & acquisitions, digital transformation, and expansion of value-added services.
Recent industry developments include:
Global trade in chemicals is substantial, with major flows from manufacturing hubs in Asia-Pacific, Europe, and North America. According to UN Comtrade data, global chemical exports exceeded US$ 2.5 Trillion in 2023, with third-party distributors playing a pivotal role in facilitating cross-border transactions. Key supplier regions include China, the US, Germany, and the Netherlands, while demand centers are widespread across all continents.
Distributors must navigate complex import/export regulations, including tariffs, chemical registration requirements, and hazardous materials transport rules. The rise of regional trade agreements (e.g., RCEP, USMCA) is expected to streamline trade flows, benefiting distributors with established networks. However, geopolitical tensions and supply chain disruptions (e.g., Red Sea shipping delays) pose risks that require agile supplier diversification strategies.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.20% from 2020-2034 |
| Segmentation |
|
By End User
| By Geography |
|
The global third-party chemical distribution market was valued at US$ 293.92 Billion in 2024 and is projected to reach US$ 392.01 Billion by 2031, growing at a CAGR of 4.20%.
Europe leads the market, accounting for approximately 35% of global share in 2025, driven by a strong industrial base and stringent regulatory environment.
Key drivers include increasing partnerships between chemical manufacturers and distributors, digitalization of supply chains, and growing demand for sustainable distribution solutions.
Major players include Brenntag, Univar Solutions, IMCD, Azelis, and BARENTZ, among others, who are actively pursuing M&A and digital transformation strategies.
Specialty chemicals distribution is expected to grow at a faster pace, fueled by demand from electronics, pharmaceuticals, and personal care industries.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 35% |
| Supply Chain Manager | 30% |
| Regulatory Affairs Specialist | 20% |
| Operations Manager | 15% |
| Company Type | Representation (%) |
|---|---|
| Chemical Manufacturers | 30% |
| Third-Party Distributors | 35% |
| Logistics & Warehousing Providers | 15% |
| End-User Industries | 15% |
| Regulatory Bodies & Associations | 5% |