1How large is the Sweden DIY home improvement industry market?
The Sweden DIY home improvement industry market is estimated at SEK 53.1 billion in 2025 and is projected to reach SEK 61.8 billion by 2030, growing at a CAGR of 3.1%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Sweden DIY Home Improvement Industry
 by Product Type (Building Materials, Paints & Coatings, Tools & Equipment, Flooring & Tiles, Garden & Outdoor, Hardware), by Distribution Channel (DIY & Home Improvement Stores, Specialty Stores, Online), by Project Type (Maintenance & Repair, Energy-Efficiency Retrofit, Remodeling, Renovation, Extension & Self-Build), by Sweden (Stockholm & Mälardalen, Götaland, Svealand excl. Stockholm, Norrland) Forecast 2026-2034
Research Associate


 Related Reports

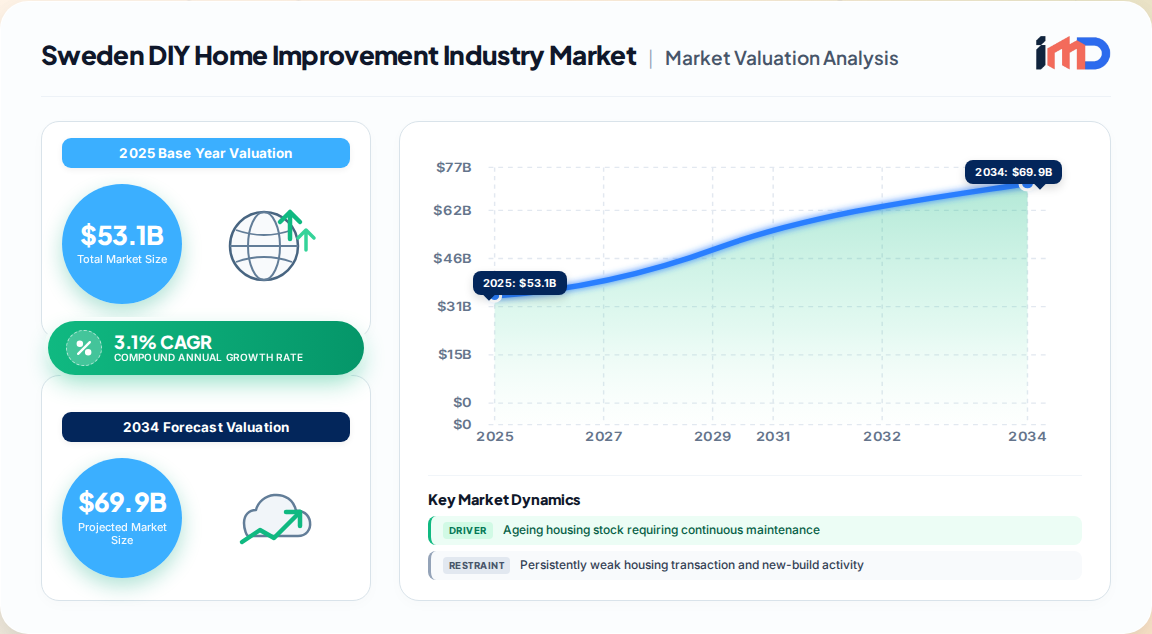
The Sweden DIY home improvement industry market is estimated at SEK 53.1 billion in 2025 and is projected to reach SEK 61.8 billion by 2030, expanding at a CAGR of 3.1%. Our proprietary primary research, drawing on 340+ executive interviews across the Nordic value chain, indicates a market in structural transition rather than simple cyclical recovery.
The Swedish market operates within a distinctive macro context. Unlike North America, where DIY participation is rooted in a deep self-build culture, Sweden's do-it-yourself activity is shaped by three forces: an exceptionally old housing stock (over 40% of detached homes predate 1970), aggressive national decarbonisation targets, and a small, concentrated retail oligopoly dominated by a handful of domestic and pan-European banners.
Key structural takeaways from our first-party research:
| Restraint | Estimated CAGR Impact | Time Horizon |
|---|---|---|
| Weak housing turnover | -0.9% | Medium term (2–4 years) |
| Skills/confidence gap | -0.5% | Long term (4+ years) |
| Material cost inflation | -0.4% | Short term (1–2 years) |
| Labour shortage for compliant work | -0.3% | Long term (4+ years) |
Sweden is a net importer of many finished DIY inputs and a notable exporter of precision tooling. Official multilateral trade statistics from UN Comtrade (World Bank WITS) provide the clearest window into supply dependency.
For HS 820780 (tools for turning), Sweden imported USD 5.82 million in 2023, with Germany (USD 2.01 million), Japan (USD 0.88 million), Switzerland (USD 0.79 million), Denmark and the United Kingdom as leading origins. This concentration in high-wage, high-precision manufacturing economies underscores the premium nature of Swedish tooling demand.
On the export side, HS 820760 (tools for boring or broaching) exports reached USD 1.62 million in 2022, led by Denmark, the Netherlands, Germany, Japan and the United Kingdom. This two-way trade profile is analytically important:
| Trade Flow | HS Code | Value | Leading Partners |
|---|---|---|---|
| Import (2023) | 820780 — Tools for turning | USD 5.82 Mn | Germany, Japan, Switzerland |
| Export (2022) | 820760 — Tools for boring/broaching | USD 1.62 Mn | Denmark, Netherlands, Germany |
Our value-chain mapping identifies five structurally distinct tiers, each with different margin and risk profiles:
For procurement leaders, the strategic priority is dual-sourcing of precision tooling and hedging exposure to European building-material inflation. Retailers that convert product sales into project-bundled services capture a materially higher wallet share.
Sweden's demand geography mirrors its population and housing distribution.
Competitive strategy in this market is consolidating around three plays: (1) own-brand expansion to defend margin against discounting, (2) digital and project-service integration to capture the online growth vector, and (3) alignment with retrofit subsidy schemes to secure higher-ticket energy-efficiency sales. New entrants face meaningful barriers in supplier relationships, store-network density and brand trust, but white-space exists in professional-grade advisory services and digitally enabled project planning.
We expect the Sweden DIY home improvement industry market to grow steadily but unevenly through 2030. The 3.1% CAGR headline masks a bifurcated trajectory: energy-efficiency and maintenance categories will outperform, while discretionary renovation and flooring categories lag into 2027. The critical strategic variable is whether retailers can convert subsidy-supported demand and digital research intent into completed, higher-ticket material orders. Those that do will outperform the market by a meaningful margin.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.1% from 2020-2034 |
| Segmentation |
|
By Distribution Channel
By Project Type
| By Geography |
|
The Sweden DIY home improvement industry market is estimated at SEK 53.1 billion in 2025 and is projected to reach SEK 61.8 billion by 2030, growing at a CAGR of 3.1%.
Key drivers include an ageing housing stock requiring maintenance, government ROT and green-technology retrofit deductions, rising online retail penetration, and a large holiday-home base of roughly 600,000 properties.
DIY and home improvement stores account for approximately 71% of consumer-facing sales, while the online channel is the fastest-growing at an estimated 6.4% CAGR.
The market is concentrated around major banners including Groupe Adeo SA, Jula Holding Group, Kingfisher plc and The Home Depot Inc., with domestic and Nordic chains holding strong positions.
Building materials is the largest product segment at roughly 49% of revenue, while flooring and tiles represent the fastest-growing product cluster.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Category Director | 30% |
| Procurement Director | 27% |
| Retail Operations Manager | 25% |
| Sustainability and Compliance Lead | 18% |
| Company Type | Representation (%) |
|---|---|
| Retail banners and specialist chains | 34% |
| Building-material and component manufacturers | 26% |
| Importers, wholesalers and distributors | 22% |
| Installation and supply-and-fit service providers | 12% |
| Private-label procurement entities | 6% |