Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Professional and Commercial Services / MARKET REPORT
Sustainability Consulting Services Market | Insight Market Data
Sustainability Consulting Services Market by Service Type (Climate-Change Consulting, ESG Reporting, Green-Building Consulting, Circular Economy and Resource-Efficiency Consulting), by End-User Industry (Energy and Power, Construction and Real Estate, Manufacturing and Industrials, Financial Services, Consumer Goods and Retail), by Consulting Delivery Model (Strategy and Advisory, Implementation, Digital Platforms and Analytics, Managed Services), by Sustainability Focus Area (Climate-Change and Net-Zero, Biodiversity and Nature-Based Solutions, Social Impact, Sustainable Finance), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia-Pacific (China, Japan, India, Australia), by South America (Brazil), by Middle East & Africa Forecast 2026-2034
Commissioning service market to reach $11.17B by 2034 at 6.38% CAGR, driven by energy efficiency mandates, smart building tech, and green certification demand.
Nov 2026|277 pages
$2900.00
The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.
Nov 2026|272 pages
$2900.00
B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.
Nov 2026|209 pages
$2900.00
Global mould detection service market valued at $6.8B in 2025, projected to reach $13.2B by 2034 at 7.6% CAGR. AI diagnostics, IAQ compliance, and thermal imaging drive growth.
Executive Overview: The Sustainability Consulting Services Market (2026–2035)
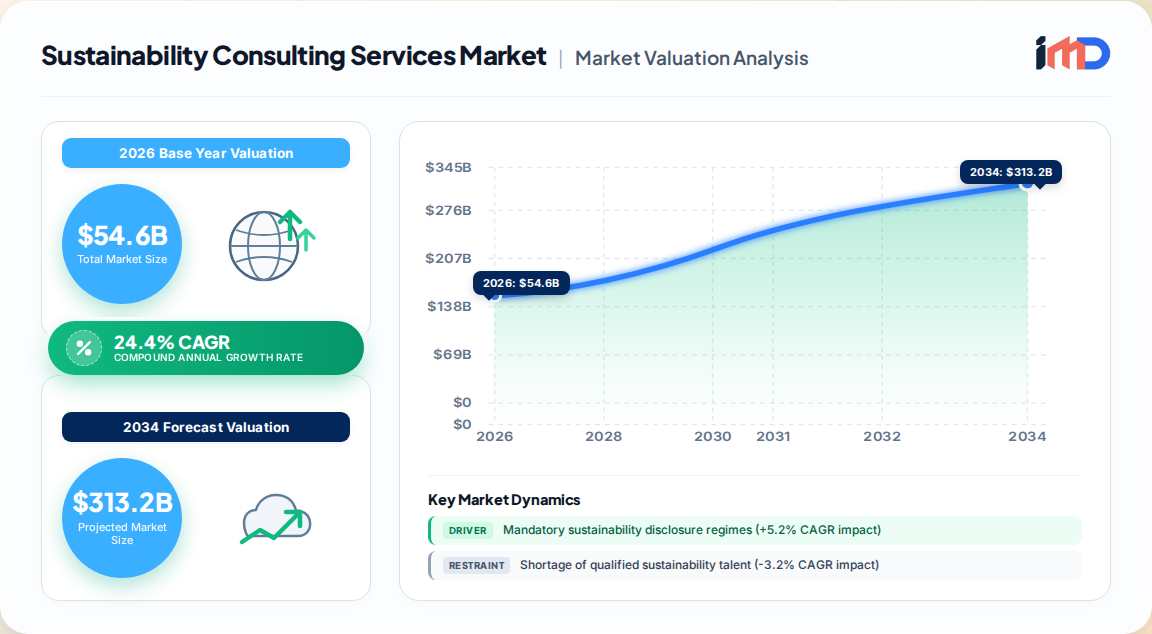
The sustainability consulting services market is undergoing a structural re-rating. Our proprietary primary research places the market at USD 43.4 billion in 2025, expanding to USD 54.6 billion in 2026 and reaching USD 389.6 billion by 2035, a CAGR of 24.4% across the 2026–2035 forecast window.
Sustainability Consulting Services Market Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
43.89 B
2025
54.60 B
2026
67.92 B
2027
84.50 B
2028
105.1 B
2029
130.8 B
2030
162.7 B
2031
This is no longer an aspirational advisory category. Sustainability consulting has migrated from marketing-adjacent CSR support into an audited, board-level obligation that mirrors financial reporting in rigour, cadence and assurance requirements.
Europe anchors demand with a 37.5% revenue share in 2025, underpinned by the Corporate Sustainability Reporting Directive (CSRD) and the EU Taxonomy.
North America generates USD 13.45 billion in 2025 revenue, a 31.0% share, driven by California SB 253 and investor-led disclosure pressure.
Asia-Pacific is the fastest-expanding theatre at a 28.6% CAGR as China, Japan, Australia and India phase in mandatory reporting.
The decisive competitive variable over the next decade is the ability to pair sector depth with scalable data, assurance and integration capability. Firms that remain pure strategy advisors will cede ground to providers who can design, build and operate assurance-ready ESG systems.
Demand Drivers Reshaping Advisory Spend
Demand is being pulled by six identifiable engines, each with a measurable impact on growth.
Driver
Estimated CAGR Impact
Geographic Concentration
Impact Timeline
Mandatory sustainability disclosure regimes
+5.2%
Europe, North America, Asia-Pacific
Medium term (2–4 yrs)
Net-zero target setting and validation
+3.9%
Global
Long term (≥4 yrs)
Investor and lender ESG integration
+3.6%
Europe, North America
Short term (≤2 yrs)
Scope 3 supply-chain decarbonisation
+3.1%
Global; Asia-Pacific manufacturing hubs
Medium term (2–4 yrs)
Public clean-energy and industrial-transition funding
+2.4%
North America, Europe, Asia-Pacific
Long term (≥4 yrs)
Physical climate risk and insurance repricing
+1.8%
Global; coastal markets
Medium term (2–4 yrs)
Disclosure law is the single largest demand engine. The CSRD, as originally adopted, extended reporting duties to roughly 50,000 companies, and its European Sustainability Reporting Standards require double-materiality assessments that most clients cannot execute without external support. By mid-2025, 36 jurisdictions had adopted or were finalising adoption of ISSB standards (IFRS S1 and S2).
Net-zero has hardened into validated commitments. More than 7,000 companies held Science Based Targets initiative-validated targets by the end of 2024. Each validation triggers baselining, pathway modelling, abatement-cost analysis and recurring progress tracking — targets set in 2020–2022 now face 2030 interim milestones, shifting clients from target-setting into implementation and capital-allocation advisory.
Restraints and Margin Pressures
The growth trajectory is not frictionless. Three restraints materially temper near-term revenue realisation.
Acute talent shortage (-3.2% CAGR impact): professionals combining climate science, regulatory fluency and systems engineering remain scarce, most severely in North America and Western Europe. The result is billing-rate inflation alongside delivery-capacity constraints.
Regulatory certainty gaps and litigation risk (-2.1%): the European Omnibus proposal and federal-level pullbacks in the United States have created scope ambiguity, delaying some compliance spending.
Off-the-shelf SaaS sustainability tools (-1.8%): commoditised disclosure and carbon-accounting software compresses low-end advisory pricing, forcing consultants up the value curve.
Client behaviour is compounding this pressure. Buyers are moving away from broad, process-heavy programmes toward targeted, outcome-driven engagements with measurable cost savings, efficiency gains and risk reduction.
Service-Type and Delivery-Model Segmentation
Revenue composition reveals where value is concentrated and where it is migrating.
Segment
2025 Share / Growth
Structural Read
Climate-change consulting
27.2%–29.1% share
Entry point for most disclosure programmes
Strategy and advisory delivery
32.5%–34.8% share
Materiality, target setting, board education
Digital platforms and analytics
28.3%–30.3% CAGR
Fastest-scaling delivery route
Circular-economy consulting
27.1%–29.1% CAGR
Material costs and landfill rules tighten
Biodiversity and nature-based solutions
29.8%–31.9% CAGR
Nature-related disclosure gaining traction
Energy and power (end-user)
22.2%–23.8% share
Utility and oil-and-gas decarbonisation
Manufacturing (end-user)
25.0%–26.7% CAGR
Scope 3 requirements cascading through value chains
The delivery methodology inside client organisations is fundamentally changing. Annual CSR reports assembled from spreadsheets and email polling are being replaced by continuous ESG data platforms, automated carbon accounting and assurance-ready systems that resemble financial reporting. Advisors now sell system design, data governance and integration — not report drafting.
Strategy and advisory remains the largest revenue pool, but digital platforms and analytics is where incremental margin and client lock-in accrue. Firms that own the data architecture own the recurring engagement.
Regional Outlook and Investment Attractiveness
Region
2025 Position
Forward Signal
Europe
37.5%–38.7% share; largest market
CSRD cohort phasing; Omnibus scope debate
North America
31.0% share; USD 13.45B in 2025
State-level mandates; investor demand
Asia-Pacific
27.9%–28.6% CAGR; fastest growth
China, India, Japan, Australia mandates
Middle East & Africa
Emerging
Sovereign-wealth sustainability mandates
South America
Emerging
Brazil regulatory momentum
The allocation of spend is also shifting geographically. Although regulatory progress appears uneven — particularly with the Omnibus proposal in Europe and federal pullbacks in the United States — momentum remains strong in Asia, Brazil and California. From 2028 to 2030, greater regulatory clarity, evolving investor expectations and intensifying physical risk are expected to create a more stable and predictable investment environment.
Competition is intensifying yet the market remains sufficiently fragmented for global majors and niche boutiques to capture share. The leading tier comprises global multi-service firms with climate practices, engineering and environmental consultancies, and technology-services providers with ESG platforms.
Three white-space clusters stand out for 2026–2035:
Nature-related risk and biodiversity advisory — expected to post a 29.8%–31.9% CAGR as TNFD-aligned disclosure gains traction.
Emerging-market disclosure mandates — Asia-Pacific and Latin American filers need localised, low-cost compliance pathways.
Managed reporting and data-driven business models — recurring, subscription-style ESG reporting operations replacing project-based advisory.
Regionally, differentiation will deepen as policy environments, regulatory developments and sustainability risk profiles shape distinct pathways. Service providers must develop sector-focused offerings reflecting the operational context of their clients rather than generic frameworks.
Value Chain Analysis
The sustainability consulting value chain is compressing and re-intermediating simultaneously.
Internal controls, audit trails, verification support
Expanding rapidly
Continuous reporting operations
Managed reporting, dashboards, disclosure filing
Subscription-style recurring revenue
AI engines now ingest utility bills, IoT sensor streams and supplier invoices to calculate product-level footprints in near real time. This does not eliminate consultants — it relocates them from tactical quantification to scenario modelling, abatement prioritisation and financial-impact analysis.
Strategic Recommendations
Build assurance-grade capability. Clients increasingly require systems that withstand third-party verification. Firms without assurance readiness will be disintermediated by audit networks.
Invest in digital delivery platforms. Digital platforms are expanding at 28.3%–30.3% CAGR — the fastest delivery route — and generate recurring revenue.
Prioritise Asia-Pacific. At a 28.6% CAGR, the region offers the strongest incremental revenue pool through 2035.
Address the talent constraint structurally. Acquire boutiques in biodiversity, nature and circular economy to buy capability rather than build it.
Shift pricing to outcomes. Outcome-driven engagements delivering measurable cost savings, efficiency and risk reduction command premium fees and survive budget scrutiny.
Table 23: Asia-Pacific Sustainability Consulting Services Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 24: Asia-Pacific Sustainability Consulting Services Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 25: Asia-Pacific Sustainability Consulting Services Market Revenue Billion Forecast, by Consulting Delivery Model 2020 & 2034
Table 26: Asia-Pacific Sustainability Consulting Services Market Revenue Billion Forecast, by Sustainability Focus Area 2020 & 2034
Table 27: Asia-Pacific Sustainability Consulting Services Market Revenue Billion Forecast, by Country 2020 & 2034
Table 28: China Sustainability Consulting Services Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Japan Sustainability Consulting Services Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: India Sustainability Consulting Services Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Australia Sustainability Consulting Services Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: South America Sustainability Consulting Services Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 33: South America Sustainability Consulting Services Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 34: South America Sustainability Consulting Services Market Revenue Billion Forecast, by Consulting Delivery Model 2020 & 2034
Table 35: South America Sustainability Consulting Services Market Revenue Billion Forecast, by Sustainability Focus Area 2020 & 2034
Table 36: South America Sustainability Consulting Services Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: Brazil Sustainability Consulting Services Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Middle East & Africa Sustainability Consulting Services Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 39: Middle East & Africa Sustainability Consulting Services Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 40: Middle East & Africa Sustainability Consulting Services Market Revenue Billion Forecast, by Consulting Delivery Model 2020 & 2034
Table 41: Middle East & Africa Sustainability Consulting Services Market Revenue Billion Forecast, by Sustainability Focus Area 2020 & 2034
Table 42: Middle East & Africa Sustainability Consulting Services Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the current size of the sustainability consulting services market?
Our proprietary research values the market at USD 43.4 billion in 2025, rising to USD 54.6 billion in 2026. It is forecast to reach USD 389.6 billion by 2035 at a 24.4% CAGR.
2Which region dominates the sustainability consulting services market?
Europe holds the largest share at approximately 37.5% in 2025, supported by the CSRD and EU Taxonomy. North America follows with 31.0% and USD 13.45 billion in revenue.
3Which segment is growing fastest in sustainability consulting?
Digital platforms and analytics is the fastest-scaling delivery model at roughly 28.3% CAGR, while biodiversity and nature-based solutions is the fastest-growing focus area at up to 31.9% CAGR.
4Why is regulatory disclosure driving consulting demand?
The EU CSRD extends reporting duties to roughly 50,000 companies, and 36 jurisdictions had adopted or were finalising ISSB standards by mid-2025. Each mandate generates gap assessments, data-system builds and assurance-readiness work.
5What is the biggest restraint on the sustainability consulting market?
An acute talent shortage, with an estimated -3.2% impact on CAGR, is the most significant restraint, most severe in North America and Western Europe and driving billing-rate inflation.
6Which end-user industries spend the most on sustainability consulting?
Energy and power accounts for roughly 22.2%–23.8% of spend, while manufacturing and financial services lead overall investment given their operational complexity and extensive value chains.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of total research effort is allocated to primary intelligence gathering, executed through structured and semi-structured interviews, and an annual buyer survey programme.
We conduct 350+ interviews per annual cycle with sustainability practice leaders, corporate buyers and assurance specialists across the value chain.
Company types engaged include global multi-service consultants with climate practices, engineering and environmental consultancies, specialist ESG and carbon-accounting boutiques, ESG data and software platform vendors, and assurance and verification providers.
Stakeholder job titles interviewed include Chief Sustainability Officer, Head of ESG Reporting, Director of Climate Strategy, and Procurement and Vendor Management Lead.
Direct consultations are supplemented with board-level briefings and validation calls with CDP-disclosing corporations and Science Based Targets initiative (SBTi) technical contacts.
Industry and regulatory bodies cross-referenced include the IFRS Foundation (ISSB), CDP, the Science Based Targets initiative (SBTi), and Eurostat's environmental goods and services sector (EGSS) framework under the UN System of Environmental-Economic Accounting.
Grievance and methodology notes are maintained with GDPR-compliant anonymisation; raw transcripts are retained for audit.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Sustainability Officer
32%
Head of ESG Reporting
26%
Director of Climate Strategy
24%
Procurement and Vendor Management Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Global multi-service consultancies with climate practices
28%
Engineering and environmental consultancies
22%
Specialist ESG and carbon-accounting boutiques
20%
ESG data and software platform vendors
18%
Assurance and verification providers
12%
Secondary Research & Industry Benchmarking
Approximately 20–30% of research effort draws on secondary verification, regulatory filings and official statistical series.
Standard financial databases used include Bloomberg, Factiva, Hoovers, and PitchBook for listed-consultancy practice revenue and segment reconciliations.
Primary regulatory instruments reviewed: the EU Corporate Sustainability Reporting Directive (CSRD) and European Sustainability Reporting Standards, the EU Taxonomy, ISSB IFRS S1 and S2, and California SB 253.
Historical values for 2021–2024 are reconciled against reported segment revenues and regulatory implementation timelines.
Every report is updated to the date of purchase, with regulatory-timeline changes re-scored against the forecast model.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are run simultaneously and validated through multi-level data triangulation across service type, end-user industry, delivery model, focus area and region.
Bottom-up market sizing uses four quantitative anchors: number of in-scope disclosing entities by jurisdiction, average annual advisory spend per filer, estimated practice-level revenue for listed and private consultancies, and regulatory phase-in cohort volumes.
Scenario-weighted adoption curves are applied for disclosure regulation, net-zero validation and digital delivery penetration through 2035.
Driver and restraint coefficients are quantified as percentage-point impacts on CAGR and stress-tested against regional regulatory timelines.
Segment shares are cross-validated against buyer-reported budget allocation from our annual ESG spend survey.
Data Accuracy & Quality Check
The methodology guarantees an estimated data accuracy level of 85–90%.
Multi-stage validation includes analyst peer review, sense-checking against official statistical series, and reconciliation with disclosed consultancy revenues.
Outlier and low-confidence estimates are flagged and excluded from weighted averages.
Forecast confidence bands widen beyond 2030 to reflect regulatory-scope uncertainty, particularly around the European Omnibus proposal and US federal policy direction.
All estimates are presented as our own proprietary first-party analysis derived from primary interviews and official benchmarks.