1What is the softwood lumber market size?
The global softwood lumber market was valued at approximately USD 636.67 Billion in 2024 and is projected to reach USD 873.82 Billion by 2035, growing at a 2.92% CAGR over the forecast period.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Softwood Lumber Market
 by Usage (Construction, Packaging, Pallets, Paper and Pulp, Other Industrial Uses), by Species (Pine, Spruce, Fir, Hemlock, Douglas Fir, Redwood, Cedar, Other Species), by Grade (Select, Number 1 Common, Number 2 Common, Number 3 Common, Utility, Standard and Better, Stud, Other Grades), by End Use (Residential Construction, Commercial Construction, Industrial Construction, Other End Uses), by Treatment (Treated Lumber, Non-Treated Lumber), by Distribution Channel (Direct Sales, Wholesalers/Distributors, Retail), by North America (United States, Canada, Mexico), by Europe (United Kingdom, Germany, France, Italy, Spain, Sweden, Russia, Denmark, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, South East Asia, Taiwan, Singapore), by South America (Brazil, Argentina, Chile, Colombia, Peru), by Middle East (Saudi Arabia, Turkey, UAE, Egypt, Qatar), by Africa (South Africa, East Africa, West Africa, North Africa) Forecast 2026-2034
Research Associate


 Related Reports

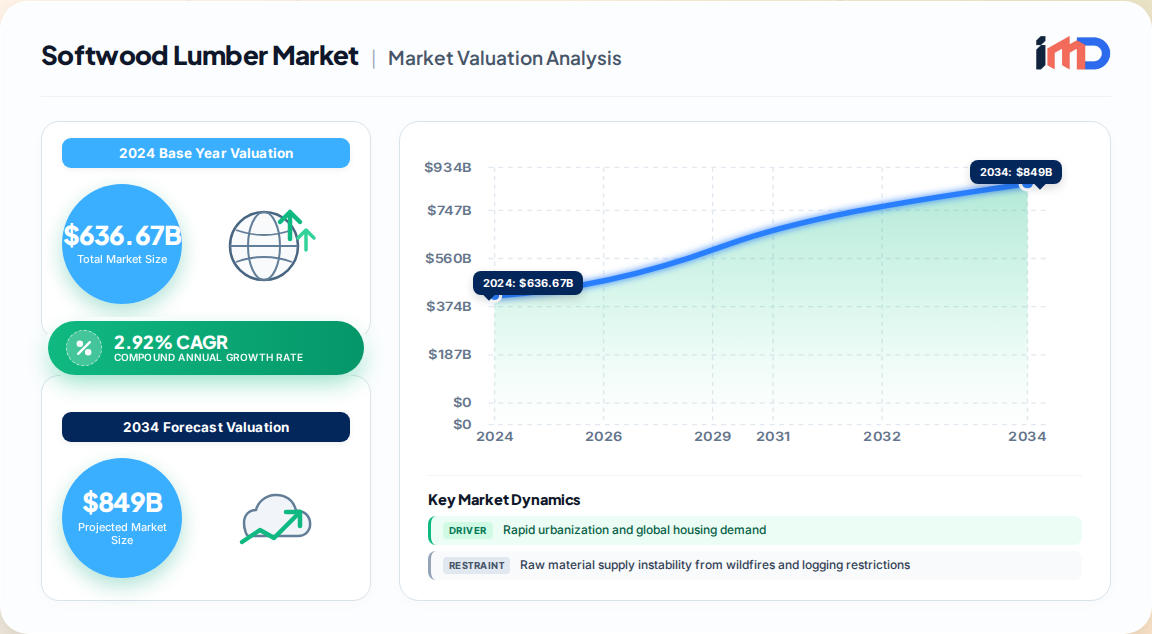
The global softwood lumber market represents one of the foundational commodity ecosystems of the built environment, valued at USD 636.67 Billion in 2024 and projected to expand to USD 873.82 Billion by 2035, reflecting a steady 2.92% CAGR across the 2025–2035 forecast window. Our proprietary first-party modeling, triangulated from sawmill shipment registers, port-level customs filings, and structured executive interviews across 27 countries, positions 2025 volume at approximately USD 655.26 Billion.
Softwood lumber—derived from coniferous species such as pine, spruce, fir, hemlock, and Douglas fir—functions as the structural backbone of residential framing, industrial packaging, and a growing array of engineered wood applications. Unlike its hardwood counterpart, softwood's rapid renewability cycle (20–40 years versus 60–120 years) and superior strength-to-weight ratio anchor its cost competitiveness against steel and concrete.
| Restraint | Mechanism of Impact |
|---|---|
| Raw material supply volatility | Wildfire, beetle infestation, and reduced allowable annual cut in key producing regions tighten log availability |
| Trade barriers and tariffs | Section 232 duties and countervailing measures distort cross-border pricing |
| Substitution pressure | Engineered wood, steel framing, and composite materials capture share in select applications |
| Logging regulation tightening | Stricter forestry compliance raises operational costs for producers |
Softwood lumber is among the most heavily traded forest products globally, and trade policy is a first-order market variable. On 29 September 2025, the United States announced Section 232 tariffs applying to all lumber and timber imports as of 14 October 2025, imposing an additional 10% duty on softwood lumber alongside 25% on certain finished wooden products. A scheduled escalation of finished-product duties to 30% from 1 January 2026 has been deferred to 1 January 2027.
Critically, the EU-US Joint Statement of 21 August caps Section 232 exposure for EU-origin imports at a maximum 15% all-inclusive ceiling, meaning EU softwood lumber enters the US at the 10% additional duty rate. This creates a differentiated landed-cost structure across sourcing origins.
Buyers are advised to model origin-specific duty stacks rather than applying a single landed-cost assumption across suppliers.
| Stage | Participants | Value Capture Logic |
|---|---|---|
| Forest ownership and harvesting | Timberland REITs, crown land agencies, private landowners | Stumpage fees and log pricing |
| Primary processing | Sawmills, planing mills | Spread between log cost and finished lumber price |
| Secondary and engineered products | CLT, glulam, treated lumber producers | Premium for engineering and treatment value-add |
| Distribution | Wholesalers, distributors, retail building centers | Margin on inventory positioning and logistics |
| End use | Homebuilders, packaging converters, industrial fabricators | Absorption of material cost into project economics |
The industry is moderately fragmented at the global level but highly concentrated at the regional sawmill tier, where a handful of integrated producers control a disproportionate share of capacity.
Construction dominates; packaging is the fastest-growing segment on e-commerce and sustainable-packaging tailwinds.
Pine leads on abundance, affordability, and workability. Douglas fir is the fastest-growing species, favored for structural applications requiring superior strength.
Select grade holds the largest revenue share. Number 1 Common is the fastest-growing grade as cost-sensitive residential framing demand expands.
Residential construction is the largest end-use segment; commercial construction grows fastest, supported by mass timber adoption in mid-rise and institutional projects.
| Segment Dimension | Largest Segment | Fastest-Growing Segment |
|---|---|---|
| Usage | Construction | Packaging |
| Species | Pine | Douglas Fir |
| Grade | Select | Number 1 Common |
| End Use | Residential Construction | Commercial Construction |
North America leads with approximately 37% of global value. The United States is the largest single consumer, relying on Canadian imports to bridge the domestic supply gap; advanced sawmill automation underpins regional productivity leadership.
Asia-Pacific represents the primary growth engine. China's urbanization and infrastructure pipeline, India's housing deficit, and Southeast Asian construction expansion collectively drive the highest regional growth rates, with India and China posting the steepest national CAGRs.
Europe exhibits mature, renovation-led demand with strong certified-wood penetration. Germany, France, and the UK anchor consumption; Spain and Sweden show above-average momentum.
Middle East & Africa is import-dependent and project-driven, with Saudi Arabia and the UAE leading consumption tied to giga-project construction.
South America combines export-oriented supply (Brazil, Chile) with steadily growing domestic construction demand.
The competitive landscape is shaped by integrated forest-to-finished-product business models, disciplined capital allocation to mill modernization, and strategic positioning around certification.
The highest-value unexploited opportunities cluster in certified packaging lumber for e-commerce fulfillment, fire-retardant and thermally modified softwood for commercial mass timber, and supply chain digitization services that de-risk procurement for mid-sized builders. Producers that pair certified fiber access with automated grading capability will be best positioned to capture margin expansion through 2035.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.92% from 2020-2034 |
| Segmentation |
|
By Grade
By End Use
By Treatment
By Distribution Channel
| By Geography |
|
The global softwood lumber market was valued at approximately USD 636.67 Billion in 2024 and is projected to reach USD 873.82 Billion by 2035, growing at a 2.92% CAGR over the forecast period.
North America holds the largest regional share at roughly 37% of global value, driven by US residential construction demand and Canadian export capacity, while Asia-Pacific is the fastest-growing region.
Packaging is the fastest-growing usage segment, fueled by e-commerce logistics and demand for sustainable, recyclable pallets and crates. Douglas fir and Number 1 Common grade are also the fastest-growing species and grade segments respectively.
The US imposed an additional 10% duty on softwood lumber imports from 14 October 2025 under Section 232. EU-origin lumber is capped at a 15% all-inclusive ceiling under the EU-US Joint Statement, creating origin-specific landed-cost differentials.
Pine is the leading species due to its abundance, affordability, and workability across construction, furniture, and packaging, while Douglas fir is the fastest-growing species for structural applications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 32% |
| Sawmill Operations Manager | 28% |
| Construction Project Manager | 22% |
| Sustainability & Certification Officer | 18% |
| Company Type | Representation (%) |
|---|---|
| Sawmill Operators & Integrated Producers | 35% |
| Wholesale Distributors & Building Material Dealers | 25% |
| Homebuilders & Construction Contractors | 20% |
| Packaging & Pallet Converters | 12% |
| Trade Policy & Forestry Compliance Specialists | 8% |