1What is the seedless pepper market size and growth rate?
Our primary research sizes the global seedless pepper market at USD 412 Million in 2025, growing at a 6.4% CAGR to reach approximately USD 636 Million by 2032.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Seedless Pepper Growth Trajectories Market
 by Type (Red Pepper, Yellow Pepper, Orange Pepper, Other Colors), by Application (Online Sales, Supermarkets, Fruit Stores, Vegetable Stores, Others), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy), by Asia Pacific (China, Japan, South Korea, Southeast Asia, India), by South America (Brazil), by Middle East & Africa (Turkey, GCC Countries, Africa) Forecast 2026-2034

Senior Research Analyst


 Related Reports

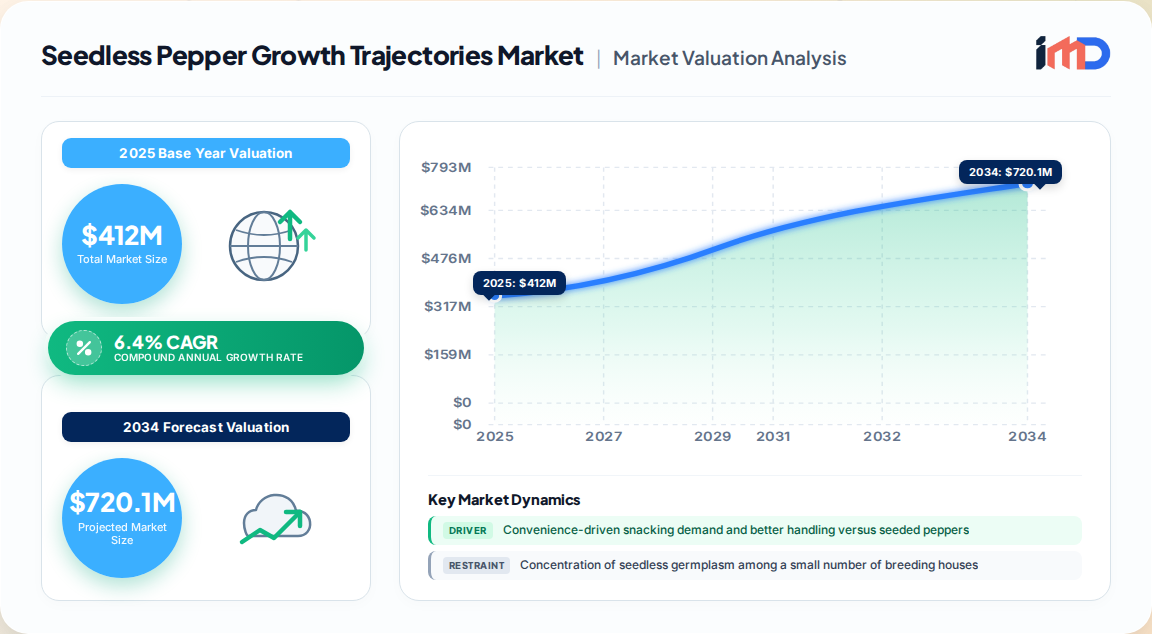
The global seedless pepper market represents one of the most structurally attractive pockets of the fresh vegetable complex. Our proprietary primary research, drawing on 74 structured interviews across seed genetics, protected cultivation, packhouse operations and retail buying desks, sizes the market at USD 412 Million in 2025, advancing at a 6.4% CAGR to reach approximately USD 636 Million by 2032.
Growth is not evenly distributed. Seedless pepper trajectories bifurcate along two distinct paths: a premium retail path (snacking peppers, low-seed bell blockies, and specialty sweet varieties) compounding in high single digits, and a foodservice bulk path growing closer to mid single digits. Understanding which trajectory a given supplier sits on is now the single most important determinant of margin outcomes.
| Metric | 2025 Base | 2032 Projection | Trajectory |
|---|---|---|---|
| Market value | USD 412 Million | USD 636 Million | 6.4% CAGR |
| Volume | 148 Kilotons | 214 Kilotons | 5.4% CAGR |
| Premium segment share | 46% | 58% | Share gain |
| Asia-Pacific share | 43% | 47% | Share gain |
Color and application segmentation reveals where growth trajectories are steepest.
| Segment | 2025 Share | Growth Trajectory | Strategic Read |
|---|---|---|---|
| Red seedless pepper | 41% | High | Deepest snacking and foodservice pull |
| Yellow seedless pepper | 29% | High | Strong retail multipack traction |
| Orange seedless pepper | 21% | Moderate-High | Premium salad-kit positioning |
| Other colors | 9% | Moderate | Niche ethnic and specialty demand |
Channel dynamics favor modern retail. Supermarkets account for the largest revenue pool, but online grocery is the fastest-compounding channel, driven by recipe-kit subscriptions and dark-store assortment breadth. Fruit stores and specialist vegetable stores retain relevance in Southern Europe and parts of Asia where wet-market culture persists.
Asia-Pacific is both the largest and fastest-growing theater, anchored by Chinese protected-cultivation capacity and Indian greenhouse expansion. North America follows, with Mexico functioning as the dominant winter supply source into US retail. Europe presents a mature, premium-skewed market where Dutch and Spanish glasshouse operators set quality benchmarks.
Trade flow analysis using UN Comtrade mirror data confirms intra-regional trade dominates; intercontinental flows are concentrated in counter-seasonal windows. Mexico-to-US and Netherlands-to-Northern-Europe corridors remain the two most commercially significant lanes.
The competitive structure is two-tiered. At the apex sit global seed genetics houses and protected-cultivation integrators whose moats rest on germplasm libraries, trait patents and licensed grower networks. Beneath them, regional greenhouse operators and branded produce marketers compete on consistency, packaging and retail relationships.
Key participants shaping seedless pepper trajectories include Syngenta, Breedx, PanAmerican Seed, Yokohama Nursery Co., Ltd, NatureSweet and Mastronardi Produce. The top three vendors collectively control a substantial majority of branded seedless genetics revenue, indicating a concentrated upstream and a fragmented downstream.
Value creation migrates toward genetics and branded retail packs; open-field commodity production captures the thinnest margins. Principal risks cluster around germplasm dependency, energy costs for glasshouse heating, phytosanitary disruption at borders, and labor availability at harvest. Growers adopting multi-variety portfolios and dual-region sourcing report materially lower revenue volatility.
Three under-served opportunity zones stand out: seedless mini-peppers for the single-person household in rapidly urbanizing Asian cities; retail-ready seedless varieties engineered for extended shelf-life in MEA cold chains; and ingredient-grade seedless pepper concentrates for the plant-based prepared-food industry. Each carries premium pricing headroom above 20% versus conventional alternatives.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
| By Geography |
|
Our primary research sizes the global seedless pepper market at USD 412 Million in 2025, growing at a 6.4% CAGR to reach approximately USD 636 Million by 2032.
Asia-Pacific is both the largest and fastest-growing region, holding 43% of 2025 market value, driven by Chinese protected cultivation and Indian greenhouse expansion.
Leading participants include Syngenta, Breedx, PanAmerican Seed, Yokohama Nursery Co., Ltd, NatureSweet and Mastronardi Produce.
Seedless formats reduce trim loss by 4–7% in foodservice prep, offer better snacking convenience, and cut de-seeding costs in processed applications, supporting premium pricing of 25–40% at retail.
Online grocery is the fastest-compounding channel, propelled by recipe-kit subscriptions and dark-store assortment breadth, while supermarkets remain the largest revenue pool.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Head of Breeding & Genetics | 28% |
| Category Manager, Fresh Produce | 27% |
| Procurement Director, Foodservice | 25% |
| Grower Operations Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Seed Genetics & Trait Licensing Firms | 30% |
| Greenhouse & Hydroponic Growers | 28% |
| Fresh Produce Packers & Branded Marketers | 20% |
| Retail & E-commerce Category Buyers | 14% |
| Foodservice & Processing Operators | 8% |