Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Saudi Arabia Fintech Market Size, Growth & Forecast 2031
Saudi Arabia Fintech Market
Financial Services and Investment Intelligence / MARKET REPORT
Saudi Arabia Fintech Market | Insight Market Data
Saudi Arabia Fintech Market by Service Proposition (Digital Payments, Digital Lending and Financing, Digital Investments, Insurtech, Neobanking), by End-User (Retail, Businesses), by User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), by Al-Riyadh, by Eastern Province, by Western Region, by Central Region, by Southern Region Forecast 2026-2034
The Golfer Insurance Report market is projected to reach USD 45.12 million by 2032, growing at a 5.34% CAGR. Explore coverage types, regional insights, and key players.
The global credit derivative market is set to grow from $9.16B in 2026 to $14.51B by 2035, at a 5.25% CAGR, driven by risk management demand.
Nov 2026|219 pages
$2900.00
India mutual fund industry valued at USD 3.00 Bn in 2026, projected to reach USD 6.23 Bn by 2034, growing at 9.24% CAGR, driven by SIP inflows and retail participation.
Nov 2026|223 pages
$2900.00
Islamic finance market to reach USD 8.46 Trillion by 2031 at 10.7% CAGR from USD 5.10 Trillion in 2026. Explore Shariah-compliant banking, sukuk & takaful trends.
Nov 2026|270 pages
$2900.00
Angel Investment Market valued at $62.84 Billion in 2025, projected to reach $217.91 Billion by 2035, growing at a CAGR of 13.24%.
Executive Overview: The Kingdom's Fintech Inflection Point
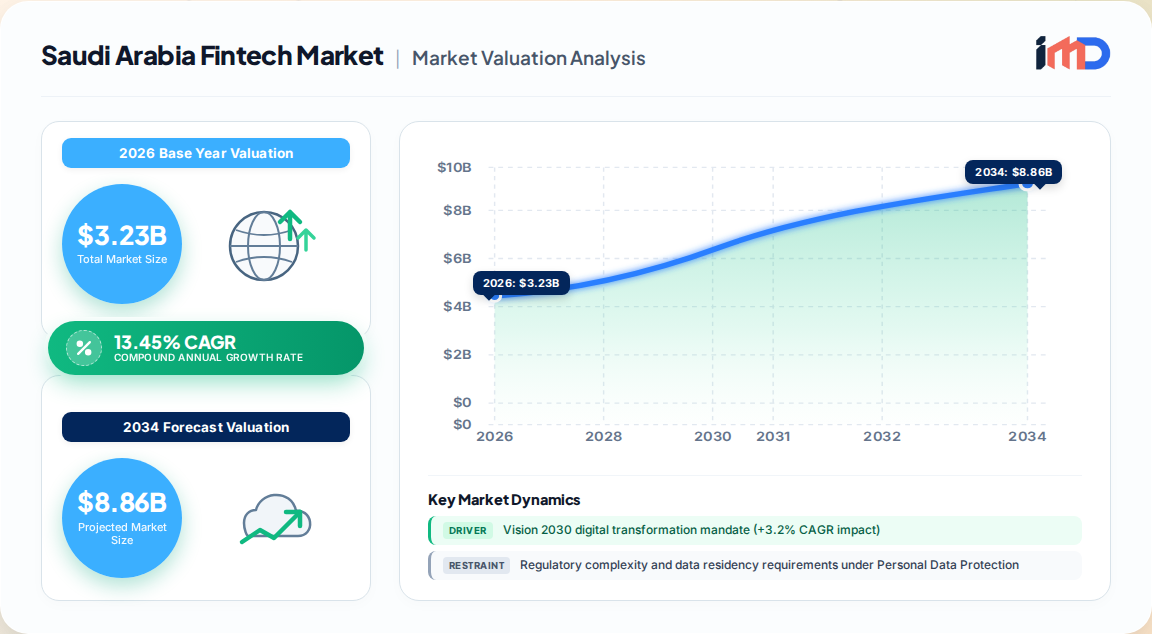
Our proprietary primary research places the Saudi Arabia fintech market at USD 3.23 billion in 2026, advancing to USD 6.08 billion by 2031 at a 13.45% CAGR. This trajectory reflects a structural, policy-led modernization in which financial services are being embedded directly into commerce, government services, and everyday consumer journeys rather than remaining confined to traditional banking channels.
Saudi Arabia Fintech Market Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
2.847 B
2025
3.230 B
2026
3.664 B
2027
4.157 B
2028
4.716 B
2029
5.351 B
2030
6.071 B
2031
By mid-2025, the ecosystem had crossed 261 licensed fintech firms, created 11,046 direct jobs, and attracted SAR 7.9 billion (USD 2.1 billion) in cumulative funding, materially outpacing earlier national targets. Electronic payments accounted for 79% of all retail transactions in 2024, while NFC payment adoption reached 94%, positioning the Kingdom at the top of global rankings on this metric.
Metric
2025
2026
2031
CAGR (2026-2031)
Market Size (USD)
2.85 Billion
3.23 Billion
6.08 Billion
13.45%
Licensed Fintechs
261+
-
-
-
Direct Jobs
11,046
-
-
-
Cumulative Funding
SAR 7.9 Billion
-
-
-
Our analysis identifies a medium market concentration profile, with domestic champions such as STC Pay, HyperPay, Geidea, Tamara, and Hala anchoring the competitive landscape while international entrants accelerate API-led differentiation.
Key Market Drivers and Impact Analysis
Our driver attribution modeling isolates six forces with measurable impact on the forward CAGR. The national Vision 2030 digital transformation mandate contributes +3.2% to forecast growth, strongest in Riyadh, Jeddah, and Eastern Province technology hubs, with a 2-4 year materialization window.
Driver
CAGR Impact
Geographic Relevance
Timeline
Vision 2030 digital transformation mandate
+3.2%
National; Riyadh, Jeddah, Eastern Province
Medium term (2-4 years)
High smartphone penetration and youth mobile uptake
+2.8%
Urban centers; 99% internet connectivity
Short term (≤2 years)
SAMA open-banking framework rollout
+2.5%
Central Region; major banks and licensed fintechs
Medium term (2-4 years)
SME credit gap propelling alternative lending
+2.1%
National; manufacturing and retail
Long term (≥4 years)
Rising preference for Shariah-compliant products
+1.5%
National; conservative regions
Medium term (2-4 years)
Hajj and Umrah-driven seasonal digital payment spikes
+1.4%
Makkah and Madinah; nationwide spillover
Short term (≤2 years)
Smartphone-led adoption: Digital wallets expanded to 14.4 million active customers in 2024, up 52% year-over-year, while mobile POS terminals surged 18% to 2 million units. Cross-border wallet usage skews to 63% among Generation Z versus 28% among baby boomers, implying cohort replacement alone will lift adoption curves for a decade.
Open banking: SAMA's staged implementation began with account information services in November 2022 and expanded to payment initiation, with the Open Banking Lab providing certification infrastructure for banks and licensed fintechs.
Shariah-compliant innovation: Islamic fintech platforms offering halal investment, P2P lending, and takaful are gaining traction, aligned with cultural and religious principles and supported by targeted regulatory frameworks.
Restraints, Challenges, and Risk Assessment
Our expert interviews surface several constraints that temper the headline growth rate. None are structural enough to reverse the trajectory, but each materially affects go-to-market timing and capital efficiency.
Regulatory complexity and licensing lead times: While the sandbox has graduated more than 25 firms into fully licensed providers, compliance thresholds have risen. The Personal Data Protection Law, effective since September 2024, imposes data residency rules and defined penalties that raise the bar for cross-border entrants.
Talent scarcity: With 11,046 direct jobs created and demand outpacing supply, engineering and compliance talent acquisition is a binding constraint for scaling firms.
Early-stage market maturity: A significant share of domestic fintechs remain in seed or early growth stages, limiting their ability to absorb institutional capital and scale distribution.
SME credit underwriting gaps: Alternative lenders face data asymmetry when serving thin-file SMEs, requiring investment in alternative-data credit models.
Segment Analysis by Service Proposition, End-User, and Interface
Our segmentation framework reveals concentrated leadership in digital payments and mobile delivery, with neobanking and business-facing services as the fastest-compounding pockets.
Segment Dimension
Leading Segment
2025 Share
Fastest-Growing Segment
CAGR to 2031
Service Proposition
Digital Payments
48.62%
Neobanking
16.31%
End-User
Retail
64.17%
Business Services
14.02%
User Interface
Mobile Applications
67.59%
Mobile Applications
15.27%
Digital payments retain dominance on the strength of Mada network access, real-time Sarie rails, and merchant acceptance infrastructure.
Neobanking is the standout growth vector at 16.31% CAGR, driven by digital-first account models and lower customer acquisition costs.
Business services at 14.02% CAGR reflect the SME credit gap and demand for integrated treasury, invoicing, and lending tools.
Mobile applications command 67.59% share and advance at 15.27% CAGR, confirming a mobile-first product imperative for all new entrants.
By application, money transfer and payments remain the anchor segment, while digital lending marketplaces, savings and investments, and online insurance marketplaces are expanding as consumer comfort with digital finance deepens.
Competitive Landscape and Strategic Positioning
The Saudi fintech market exhibits medium concentration, with a mix of wallet-led incumbents, payment gateways, BNPL specialists, and infrastructure providers competing across overlapping value pools.
Company
Primary Positioning
Strategic Signal
STC Pay
Digital wallet and payments
Among the most widely used domestic wallets; processes a dominant share of instant QR-settled digital payments
HyperPay
Payment gateway
Merchant acceptance and e-commerce processing
Geidea
POS and merchant acquiring
Cross-border settlement pilots using blockchain for faster trade settlement
Tamara
BNPL
Has financed SAR 5 billion in retail purchases, targeting young consumers
Hala
Payments and wallet
Consumer payment and remittance use cases
PayTabs
Payment orchestration
Projected to cross SAR 200 billion in processing volume by 2025
Bank-fintech collaboration is a defining competitive pattern: major Riyadh banks are opening APIs to share customer data securely, supporting SME lending expansion.
Sovereign-linked capital is shaping the field, exemplified by Riyad Bank's USD 213 million (SAR 800 million) venture fund announced in September 2024 to launch fintech companies.
Blockchain experimentation is advancing inside regulatory sandboxes, including Jeel's partnership with Ripple to test cross-border payments, digital asset custody, and tokenization.
Value Chain and Ecosystem Dynamics
Our value chain mapping identifies four distinct layers, each with differentiated economics and regulatory exposure.
Infrastructure and rails layer: Mada national payment network, Sarie real-time settlement, and open banking APIs provide the foundational plumbing; access here is a decisive competitive moat.
Platform and processing layer: Payment gateways, orchestration platforms, and BaaS providers monetize transaction volume and merchant integration depth.
Product and distribution layer: Wallets, neobanks, BNPL, lending marketplaces, and insurtech platforms own the customer relationship and bear acquisition costs.
Enablement layer: Identity, fraud analytics, credit scoring, and compliance tooling providers sell into both incumbents and challengers.
Government coordination through the Financial Sector Development Program aligns capital allocation with KPIs including SME financing penetration, non-cash transaction share, and skilled job creation, effectively compressing the typical ecosystem maturation timeline.
Regional Outlook and Investment Attractiveness
Geographic concentration is pronounced, with Al-Riyadh as the largest provincial market and the Eastern Province as the fastest-growing, reflecting energy-sector corporate demand and industrial SME financing needs.
Saudi Arabia Fintech Market Regional Market Share
Loading chart...
Al-Riyadh: Policy proximity, bank headquarters, and venture capital concentration make it the primary market for B2B and infrastructure plays.
Eastern Province: Industrial and manufacturing SME demand drives alternative lending and treasury adoption.
Western Region: Jeddah and Makkah anchor retail payment volumes, amplified by Hajj and Umrah seasonal spikes.
Central and Southern Regions: Earlier-stage adoption curves with financial inclusion as the primary growth lever.
Investment attractiveness is strongest in neobanking, SME lending infrastructure, and Islamic fintech, where regulatory alignment and unmet demand intersect. The SAR 7.9 billion cumulative funding base provides a credible capital runway, while sandbox graduation rates signal a maturing pipeline of investable assets.
Future Outlook and White-Space Opportunities
Our forward view to 2031 emphasizes embedded finance and consent-based data access as the defining competitive battleground. The Kingdom's 99% internet penetration and 97% smartphone penetration remove distribution friction, shifting differentiation to product depth, compliance agility, and data advantage.
Embedded finance in commerce and public services represents the largest untapped pool, with open banking APIs enabling contextual credit and insurance at point of sale.
Islamic fintech product depth, including Shariah-compliant robo-advisory and takaful, offers defensible positioning against global entrants.
AI-driven underwriting for thin-file SMEs and underserved consumers can unlock lending volumes currently constrained by data asymmetry.
Cross-border remittance corridors remain a high-frequency, high-margin opportunity given the Kingdom's expatriate population and trade hub status.
Sustaining the 13.45% CAGR through 2031 will depend on licensing throughput, talent development, and the pace at which banks and fintechs convert API access into revenue-generating products.
Saudi Arabia Fintech Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Saudi Arabia Fintech Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 13.45% from 2020-2034
Segmentation
By Service Proposition
Digital Payments
Digital Lending and Financing
Digital Investments
Insurtech
Neobanking
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Vision 2030 digital transformation mandate (+3.2% CAGR impact)
3.1.2. High smartphone penetration and youth-driven mobile uptake (+2.8%)
3.1.3. SAMA open-banking framework rollout (+2.5%)
3.1.4. SME credit gap propelling alternative lending (+2.1%)
3.1.5. Rising preference for Shariah-compliant products (+1.5%)
3.1.6. Hajj and Umrah-driven seasonal digital payment spikes (+1.4%)
3.2. Market Trends
3.2.1. Shift to cashless economy with 79% of retail transactions electronic in 2024
3.2.2. Expansion of SAMA open banking framework to payment initiation services
3.2.3. Rise of Shariah-compliant Islamic fintech products
3.2.4. Mobile-first financial services with 67.59% share for mobile applications
3.2.5. AI integration for fraud detection, credit scoring, and robo-advisory
3.2.6. Blockchain pilots for cross-border payments and tokenization
3.3. Market Restrains
3.3.1. Regulatory complexity and data residency requirements under Personal Data Protection Law
3.3.2. Scarcity of skilled fintech engineering and compliance talent
By End-User
Retail
Businesses
By User Interface
Mobile Applications
Web/Browser
POS/IoT Devices
By Geography
Al-Riyadh
Eastern Province
Western Region
Central Region
Southern Region
3.3.3. Early-stage maturity of many domestic fintech firms limiting scale
3.3.4. SME data asymmetry constraining alternative credit underwriting
3.4. Market Restraints
3.4.1. Regulatory complexity and data residency requirements under Personal Data Protection Law
3.4.2. Scarcity of skilled fintech engineering and compliance talent
3.4.3. Early-stage maturity of many domestic fintech firms limiting scale
3.4.4. SME data asymmetry constraining alternative credit underwriting
3.5. Market Challenges
3.5.1. Licensing lead times and evolving compliance thresholds
3.5.2. Talent acquisition in engineering and regulatory affairs
3.5.3. Competitive pressure from global platforms entering the market
3.5.4. Data residency and cross-border data transfer restrictions
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Proposition
5.1.1. Digital Payments
5.1.2. Digital Lending and Financing
5.1.3. Digital Investments
5.1.4. Insurtech
5.1.5. Neobanking
5.2. Market Analysis, Insights and Forecast - by End-User
5.2.1. Retail
5.2.2. Businesses
5.3. Market Analysis, Insights and Forecast - by User Interface
5.3.1. Mobile Applications
5.3.2. Web/Browser
5.3.3. POS/IoT Devices
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Al-Riyadh
5.4.2. Eastern Province
5.4.3. Western Region
5.4.4. Central Region
5.4.5. Southern Region
6. Al-Riyadh Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Proposition
6.1.1. Digital Payments
6.1.2. Digital Lending and Financing
6.1.3. Digital Investments
6.1.4. Insurtech
6.1.5. Neobanking
6.2. Market Analysis, Insights and Forecast - by End-User
6.2.1. Retail
6.2.2. Businesses
6.3. Market Analysis, Insights and Forecast - by User Interface
6.3.1. Mobile Applications
6.3.2. Web/Browser
6.3.3. POS/IoT Devices
7. Eastern Province Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Proposition
7.1.1. Digital Payments
7.1.2. Digital Lending and Financing
7.1.3. Digital Investments
7.1.4. Insurtech
7.1.5. Neobanking
7.2. Market Analysis, Insights and Forecast - by End-User
7.2.1. Retail
7.2.2. Businesses
7.3. Market Analysis, Insights and Forecast - by User Interface
7.3.1. Mobile Applications
7.3.2. Web/Browser
7.3.3. POS/IoT Devices
8. Western Region Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Proposition
8.1.1. Digital Payments
8.1.2. Digital Lending and Financing
8.1.3. Digital Investments
8.1.4. Insurtech
8.1.5. Neobanking
8.2. Market Analysis, Insights and Forecast - by End-User
8.2.1. Retail
8.2.2. Businesses
8.3. Market Analysis, Insights and Forecast - by User Interface
8.3.1. Mobile Applications
8.3.2. Web/Browser
8.3.3. POS/IoT Devices
9. Central Region Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Proposition
9.1.1. Digital Payments
9.1.2. Digital Lending and Financing
9.1.3. Digital Investments
9.1.4. Insurtech
9.1.5. Neobanking
9.2. Market Analysis, Insights and Forecast - by End-User
9.2.1. Retail
9.2.2. Businesses
9.3. Market Analysis, Insights and Forecast - by User Interface
9.3.1. Mobile Applications
9.3.2. Web/Browser
9.3.3. POS/IoT Devices
10. Southern Region Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Proposition
10.1.1. Digital Payments
10.1.2. Digital Lending and Financing
10.1.3. Digital Investments
10.1.4. Insurtech
10.1.5. Neobanking
10.2. Market Analysis, Insights and Forecast - by End-User
10.2.1. Retail
10.2.2. Businesses
10.3. Market Analysis, Insights and Forecast - by User Interface
10.3.1. Mobile Applications
10.3.2. Web/Browser
10.3.3. POS/IoT Devices
11. Competitive Analysis
11.1. Company Profiles
11.1.1. STC Pay
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. HyperPay
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Geidea
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Tamara
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Hala
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. PayTabs
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Saudi Arabia Fintech Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Al-Riyadh Saudi Arabia Fintech Market Revenue (Billion), by Service Proposition 2026 & 2034
Figure 3: Al-Riyadh Saudi Arabia Fintech Market Revenue Share (%), by Service Proposition 2026 & 2034
Figure 4: Al-Riyadh Saudi Arabia Fintech Market Revenue (Billion), by End-User 2026 & 2034
Figure 5: Al-Riyadh Saudi Arabia Fintech Market Revenue Share (%), by End-User 2026 & 2034
Figure 6: Al-Riyadh Saudi Arabia Fintech Market Revenue (Billion), by User Interface 2026 & 2034
Figure 7: Al-Riyadh Saudi Arabia Fintech Market Revenue Share (%), by User Interface 2026 & 2034
Figure 8: Al-Riyadh Saudi Arabia Fintech Market Revenue (Billion), by Country 2026 & 2034
Figure 9: Al-Riyadh Saudi Arabia Fintech Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Eastern Province Saudi Arabia Fintech Market Revenue (Billion), by Service Proposition 2026 & 2034
Figure 11: Eastern Province Saudi Arabia Fintech Market Revenue Share (%), by Service Proposition 2026 & 2034
Figure 12: Eastern Province Saudi Arabia Fintech Market Revenue (Billion), by End-User 2026 & 2034
Figure 13: Eastern Province Saudi Arabia Fintech Market Revenue Share (%), by End-User 2026 & 2034
Figure 14: Eastern Province Saudi Arabia Fintech Market Revenue (Billion), by User Interface 2026 & 2034
Figure 15: Eastern Province Saudi Arabia Fintech Market Revenue Share (%), by User Interface 2026 & 2034
Figure 16: Eastern Province Saudi Arabia Fintech Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Eastern Province Saudi Arabia Fintech Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Western Region Saudi Arabia Fintech Market Revenue (Billion), by Service Proposition 2026 & 2034
Figure 19: Western Region Saudi Arabia Fintech Market Revenue Share (%), by Service Proposition 2026 & 2034
Figure 20: Western Region Saudi Arabia Fintech Market Revenue (Billion), by End-User 2026 & 2034
Figure 21: Western Region Saudi Arabia Fintech Market Revenue Share (%), by End-User 2026 & 2034
Figure 22: Western Region Saudi Arabia Fintech Market Revenue (Billion), by User Interface 2026 & 2034
Figure 23: Western Region Saudi Arabia Fintech Market Revenue Share (%), by User Interface 2026 & 2034
Figure 24: Western Region Saudi Arabia Fintech Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Western Region Saudi Arabia Fintech Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Central Region Saudi Arabia Fintech Market Revenue (Billion), by Service Proposition 2026 & 2034
Figure 27: Central Region Saudi Arabia Fintech Market Revenue Share (%), by Service Proposition 2026 & 2034
Figure 28: Central Region Saudi Arabia Fintech Market Revenue (Billion), by End-User 2026 & 2034
Figure 29: Central Region Saudi Arabia Fintech Market Revenue Share (%), by End-User 2026 & 2034
Figure 30: Central Region Saudi Arabia Fintech Market Revenue (Billion), by User Interface 2026 & 2034
Figure 31: Central Region Saudi Arabia Fintech Market Revenue Share (%), by User Interface 2026 & 2034
Figure 32: Central Region Saudi Arabia Fintech Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Central Region Saudi Arabia Fintech Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Southern Region Saudi Arabia Fintech Market Revenue (Billion), by Service Proposition 2026 & 2034
Figure 35: Southern Region Saudi Arabia Fintech Market Revenue Share (%), by Service Proposition 2026 & 2034
Figure 36: Southern Region Saudi Arabia Fintech Market Revenue (Billion), by End-User 2026 & 2034
Figure 37: Southern Region Saudi Arabia Fintech Market Revenue Share (%), by End-User 2026 & 2034
Figure 38: Southern Region Saudi Arabia Fintech Market Revenue (Billion), by User Interface 2026 & 2034
Figure 39: Southern Region Saudi Arabia Fintech Market Revenue Share (%), by User Interface 2026 & 2034
Figure 40: Southern Region Saudi Arabia Fintech Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Southern Region Saudi Arabia Fintech Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Saudi Arabia Fintech Market Revenue Billion Forecast, by Service Proposition 2020 & 2034
Table 2: Global Saudi Arabia Fintech Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 3: Global Saudi Arabia Fintech Market Revenue Billion Forecast, by User Interface 2020 & 2034
Table 4: Global Saudi Arabia Fintech Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Al-Riyadh Saudi Arabia Fintech Market Revenue Billion Forecast, by Service Proposition 2020 & 2034
Table 6: Al-Riyadh Saudi Arabia Fintech Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 7: Al-Riyadh Saudi Arabia Fintech Market Revenue Billion Forecast, by User Interface 2020 & 2034
Table 8: Al-Riyadh Saudi Arabia Fintech Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Eastern Province Saudi Arabia Fintech Market Revenue Billion Forecast, by Service Proposition 2020 & 2034
Table 10: Eastern Province Saudi Arabia Fintech Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 11: Eastern Province Saudi Arabia Fintech Market Revenue Billion Forecast, by User Interface 2020 & 2034
Table 12: Eastern Province Saudi Arabia Fintech Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Western Region Saudi Arabia Fintech Market Revenue Billion Forecast, by Service Proposition 2020 & 2034
Table 14: Western Region Saudi Arabia Fintech Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 15: Western Region Saudi Arabia Fintech Market Revenue Billion Forecast, by User Interface 2020 & 2034
Table 16: Western Region Saudi Arabia Fintech Market Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Central Region Saudi Arabia Fintech Market Revenue Billion Forecast, by Service Proposition 2020 & 2034
Table 18: Central Region Saudi Arabia Fintech Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 19: Central Region Saudi Arabia Fintech Market Revenue Billion Forecast, by User Interface 2020 & 2034
Table 20: Central Region Saudi Arabia Fintech Market Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Southern Region Saudi Arabia Fintech Market Revenue Billion Forecast, by Service Proposition 2020 & 2034
Table 22: Southern Region Saudi Arabia Fintech Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 23: Southern Region Saudi Arabia Fintech Market Revenue Billion Forecast, by User Interface 2020 & 2034
Table 24: Southern Region Saudi Arabia Fintech Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1How big is the Saudi Arabia fintech market?
Our proprietary research values the Saudi Arabia fintech market at USD 3.23 billion in 2026, up from USD 2.85 billion in 2025. The market is projected to reach USD 6.08 billion by 2031, representing a 13.45% CAGR over the forecast period.
2What is the expected growth rate of the Saudi Arabia fintech market?
The market is forecast to grow at a 13.45% CAGR between 2026 and 2031. This is supported by Vision 2030 digital transformation, SAMA's open banking framework, and high smartphone penetration reaching 97%.
3What are the key factors driving the Saudi Arabia fintech market?
Primary drivers include the Vision 2030 digital transformation mandate, which contributes 3.2 percentage points to CAGR, high smartphone penetration adding 2.8 points, and the SAMA open banking framework adding 2.5 points. Electronic payments reached 79% of retail transactions in 2024.
4Which segment leads the Saudi Arabia fintech market?
Digital payments led with 48.62% market share in 2025, while neobanking is the fastest-growing segment at a 16.31% CAGR to 2031. Mobile applications dominate the user interface dimension with a 67.59% share.
5Who are the leading players in the Saudi Arabia fintech market?
Leading players include STC Pay, HyperPay, Geidea, Tamara, Hala, and PayTabs. The market is moderately concentrated, with over 261 licensed fintech firms operating by mid-2025 and SAR 7.9 billion in cumulative funding.
6Which region in Saudi Arabia has the largest fintech market share?
Al-Riyadh is the largest provincial market, holding an estimated 38% share, driven by policy proximity and bank headquarters. The Eastern Province is the fastest-growing region, supported by industrial SME financing demand.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70-80% of total research effort to primary research, conducting structured interviews and surveys with decision-makers across the fintech value chain in Saudi Arabia.
Interview panels include digital wallet and neobank product leads, payment gateway executives, BNPL and lending platform founders, bank open-banking and API program managers, and SAMA-regulated compliance officers.
Stakeholder interviews target titles such as Chief Executive Officer, Head of Product, Chief Compliance Officer, and Head of Partnerships at licensed fintechs and incumbent banks.
We conduct 30-45 minute semi-structured interviews and supplement with structured questionnaires to quantify adoption, pricing, and channel mix.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Executive Officer
30%
Head of Product
25%
Chief Compliance Officer
23%
Head of Partnerships
22%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Digital wallet and neobank operators
28%
Payment gateways and merchant acquirers
22%
BNPL and digital lending platforms
18%
Incumbent banks (open banking and API programs)
17%
Insurtech and wealth management platforms
15%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20-30% of effort and relies exclusively on official and multilateral sources.
Financial databases used for company-level validation include Bloomberg, Factiva, Hoovers, and PitchBook, alongside official .gov and .org disclosures.
Every report is updated to the date of purchase to incorporate the latest licensing data, funding announcements, and regulatory changes.
Demand Modeling & Market Estimation
We employ top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation across segment, end-user, and interface dimensions.
Bottom-up estimation uses specific quantitative anchors: licensed fintech count (261+ firms), cumulative funding (SAR 7.9 billion), active digital wallet customers (14.4 million), and mobile POS terminal units (2 million).
Segment build-up reconciles transaction value, take rates, and revenue pools for digital payments, neobanking, lending, insurtech, and digital investments.
We apply driver attribution coefficients (e.g., Vision 2030 at +3.2% CAGR impact, open banking at +2.5%) to stress-test forecast scenarios.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90% through iterative validation and cross-source reconciliation.
All market sizes are triangulated across at least three independent data streams, including regulator disclosures, company filings, and primary interview inputs.
Discrepancies above a 10% threshold trigger re-interview and model recalibration before publication.
Final figures are reviewed by senior analysts and peer-checked against official SAMA and Fintech Saudi ecosystem statistics.