Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Residential EV Charging Market Size, Trends & 2032 Forecast
Residential EV Charging Market | Insight Market Data
Residential EV Charging Market by Charger Type (Level 1 (Up To 1.9 KW), Level 2, Wireless/Inductive), by Vehicle Type (Passenger Cars, Two-Wheelers and Micro-Mobility, Commercial), by Charging-Station Power Band (Low (Up To 3.7 KW), Medium, High), by Connectivity (Smart/Networked, Non-Smart), by Installation Type (Wall-Mounted, Portable Plug-In), by Purchase Channel (OEM Bundled, Specialist EV Stores and Installer Networks, Retail), by Asia-Pacific (China, Japan, India, South Korea, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands, Norway), by Middle East & Africa (UAE, Saudi Arabia, Jordan, South Africa), by South America (Brazil, Argentina, Chile) Forecast 2026-2034
Automotive chemicals market valued at $70.1 billion in 2025, growing at 5.2% CAGR to $112.1 billion by 2034, driven by EV thermal fluids and synthetic lubricants.
Kids scooter market to reach US$ 8.80 Billion by 2034 at 4.7% CAGR from US$ 5.53 Billion in 2024. Kick scooters lead with 87.4% share; Europe dominates globally.
Nov 2026|242 pages
$2900.00
The Electric Vehicle Magnets Market is valued at USD 2.74 Billion in 2025 and is projected to reach USD 11.63 Billion by 2033, growing at a CAGR of 19.8%.
Nov 2026|180 pages
$2900.00
The global automobile weather strip market is valued at $8.6 Billion in 2025, growing at a 3.5% CAGR to reach $12.1 Billion by 2035, driven by EV adoption and comfort demand.
Nov 2026|248 pages
$2900.00
The global automotive aftermarket market is valued at USD 464.83 billion in 2025, growing at a 3.64% CAGR to reach USD 555.82 billion by 2030.
Executive Overview: The Home as the Primary Charging Hub
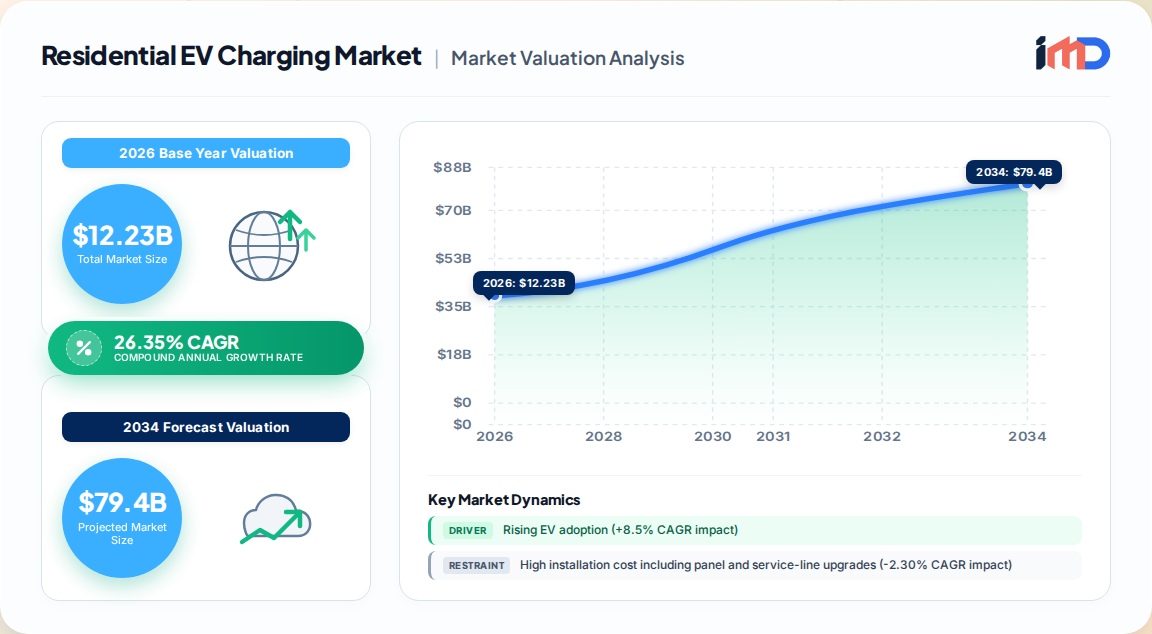
The residential EV charging market is undergoing a structural re-rating. Our proprietary primary research and expert interviews estimate the global market at USD 12.23 billion in 2026, rising to USD 15.45 billion in 2027 and projected to reach USD 49.76 billion by 2032, a CAGR of 26.35% over the 2027–2032 period. Home charging has cemented its role as the default routine refueling location: more than 43 million private charge points were in service globally at the end of 2025, and in mature markets such as the UK, over 90% of EV owners rely on home charging for regular use.
Residential EV Charging Market Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
9.679 B
2025
12.23 B
2026
15.45 B
2027
19.52 B
2028
24.67 B
2029
31.17 B
2030
39.38 B
2031
The market's center of gravity is shifting from hardware-only sales toward managed energy services. Competition now hinges on load management, solar-plus-storage integration, bidirectional (V2H/V2G) capability, and cybersecurity—not merely connector amperage.
Asia-Pacific remains the largest regional market, holding 40.01% of 2026 revenue, led by China's scale and manufacturing cost advantages.
Middle East & Africa is the fastest-growing region at a projected 27.44% CAGR, spurred by tax-exempt EV import surges in markets such as Jordan.
Smart/networked chargers already command 65.55% of revenue share, signaling that software and grid-interaction value is compounding faster than unit volume.
Key Market Drivers and Restraint Dynamics
Our demand model attributes growth to five identifiable drivers, each with a measurable impact on the forecast CAGR. Rising EV adoption is the single largest contributor at +8.5%, followed by government home-charging incentives at +6.2% and falling hardware costs at +4.8%.
Driver
Estimated CAGR Impact
Primary Geographic Relevance
Impact Timeline
Rising EV adoption
+8.5%
Global; Asia-Pacific and North America leading
Medium term (2–4 years)
Government incentives for home charging
+6.2%
North America and Europe core
Short term (up to 2 years)
Falling charger hardware costs
+4.8%
Global; Asia-Pacific manufacturing scale
Medium term (2–4 years)
Residential solar-plus-storage uptake
+3.1%
North America, Europe, Australia
Long term (4+ years)
Second-hand EV aftermarket demand
+2.4%
Global; early adoption in developed markets
Long term (4+ years)
V2H/V2G monetisation opportunities
+1.7%
North America and Europe regulatory frameworks
Long term (4+ years)
Policy is a structural tailwind. In the United States, individuals can offset 30% of qualified installation expenses, capped at USD 1,000, through 2032. California requires EV-ready circuits in every new dwelling from 2026, while the EU Energy Performance of Buildings Directive mandates charging or pre-cabling in new multi-space residential structures. The EU Alternative Fuels Infrastructure Regulation's 60 km public charging spacing requirement indirectly reinforces the case for overnight home charging.
Countervailing forces are material but manageable. High installation cost carries a -2.30% CAGR drag, legacy electrical-panel limits -1.80%, permitting delays -1.20%, and smart-charger cybersecurity concerns -0.90%. Households can face several thousand dollars in panel or service-line upgrades beyond the charger itself, which lengthens payback and disproportionately affects price-sensitive and older housing stock.
Value Chain and Procurement Dynamics
The residential charging value chain is fragmenting into four monetizable layers:
Silicon and power electronics: power modules, load-management ASICs, and metering components sourced largely from Asian foundries and specialized semiconductor suppliers.
Hardware OEMs and white-label assemblers: Level 1, Level 2, and emerging wireless/inductive charger manufacturers, increasingly bundling installation.
Installation and permitting networks: licensed electricians, panel-upgrade specialists, and inspection intermediaries whose bottlenecks directly cap conversion rates.
Software, energy management, and V2X platforms: managed-charging aggregators, solar-plus-storage integrators, and utility demand-response program operators.
Procurement strategy is shifting from one-off contractor purchasing to OEM-bundled programs (which represented 47.19% of 2026 volume) and integrator-led multi-family deployments. Buyers prioritizing total cost of ownership should negotiate load-management firmware as standard rather than optional, and validate panel-upgrade scope before signing installation contracts.
Segment Analysis: Where Value Is Concentrating
By charger type, Level 2 chargers held 67.83% of 2026 revenue share, reflecting their fit for overnight charging. Wireless and inductive chargers are the fastest-growing type at 34.78% CAGR through 2032, supported by capital flowing into wireless technology development.
By power band, medium power held 44.13% of 2026 share, while the high power band is projected to grow at 27.59% CAGR. By vehicle type, passenger cars accounted for 92.58%, but two-wheelers and micro-mobility are growing at 30.09% CAGR, a segment that will matter increasingly in Asian and Southern European cities.
Segment Dimension
Leading Category (2026 Share)
Fastest-Growing Category (CAGR to 2032)
Charger type
Level 2 (67.83%)
Wireless/inductive (34.78%)
Vehicle type
Passenger cars (92.58%)
Two-wheelers & micro-mobility (30.09%)
Power band
Medium power (44.13%)
High power (27.59%)
Connectivity
Smart/networked (65.55%)
Smart/networked (28.12%)
Installation type
Wall-mounted (60.25%)
Portable plug-in (28.35%)
Purchase channel
OEM bundled (47.19% of volume)
Specialist EV stores & installer networks (27.11%)
By connectivity, smart chargers hold 65.55% of 2026 revenue and are growing at 28.12% CAGR—the clearest signal that the market's future economics lie in software-enabled energy coordination rather than commodity hardware. By installation type, wall-mounted units command 60.25%, while portable plug-in chargers grow fastest at 28.35%. By purchase channel, specialist EV stores and installer networks are outpacing the overall market at 27.11% CAGR, gradually eroding the OEM-bundle dominance.
Regional Outlook and Investment Prioritization
Asia-Pacific's 40.01% share is underpinned by China's EV sales scale and aggressive domestic charging rollout. Europe and North America follow, with North America benefiting from federal tax credits and state-level building codes. The Middle East & Africa, though starting from a smaller base, is the fastest-growing region at 27.44% CAGR, driven by import-led EV adoption in markets with favorable tax treatment.
Residential EV Charging Market Regional Market Share
Loading chart...
For investors, the most attractive near-term white space is in multi-family and rental housing retrofits, where panel constraints and shared-parking economics have historically suppressed penetration. The second is integrated solar-plus-storage-plus-charger offerings: a 4 kW solar-based hybrid station can refuel 10–12 EVs daily and export surplus power, materially improving payback on residential solar arrays.
Competitive Landscape and Strategic Developments
The competitive field is medium-concentration, with hardware OEMs, energy-management platforms, and installer networks converging. Recent strategic moves underscore the shift toward integrated energy and wireless capability:
2025: Siemens acquired a USD 25 million stake in WiTricity, accelerating investment in wireless residential charging technology.
2025: Schneider Electric integrated solar, storage, and EV charging into a unified residential energy platform, simplifying prosumer monitoring.
2026: Emporia's Pro charger launched at USD 599 with built-in load management, illustrating smart features reaching mid-market price points.
Winning strategies combine three elements: firmware-led differentiation (load management and V2H readiness), installation ecosystem control (panel-upgrade partnerships and permitting navigation), and utility/VPP integration to monetize flexible home charging capacity.
Residential EV Charging Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Residential EV Charging Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 26.35% from 2020-2034
Segmentation
By Charger Type
Level 1
Up To 1.9 KW
Level 2
Wireless/Inductive
By Vehicle Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising EV adoption (+8.5% CAGR impact)
3.1.2. Government incentives for home charging (+6.2% CAGR impact)
3.2.4. Wireless and inductive charging growing at 34.78% CAGR through 2032
3.2.5. V2H/V2G monetization frameworks emerging in North America and Europe
3.3. Market Restrains
3.3.1. High installation cost including panel and service-line upgrades (-2.30% CAGR impact)
3.3.2. Legacy home electrical-panel limits (-1.80% CAGR impact)
3.3.3. Permit and inspection delays in North American jurisdictions (-1.20% CAGR impact)
3.3.4. Cybersecurity vulnerabilities in smart chargers (-0.90% CAGR impact)
Passenger Cars
Two-Wheelers and Micro-Mobility
Commercial
By Charging-Station Power Band
Low
Up To 3.7 KW
Medium
High
By Connectivity
Smart/Networked
Non-Smart
By Installation Type
Wall-Mounted
Portable Plug-In
By Purchase Channel
OEM Bundled
Specialist EV Stores and Installer Networks
Retail
By Geography
Asia-Pacific
China
Japan
India
South Korea
Australia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Netherlands
Norway
Middle East & Africa
UAE
Saudi Arabia
Jordan
South Africa
South America
Brazil
Argentina
Chile
3.4. Market Restraints
3.4.1. High installation cost including panel and service-line upgrades (-2.30% CAGR impact)
3.4.2. Legacy home electrical-panel limits (-1.80% CAGR impact)
3.4.3. Permit and inspection delays in North American jurisdictions (-1.20% CAGR impact)
3.4.4. Cybersecurity vulnerabilities in smart chargers (-0.90% CAGR impact)
3.5. Market Challenges
3.5.1. Several thousand dollars in potential panel or service-line upgrade costs per household
3.5.2. Fragmented permitting and inspection processes across jurisdictions
3.5.3. Converting multi-family and rental housing stock with shared-parking economics
3.5.4. Protecting smart chargers from cybersecurity vulnerabilities
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Charger Type
5.1.1. Level 1
5.1.1.1. Up To 1.9 KW
5.1.2. Level 2
5.1.3. Wireless/Inductive
5.2. Market Analysis, Insights and Forecast - by Vehicle Type
5.2.1. Passenger Cars
5.2.2. Two-Wheelers and Micro-Mobility
5.2.3. Commercial
5.3. Market Analysis, Insights and Forecast - by Charging-Station Power Band
5.3.1. Low
5.3.1.1. Up To 3.7 KW
5.3.2. Medium
5.3.3. High
5.4. Market Analysis, Insights and Forecast - by Connectivity
5.4.1. Smart/Networked
5.4.2. Non-Smart
5.5. Market Analysis, Insights and Forecast - by Installation Type
5.5.1. Wall-Mounted
5.5.2. Portable Plug-In
5.6. Market Analysis, Insights and Forecast - by Purchase Channel
5.6.1. OEM Bundled
5.6.2. Specialist EV Stores and Installer Networks
5.6.3. Retail
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. Asia-Pacific
5.7.2. North America
5.7.3. Europe
5.7.4. Middle East & Africa
5.7.5. South America
6. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Charger Type
6.1.1. Level 1
6.1.1.1. Up To 1.9 KW
6.1.2. Level 2
6.1.3. Wireless/Inductive
6.2. Market Analysis, Insights and Forecast - by Vehicle Type
6.2.1. Passenger Cars
6.2.2. Two-Wheelers and Micro-Mobility
6.2.3. Commercial
6.3. Market Analysis, Insights and Forecast - by Charging-Station Power Band
6.3.1. Low
6.3.1.1. Up To 3.7 KW
6.3.2. Medium
6.3.3. High
6.4. Market Analysis, Insights and Forecast - by Connectivity
6.4.1. Smart/Networked
6.4.2. Non-Smart
6.5. Market Analysis, Insights and Forecast - by Installation Type
6.5.1. Wall-Mounted
6.5.2. Portable Plug-In
6.6. Market Analysis, Insights and Forecast - by Purchase Channel
6.6.1. OEM Bundled
6.6.2. Specialist EV Stores and Installer Networks
6.6.3. Retail
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Charger Type
7.1.1. Level 1
7.1.1.1. Up To 1.9 KW
7.1.2. Level 2
7.1.3. Wireless/Inductive
7.2. Market Analysis, Insights and Forecast - by Vehicle Type
7.2.1. Passenger Cars
7.2.2. Two-Wheelers and Micro-Mobility
7.2.3. Commercial
7.3. Market Analysis, Insights and Forecast - by Charging-Station Power Band
7.3.1. Low
7.3.1.1. Up To 3.7 KW
7.3.2. Medium
7.3.3. High
7.4. Market Analysis, Insights and Forecast - by Connectivity
7.4.1. Smart/Networked
7.4.2. Non-Smart
7.5. Market Analysis, Insights and Forecast - by Installation Type
7.5.1. Wall-Mounted
7.5.2. Portable Plug-In
7.6. Market Analysis, Insights and Forecast - by Purchase Channel
7.6.1. OEM Bundled
7.6.2. Specialist EV Stores and Installer Networks
7.6.3. Retail
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Charger Type
8.1.1. Level 1
8.1.1.1. Up To 1.9 KW
8.1.2. Level 2
8.1.3. Wireless/Inductive
8.2. Market Analysis, Insights and Forecast - by Vehicle Type
8.2.1. Passenger Cars
8.2.2. Two-Wheelers and Micro-Mobility
8.2.3. Commercial
8.3. Market Analysis, Insights and Forecast - by Charging-Station Power Band
8.3.1. Low
8.3.1.1. Up To 3.7 KW
8.3.2. Medium
8.3.3. High
8.4. Market Analysis, Insights and Forecast - by Connectivity
8.4.1. Smart/Networked
8.4.2. Non-Smart
8.5. Market Analysis, Insights and Forecast - by Installation Type
8.5.1. Wall-Mounted
8.5.2. Portable Plug-In
8.6. Market Analysis, Insights and Forecast - by Purchase Channel
8.6.1. OEM Bundled
8.6.2. Specialist EV Stores and Installer Networks
8.6.3. Retail
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Charger Type
9.1.1. Level 1
9.1.1.1. Up To 1.9 KW
9.1.2. Level 2
9.1.3. Wireless/Inductive
9.2. Market Analysis, Insights and Forecast - by Vehicle Type
9.2.1. Passenger Cars
9.2.2. Two-Wheelers and Micro-Mobility
9.2.3. Commercial
9.3. Market Analysis, Insights and Forecast - by Charging-Station Power Band
9.3.1. Low
9.3.1.1. Up To 3.7 KW
9.3.2. Medium
9.3.3. High
9.4. Market Analysis, Insights and Forecast - by Connectivity
9.4.1. Smart/Networked
9.4.2. Non-Smart
9.5. Market Analysis, Insights and Forecast - by Installation Type
9.5.1. Wall-Mounted
9.5.2. Portable Plug-In
9.6. Market Analysis, Insights and Forecast - by Purchase Channel
9.6.1. OEM Bundled
9.6.2. Specialist EV Stores and Installer Networks
9.6.3. Retail
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Charger Type
10.1.1. Level 1
10.1.1.1. Up To 1.9 KW
10.1.2. Level 2
10.1.3. Wireless/Inductive
10.2. Market Analysis, Insights and Forecast - by Vehicle Type
10.2.1. Passenger Cars
10.2.2. Two-Wheelers and Micro-Mobility
10.2.3. Commercial
10.3. Market Analysis, Insights and Forecast - by Charging-Station Power Band
10.3.1. Low
10.3.1.1. Up To 3.7 KW
10.3.2. Medium
10.3.3. High
10.4. Market Analysis, Insights and Forecast - by Connectivity
10.4.1. Smart/Networked
10.4.2. Non-Smart
10.5. Market Analysis, Insights and Forecast - by Installation Type
10.5.1. Wall-Mounted
10.5.2. Portable Plug-In
10.6. Market Analysis, Insights and Forecast - by Purchase Channel
10.6.1. OEM Bundled
10.6.2. Specialist EV Stores and Installer Networks
10.6.3. Retail
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Siemens
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Schneider Electric
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Emporia
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. WiTricity
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. General Motors
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. BMW
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Volkswagen Group
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Residential EV Charging Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Charger Type 2026 & 2034
Figure 3: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Charger Type 2026 & 2034
Figure 4: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 5: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 6: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Charging-Station Power Band 2026 & 2034
Figure 7: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Charging-Station Power Band 2026 & 2034
Figure 8: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Connectivity 2026 & 2034
Figure 9: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Connectivity 2026 & 2034
Figure 10: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Installation Type 2026 & 2034
Figure 11: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Installation Type 2026 & 2034
Figure 12: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Purchase Channel 2026 & 2034
Figure 13: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Purchase Channel 2026 & 2034
Figure 14: Asia-Pacific Residential EV Charging Market Revenue (Billion), by Country 2026 & 2034
Figure 15: Asia-Pacific Residential EV Charging Market Revenue Share (%), by Country 2026 & 2034
Figure 16: North America Residential EV Charging Market Revenue (Billion), by Charger Type 2026 & 2034
Figure 17: North America Residential EV Charging Market Revenue Share (%), by Charger Type 2026 & 2034
Figure 18: North America Residential EV Charging Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 19: North America Residential EV Charging Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 20: North America Residential EV Charging Market Revenue (Billion), by Charging-Station Power Band 2026 & 2034
Figure 21: North America Residential EV Charging Market Revenue Share (%), by Charging-Station Power Band 2026 & 2034
Figure 22: North America Residential EV Charging Market Revenue (Billion), by Connectivity 2026 & 2034
Figure 23: North America Residential EV Charging Market Revenue Share (%), by Connectivity 2026 & 2034
Figure 24: North America Residential EV Charging Market Revenue (Billion), by Installation Type 2026 & 2034
Figure 25: North America Residential EV Charging Market Revenue Share (%), by Installation Type 2026 & 2034
Figure 26: North America Residential EV Charging Market Revenue (Billion), by Purchase Channel 2026 & 2034
Figure 27: North America Residential EV Charging Market Revenue Share (%), by Purchase Channel 2026 & 2034
Figure 28: North America Residential EV Charging Market Revenue (Billion), by Country 2026 & 2034
Figure 29: North America Residential EV Charging Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Europe Residential EV Charging Market Revenue (Billion), by Charger Type 2026 & 2034
Figure 31: Europe Residential EV Charging Market Revenue Share (%), by Charger Type 2026 & 2034
Figure 32: Europe Residential EV Charging Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 33: Europe Residential EV Charging Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 34: Europe Residential EV Charging Market Revenue (Billion), by Charging-Station Power Band 2026 & 2034
Figure 35: Europe Residential EV Charging Market Revenue Share (%), by Charging-Station Power Band 2026 & 2034
Figure 36: Europe Residential EV Charging Market Revenue (Billion), by Connectivity 2026 & 2034
Figure 37: Europe Residential EV Charging Market Revenue Share (%), by Connectivity 2026 & 2034
Figure 38: Europe Residential EV Charging Market Revenue (Billion), by Installation Type 2026 & 2034
Figure 39: Europe Residential EV Charging Market Revenue Share (%), by Installation Type 2026 & 2034
Figure 40: Europe Residential EV Charging Market Revenue (Billion), by Purchase Channel 2026 & 2034
Figure 41: Europe Residential EV Charging Market Revenue Share (%), by Purchase Channel 2026 & 2034
Figure 42: Europe Residential EV Charging Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Europe Residential EV Charging Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Charger Type 2026 & 2034
Figure 45: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Charger Type 2026 & 2034
Figure 46: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 47: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 48: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Charging-Station Power Band 2026 & 2034
Figure 49: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Charging-Station Power Band 2026 & 2034
Figure 50: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Connectivity 2026 & 2034
Figure 51: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Connectivity 2026 & 2034
Figure 52: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Installation Type 2026 & 2034
Figure 53: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Installation Type 2026 & 2034
Figure 54: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Purchase Channel 2026 & 2034
Figure 55: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Purchase Channel 2026 & 2034
Figure 56: Middle East & Africa Residential EV Charging Market Revenue (Billion), by Country 2026 & 2034
Figure 57: Middle East & Africa Residential EV Charging Market Revenue Share (%), by Country 2026 & 2034
Figure 58: South America Residential EV Charging Market Revenue (Billion), by Charger Type 2026 & 2034
Figure 59: South America Residential EV Charging Market Revenue Share (%), by Charger Type 2026 & 2034
Figure 60: South America Residential EV Charging Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 61: South America Residential EV Charging Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 62: South America Residential EV Charging Market Revenue (Billion), by Charging-Station Power Band 2026 & 2034
Figure 63: South America Residential EV Charging Market Revenue Share (%), by Charging-Station Power Band 2026 & 2034
Figure 64: South America Residential EV Charging Market Revenue (Billion), by Connectivity 2026 & 2034
Figure 65: South America Residential EV Charging Market Revenue Share (%), by Connectivity 2026 & 2034
Figure 66: South America Residential EV Charging Market Revenue (Billion), by Installation Type 2026 & 2034
Figure 67: South America Residential EV Charging Market Revenue Share (%), by Installation Type 2026 & 2034
Figure 68: South America Residential EV Charging Market Revenue (Billion), by Purchase Channel 2026 & 2034
Figure 69: South America Residential EV Charging Market Revenue Share (%), by Purchase Channel 2026 & 2034
Figure 70: South America Residential EV Charging Market Revenue (Billion), by Country 2026 & 2034
Figure 71: South America Residential EV Charging Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Residential EV Charging Market Revenue Billion Forecast, by Charger Type 2020 & 2034
Table 2: Global Residential EV Charging Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 3: Global Residential EV Charging Market Revenue Billion Forecast, by Charging-Station Power Band 2020 & 2034
Table 4: Global Residential EV Charging Market Revenue Billion Forecast, by Connectivity 2020 & 2034
Table 5: Global Residential EV Charging Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 6: Global Residential EV Charging Market Revenue Billion Forecast, by Purchase Channel 2020 & 2034
Table 7: Global Residential EV Charging Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Charger Type 2020 & 2034
Table 9: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 10: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Charging-Station Power Band 2020 & 2034
Table 11: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Connectivity 2020 & 2034
Table 12: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 13: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Purchase Channel 2020 & 2034
Table 14: Asia-Pacific Residential EV Charging Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: China Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Japan Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: India Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: South Korea Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Australia Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: North America Residential EV Charging Market Revenue Billion Forecast, by Charger Type 2020 & 2034
Table 21: North America Residential EV Charging Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 22: North America Residential EV Charging Market Revenue Billion Forecast, by Charging-Station Power Band 2020 & 2034
Table 23: North America Residential EV Charging Market Revenue Billion Forecast, by Connectivity 2020 & 2034
Table 24: North America Residential EV Charging Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 25: North America Residential EV Charging Market Revenue Billion Forecast, by Purchase Channel 2020 & 2034
Table 26: North America Residential EV Charging Market Revenue Billion Forecast, by Country 2020 & 2034
Table 27: USA Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Canada Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Mexico Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Europe Residential EV Charging Market Revenue Billion Forecast, by Charger Type 2020 & 2034
Table 31: Europe Residential EV Charging Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 32: Europe Residential EV Charging Market Revenue Billion Forecast, by Charging-Station Power Band 2020 & 2034
Table 33: Europe Residential EV Charging Market Revenue Billion Forecast, by Connectivity 2020 & 2034
Table 34: Europe Residential EV Charging Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 35: Europe Residential EV Charging Market Revenue Billion Forecast, by Purchase Channel 2020 & 2034
Table 36: Europe Residential EV Charging Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: Germany Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: UK Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: France Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Netherlands Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Norway Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Charger Type 2020 & 2034
Table 43: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 44: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Charging-Station Power Band 2020 & 2034
Table 45: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Connectivity 2020 & 2034
Table 46: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 47: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Purchase Channel 2020 & 2034
Table 48: Middle East & Africa Residential EV Charging Market Revenue Billion Forecast, by Country 2020 & 2034
Table 49: UAE Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Saudi Arabia Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Jordan Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: South Africa Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: South America Residential EV Charging Market Revenue Billion Forecast, by Charger Type 2020 & 2034
Table 54: South America Residential EV Charging Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 55: South America Residential EV Charging Market Revenue Billion Forecast, by Charging-Station Power Band 2020 & 2034
Table 56: South America Residential EV Charging Market Revenue Billion Forecast, by Connectivity 2020 & 2034
Table 57: South America Residential EV Charging Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 58: South America Residential EV Charging Market Revenue Billion Forecast, by Purchase Channel 2020 & 2034
Table 59: South America Residential EV Charging Market Revenue Billion Forecast, by Country 2020 & 2034
Table 60: Brazil Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 61: Argentina Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 62: Chile Residential EV Charging Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the residential EV charging market size in 2026?
Our proprietary primary research estimates the global residential EV charging market at USD 12.23 billion in 2026, rising to USD 15.45 billion in 2027 and reaching USD 49.76 billion by 2032 at a 26.35% CAGR.
2Which region holds the largest share of the residential EV charging market?
Asia-Pacific is the largest regional market, accounting for 40.01% of 2026 revenue, driven by China's EV sales scale and domestic charging rollout.
3What charger type dominates residential EV charging installations?
Level 2 chargers held 67.83% of 2026 residential market share, reflecting their suitability for overnight home charging, while wireless and inductive chargers are the fastest-growing type at 34.78% CAGR.
4What incentives support residential EV charger adoption in the United States?
U.S. individuals can offset 30% of qualified residential charging installation expenses, capped at USD 1,000, through 2032. California additionally requires EV-ready circuits in every new dwelling from 2026.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted structured interviews and surveys with senior decision-makers across the residential EV charging value chain, allocating 70–80% of total research effort to primary collection.
Interviewed company types include Level 2 and wireless charger OEMs, licensed electrical installation and panel-upgrade contractors, residential solar-plus-storage integrators, utility demand-response program managers, and multi-family property technology providers.
Stakeholder job titles include Head of EV Charging Product Management, Director of Residential Installation Operations, Energy Management Platform Lead, and Utility Program Manager for Distributed Energy Resources.
We benchmark against technical standards and regulatory frameworks from the International Electrotechnical Commission (IEC), SAE International, the U.S. Department of Energy, and the European Union's Energy Performance of Buildings Directive.
Quantitative inputs captured in bottom-up models include unit shipments by charger type, average selling prices by power band, installation attach rates, and panel-upgrade incidence rates.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of EV Charging Product Management
32%
Director of Residential Installation Operations
28%
Energy Management Platform Lead
22%
Utility Program Manager, Distributed Energy Resources
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Level 2 and wireless charger OEMs
35%
Electrical installation and panel-upgrade contractors
25%
Residential solar-plus-storage integrators
20%
Utility demand-response and VPP program managers
12%
Multi-family property technology providers
8%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on official multilateral and governmental sources, including the International Energy Agency, UN Comtrade, World Bank, OECD, Eurostat, and U.S. Department of Energy datasets.
Financial and corporate intelligence is sourced from Bloomberg, Factiva, Hoovers, and PitchBook to validate OEM revenue exposure and M&A activity.
Trade association and non-profit technical benchmarks are incorporated from SAE International, IEC, and the Zero Emission Transportation Association.
All secondary figures are triangulated against primary interview findings; no commercial market research portals or third-party report publishers are used.
Every report is updated to the date of purchase to reflect the latest policy, tariff, and product-launch developments.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across charger types, power bands, connectivity, and installation channels.
Bottom-up market sizing is built from specific quantitative metrics: global private charge point installations (43 million units at end-2025), EV sales volumes by region (20 million units in 2025), average charger selling prices by power band, and installation attach rates by purchase channel.
Regional models incorporate policy-specific variables such as the U.S. 30% installation tax credit cap, California's 2026 EV-ready building code, and the EU Alternative Fuels Infrastructure Regulation's 60 km charging spacing rule.
Driver and restraint impact coefficients—such as rising EV adoption at +8.5% CAGR impact and high installation cost at -2.30%—are derived from regression analysis of primary survey responses and validated against historical shipment data.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-level triangulation and cross-validation of primary and secondary inputs.
All market size and CAGR estimates are stress-tested against alternative scenario assumptions for policy rollback, panel-upgrade bottlenecks, and semiconductor supply constraints.
Expert review panels re-validate segment shares and regional splits prior to publication, with discrepancies above 5% flagged for re-interview.
Data is refreshed to the date of purchase, ensuring alignment with the latest regulatory and product-launch developments.