1What is the current size of the global render farm market?
The global render farm market is valued at USD 5.06 Billion in 2025 and is projected to reach USD 12 Billion by 2035, growing at a CAGR of 9.1%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Render Farm Market
 by Application (Visual Effects, Animation, Architectural Visualization, Product Design, Simulation, Gaming), by Deployment Model (On-Premises, Cloud-Based, Hybrid), by Service Type (Rendering Services, Storage Services, Consulting Services, Support Services, GPU-Based Rendering, CPU-Based Rendering, Hybrid Rendering), by End Use Industries (Media and Entertainment, Gaming, Architecture and Construction, Manufacturing, Automotive), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, South Korea, India), by South America (Brazil, Argentina), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034
Research Associate

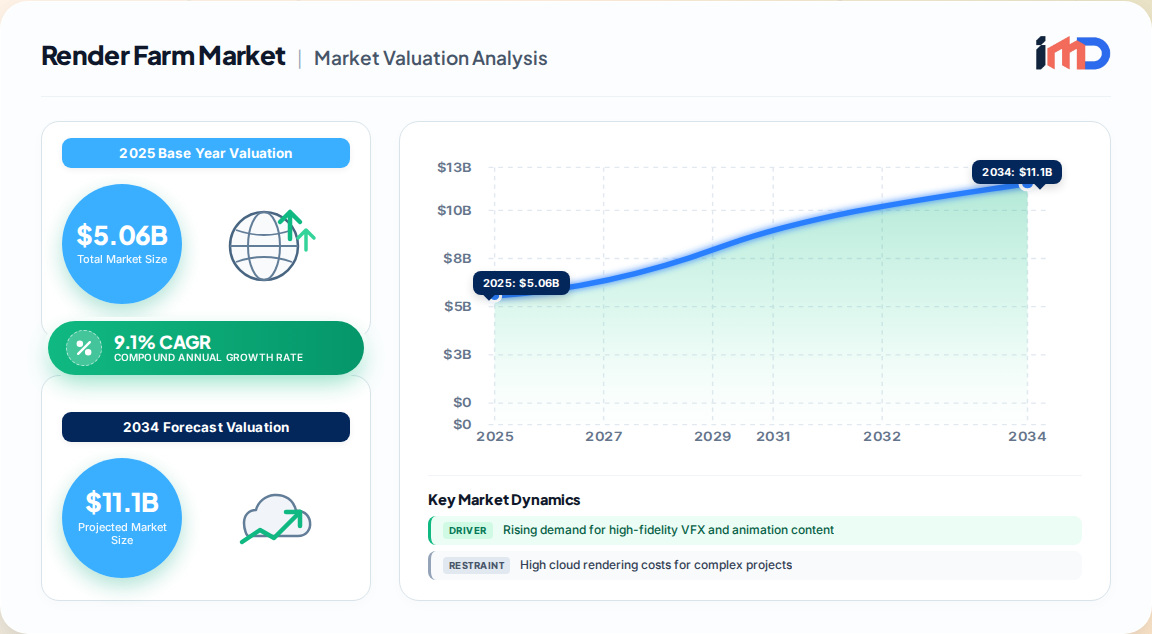
The global render farm market is estimated at USD 5.06 Billion in 2025 and is projected to reach USD 12 Billion by 2035, advancing at a CAGR of 9.1% over the forecast period. Render farms—clusters of high-performance computing nodes dedicated to generating 2D and 3D digital imagery—have become foundational infrastructure for media and entertainment, gaming, architecture, manufacturing, and simulation-driven industries. Demand is being reshaped by the migration from on-premises render infrastructure to cloud and hybrid models, by GPU-accelerated and AI-assisted rendering, and by the rapid expansion of high-resolution content pipelines across streaming, virtual production, and real-time visualization.
Our proprietary bottom-up modeling, triangulated with primary interviews across render farm operators, software vendors, and studio technology leaders, indicates that the addressable compute capacity consumed by rendering workloads will more than double between 2025 and 2030. The market is transitioning from a capacity-constrained, hardware-centric model to a service-oriented, consumption-based model in which flexibility, latency, and cost per frame define competitive advantage.
| Value Chain Stage | Key Activities | Representative Participants |
|---|---|---|
| Silicon and Hardware | GPU/CPU manufacturing, server assembly, networking | NVIDIA, AMD, Intel, server OEMs |
| Infrastructure Providers | Data centers, cloud compute, storage, networking | AWS, Microsoft Azure, Google Cloud, colocation providers |
| Render Management Software | Scheduler, orchestration, plugin integration | Autodesk, Foundry, open-source and proprietary tools |
| Render Farm Service Providers | Managed rendering, storage, consulting, support | Fox Renderfarm, RebusFarm, GarageFarm, Ranch Computing, iRender |
| Content Creators | VFX, animation, gaming, architecture, manufacturing | Studios, design firms, automotive OEMs |
| Distribution and Consumption | Streaming, broadcast, theatrical, interactive media | Platforms, broadcasters, enterprises |
The value chain is converging: cloud hyperscalers are moving up into managed rendering services, while specialized render farms are layering consulting, storage, and pipeline integration to differentiate. Software vendors are embedding AI and cloud orchestration directly into content creation tools, compressing the distance between creation and rendering.
By Service Type: GPU-based rendering is the dominant service type at roughly 49% share in 2025, favored for VFX, animation, and gaming. Hybrid rendering is the fastest-growing at approximately 23% CAGR, as studios match workloads to the most efficient compute resource. CPU-based rendering remains relevant for simulation, scientific visualization, and certain simulation-heavy manufacturing workloads.
By Deployment Model: Public cloud holds approximately 62% of the market, driven by on-demand scalability. Hybrid cloud is the fastest-growing deployment model at roughly 25% CAGR, reflecting enterprise preferences for workload placement flexibility. On-premises render farms persist where data control and predictable utilization justify capital investment.
By Application: Visual effects leads with about 34% share, followed by animation, architectural visualization, product design, and simulation. Gaming is the fastest-growing application at approximately 23% CAGR, with architectural visualization and automotive design also expanding rapidly.
By End-Use Industry: Media and entertainment dominate at approximately 61% of demand, while automotive is the fastest-growing end-use vertical at roughly 26% CAGR, driven by digital twins, simulation, and virtual prototyping. Architecture and construction and manufacturing follow, with growing adoption of photorealistic visualization.
| Region | Market Position | Key Characteristics |
|---|---|---|
| North America | Largest market (~28% share) | Deep media and entertainment ecosystem, leading cloud providers, high VFX spend |
| Europe | Mature (~23% share) | Strong creative industries, data-sovereignty preferences, hybrid adoption |
| Asia-Pacific | Fastest-growing (~40% share) | Rapid animation and gaming expansion, rising cloud investment, cost-competitive studios |
| South America | Emerging (~5% share) | Growing production services, infrastructure constraints |
| Middle East & Africa | Nascent (~4% share) | Early-stage adoption, government-led digital content initiatives |
Asia-Pacific is the growth engine of the render farm market, underpinned by expanding animation studios, mobile gaming, and government-backed digital content initiatives. North America retains leadership through concentration of VFX houses, streaming platforms, and hyperscale cloud infrastructure. Europe demonstrates steady adoption, with hybrid models favored for data governance. The U.S. market alone is estimated at USD 0.98 Billion in 2025, projected to reach USD 4.44 Billion by 2035 at a CAGR of 16.4% within the cloud render farm services segment.
The render farm market is on a trajectory to exceed USD 12 Billion by 2035, driven by content proliferation, GPU and AI acceleration, and the structural shift to cloud and hybrid consumption models. Stakeholders should prioritize AI-enabled rendering optimization, hybrid deployment flexibility, and regional capacity expansion to capture growth in Asia-Pacific and emerging verticals such as automotive and architectural visualization. Security, cost transparency, and pipeline integration will remain key differentiators as competition intensifies across hyperscalers and specialist providers.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.1% from 2020-2034 |
| Segmentation |
|
By Deployment Model
By Service Type
By End Use Industries
| By Geography |
|
The global render farm market is valued at USD 5.06 Billion in 2025 and is projected to reach USD 12 Billion by 2035, growing at a CAGR of 9.1%.
Visual effects (VFX) is the largest application segment, accounting for approximately 34% of cloud render farm service demand in 2025, driven by film, television, and streaming content production.
The market includes on-premises, cloud-based, and hybrid deployment models. Public cloud holds about 62% share, while hybrid cloud is the fastest-growing at around 25% CAGR.
Asia-Pacific is the fastest-growing region, underpinned by expanding animation and gaming industries, rising cloud investment, and government digital content initiatives.
AI is used to optimize rendering workloads, predict resource needs, automate scheduling, denoise images, and enable machine-learning training for VFX, significantly reducing render times and infrastructure costs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 30% |
| Head of Production Technology | 25% |
| Render Pipeline Supervisor | 25% |
| Cloud Infrastructure Architect | 20% |
| Company Type | Representation (%) |
|---|---|
| Render Farm Service Providers | 35% |
| Cloud Hyperscalers & Data Centers | 20% |
| GPU/CPU Hardware & Server OEMs | 15% |
| Render Management Software Vendors | 15% |
| Content Production Studios | 15% |

 Related Reports
