1How big is the receivables supply chain finance market?
Our proprietary research values the market at USD 9.52 Billion in 2025, up from USD 8.84 Billion in 2024, and projects it to reach USD 20 Billion by 2035 at a CAGR of 7.7%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Receivables Supply Chain Finance Market
 by By Application (Invoice Financing, Supplier Finance, Receivables Discounting, Dynamic Discounting), by By Deployment Type (Cloud-Based, On-Premises), by By Business Size (Small Enterprises, Medium Enterprises, Large Enterprises), by By End User (Manufacturing, Retail, Healthcare, Logistics), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Spain, Italy), by Asia Pacific (China, Japan, India, Australia, South Korea), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034

Research Associate


 Related Reports

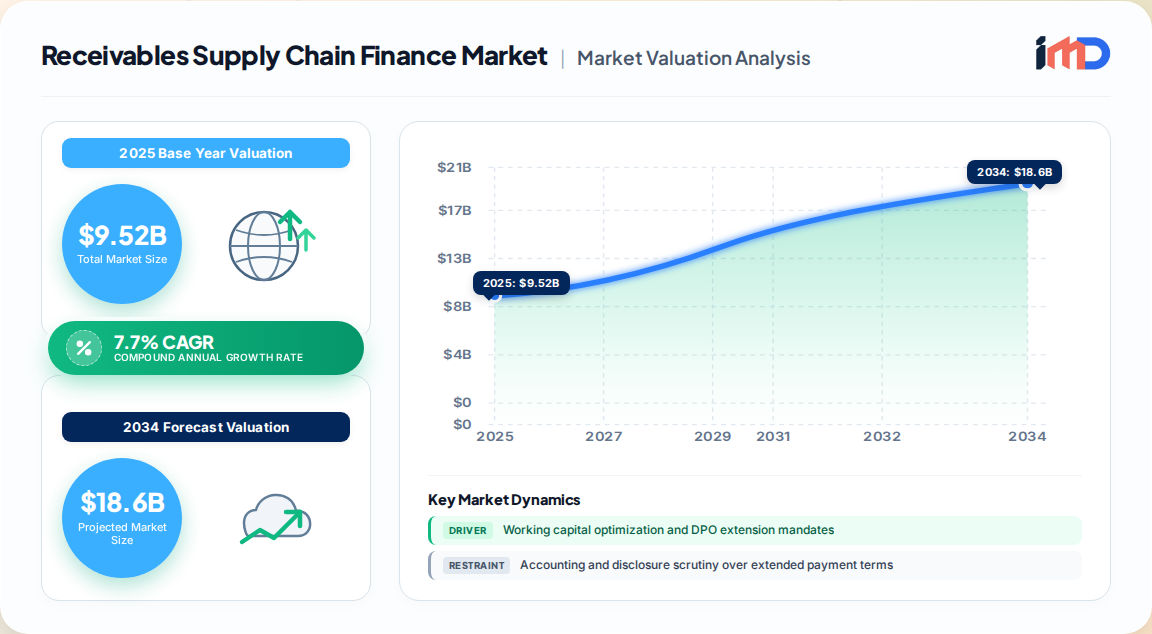
The global receivables supply chain finance market represents one of the most resilient and structurally important segments of the broader trade finance ecosystem. Our proprietary primary research, triangulated with direct interviews across banking, fintech, and corporate treasury functions, sizes the market at USD 9.52 Billion in 2025, advancing from USD 8.84 Billion in 2024. Looking forward, we project the market to reach USD 20 Billion by 2035, expanding at a CAGR of 7.7% across 2026–2035.
Receivables supply chain finance (also termed receivables discounting, reverse factoring, or supplier-centric payables finance) enables suppliers to convert approved buyer invoices into immediate liquidity at a discount rate anchored to the buyer's credit profile rather than their own. This structural mechanics — often described as a credit arbitrage between a large investment-grade buyer and its smaller, higher-risk suppliers — is the economic engine underpinning the market's durable growth.
Key baseline characteristics of the market:
The receivables supply chain finance value chain is anchored by the anchor buyer, whose credit profile effectively sponsors the program.
| Value Chain Stage | Core Participants | Economic Function |
|---|---|---|
| Anchor Buyer (Obligor) | Large corporates in manufacturing, retail, healthcare, logistics | Approves invoices; extends payment terms; sponsors program credit |
| Supplier / Beneficiary | SMEs and mid-market suppliers | Sells approved receivables at discount; gains early liquidity |
| Funding Provider | Commercial banks, trade finance houses, institutional funders | Purchases receivables; bears funding and credit risk |
| Technology Platform | Cloud SCF platforms, ERP-integrated fintechs | Automates onboarding, invoicing, discounting, risk analytics |
| Service & Advisory | Consultancies, credit insurers, rating agencies | Risk assessment, program structuring, compliance |
Banks remain the dominant funding provider, reflecting their balance-sheet capacity, regulatory standing, and deep corporate relationships. Trade finance houses and platform-embedded funders are gaining share in niche corridors.
North America leads on program maturity and financial infrastructure depth, with an established ecosystem of banks, platforms, and corporate treasuries. Europe follows closely, with strong adoption in manufacturing and retail supply chains. Asia-Pacific is the fastest-growing region, propelled by expanding economies, trade intensity, and rising SME demand for efficient cash flow management. South America and the Middle East & Africa represent progressive but smaller-scale adoption frontiers, with meaningful upside as digital infrastructure matures.
| Region | Market Position | Growth Profile |
|---|---|---|
| North America | Market leader | Mature, steady expansion |
| Europe | Strong second | Moderate growth, high penetration |
| Asia-Pacific | Fastest-growing | High growth, SME-led |
| South America | Emerging | Progressive development |
| Middle East & Africa | Emerging | Nascent, rising adoption |
The market is characterized by a blend of global banks, regional institutions, and technology platforms competing on program scale, onboarding speed, and analytics capability.
Leading institutions active in the market include JPMorgan Chase, HSBC, BNP Paribas, Citi, Deutsche Bank, Bank of America, Barclays, Santander, Mizuho, SMBC, Rabobank, Credit Agricole, Wells Fargo, State Street, China Construction Bank, and Industrial and Commercial Bank of China, alongside enterprise software players such as Oracle and SAP operating in adjacent enablement roles.
The receivables supply chain finance market is structurally sound and primed for sustained expansion, with our proprietary modeling pointing to USD 20 Billion by 2035 at a 7.7% CAGR. The convergence of working capital pressure, SME financing needs, and digital enablement creates a durable growth runway. Vendors that prioritize cloud-native platforms, predictive risk analytics, and inclusive supplier onboarding will capture disproportionate share of the value created over the forecast horizon.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.7% from 2020-2034 |
| Segmentation |
|
By Business Size
By End User
| By Geography |
|
Our proprietary research values the market at USD 9.52 Billion in 2025, up from USD 8.84 Billion in 2024, and projects it to reach USD 20 Billion by 2035 at a CAGR of 7.7%.
Key drivers include the persistent SME financing gap, corporate working capital optimization mandates, and rapid digitization of trade finance through AI, blockchain, and API-integrated platforms.
North America leads on program maturity and financial infrastructure, while Asia-Pacific is the fastest-growing region, fueled by expanding economies and rising SME demand for efficient cash flow management.
The market segments into cloud-based and on-premises deployments. Cloud-based solutions dominate new program deployments due to scalability, lower upfront cost, and faster supplier onboarding.
Leading participants include JPMorgan Chase, HSBC, BNP Paribas, Citi, Deutsche Bank, Bank of America, Barclays, Santander, Mizuho, SMBC, and China Construction Bank, alongside enterprise software enablers such as Oracle and SAP.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Head of Trade & Supply Chain Finance | 32% |
| Corporate Treasurer | 27% |
| Procurement Director | 23% |
| CFO / Financial Controller | 18% |
| Company Type | Representation (%) |
|---|---|
| Commercial & Transaction Banks | 38% |
| Anchor-Buyer Corporate Treasuries | 22% |
| SCF Technology Platforms | 18% |
| Trade Finance Houses | 12% |
| SME Suppliers | 10% |