Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Real Estate Industry Market Size, Growth & Forecast to 2030
Real Estate Industry by Property Type (Residential, Commercial, Industrial, Land), by Transaction Type (Sales, Rental, Lease), by Service (Brokerage, Property Management, Appraisal, Development), by Asia-Pacific (China, India, Japan, Australia, Indonesia, South Korea), by North America (USA, Canada, Mexico), by Europe (UK, Germany, France, Italy, Spain), by South America (Brazil, Chile, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Nigeria) Forecast 2026-2034
India facility management market valued at USD 2.86 Billion in 2025, growing at 10.66% CAGR to reach USD 7.13 Billion by 2034, led by South India.
Nov 2026|198 pages
$2900.00
Property And Casualty Reinsurance Market valued at USD 398.3 Billion in 2024, projected to reach USD 1,245.46 Billion by 2035 at a 10.92% CAGR.
Nov 2026|245 pages
$2900.00
IP valuation market valued at $14.16 Billion in 2026, reaching $30.75 Billion by 2034 at a 10.18% CAGR, driven by M&A and IP-backed finance.
Nov 2026|216 pages
$2900.00
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.
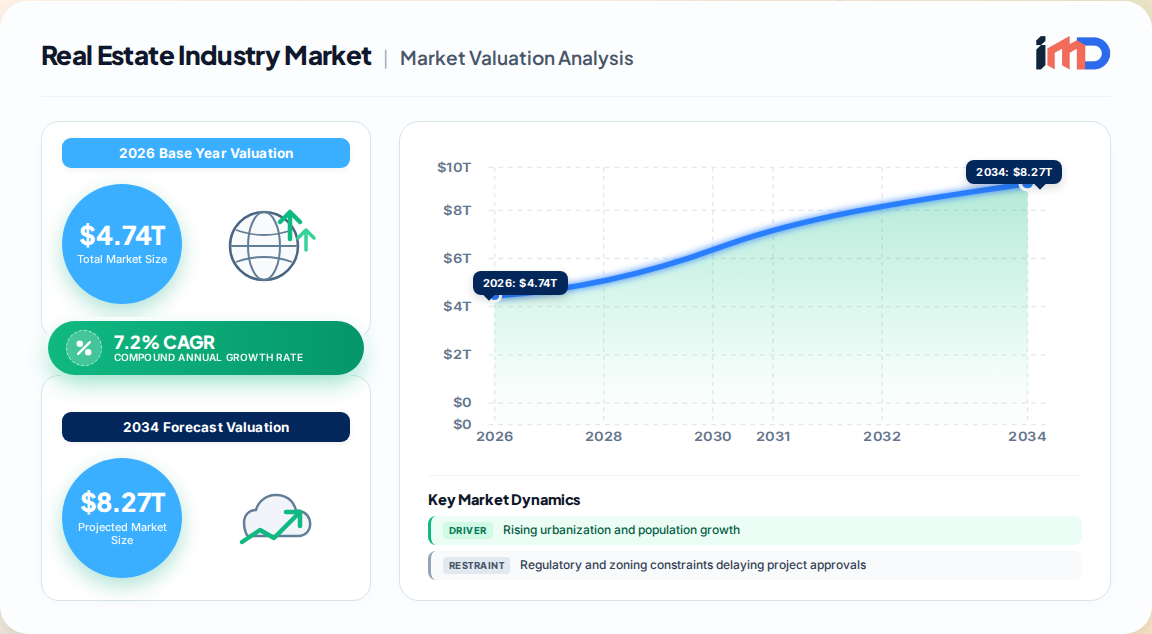
The global real estate industry market represents one of the largest and most systemically important sectors in the world economy. Our proprietary primary research estimates the market at USD 4.74 Trillion in 2026, up from USD 4.44 Trillion in 2025, reflecting a strong 6.8% year-over-year growth rate. Looking forward, we project the market to reach USD 6.26 Trillion by 2030, expanding at a 7.2% CAGR over the forecast period (2026–2030).
Real Estate Industry Market Size (In Million)
7.5M
6.0M
4.5M
3.0M
1.5M
0
4.422 M
2025
4.740 M
2026
5.081 M
2027
5.447 M
2028
5.839 M
2029
6.260 M
2030
6.710 M
2031
This valuation captures revenues earned by entities engaged in residential and non-residential building rental, leasing, brokerage, property management, and real estate development activities. The sector's scale is underscored by the OECD, which estimates that built real estate stock across 34 OECD member countries alone is valued at USD 111 Trillion, equivalent to 196% of total GDP—nearly double the economic output of those nations. Such magnitude positions real estate as both a primary driver of household wealth and a potential source of systemic financial vulnerability.
Historic growth (2021–2025): Driven by rising urbanization, expanding commercial infrastructure, and increased investment in property portfolios.
Forecast growth (2026–2030): Accelerated by demand for modern housing, urban infrastructure improvement, and the expansion of rental and brokerage services.
Geographic dominance: Asia-Pacific was the largest region in 2025, accounting for an estimated 41% of global market value, followed by North America at 26%.
Market Drivers & Restraints
Key Growth Drivers
Urbanization and Population Growth: According to the OECD, 82.7% of the U.S. population already lives in urban areas, and similar trends are accelerating across Asia-Pacific. The UN projects that global urban populations will increase by 2.5 billion by 2050, directly fueling demand for residential and commercial properties.
Construction Activity Expansion: In Australia alone, 240,813 dwellings were under construction in Q1 2023, up from 240,065 in 2022, per the Australian Bureau of Statistics. This pipeline of new supply sustains rental and sales revenue streams.
Economic Growth and Employment: In Q2 2024, U.S. real GDP expanded by 2.8%, while unemployment declined to 3.5% by July 2023, boosting disposable incomes and property purchasing power.
Technological Innovation: AI-driven property platforms, such as those launched by Klipster Inc. in October 2025, are streamlining property discovery, virtual tours, and transaction completion, reducing search friction and expanding market participation.
Market Restraints and Challenges
Regulatory and Zoning Constraints: Government policies, tax structures, and zoning rules directly influence property values and development feasibility, often delaying project timelines and increasing compliance costs.
Economic Uncertainties: Recessions, interest rate volatility, and cap rate expansions constrain investment. U.S. property values declined by approximately 20% since early 2022, with cap rates rising 150–200 basis points, per our analysis of institutional data.
Climate-Related Financial Risks: The OECD reports that climate-related disasters cost up to USD 430 Billion annually (0.5% of global GDP). Physical hazards such as floods and wildfires damage assets, while transition risks from energy-performance standards can strand carbon-intensive properties.
Insurance Protection Gaps: Rising premiums and insurer withdrawals from high-risk areas are increasing financing constraints for property owners and developers.
Value Chain Analysis
The real estate industry value chain comprises tightly linked input and output markets. Bottlenecks in land release, skilled labor, or materials quickly transmit to output markets through increased rents and prices.
Value Chain Stage
Key Activities
Primary Participants
Input Markets
Land acquisition, construction materials, labor, finance, approvals
Landowners, material suppliers (cement, steel, glass), construction firms, banks
Development & Construction
Design, building, project management
Builders, developers, contractors
Transaction & Brokerage
Sales, leasing, appraisal, title services
Real estate brokers, agents, appraisers, MLS platforms
Residential occupancy, commercial tenancy, industrial use
Households, businesses, institutional investors
The OECD notes that buildings account for 37% of global energy-related emissions, making sustainable construction and retrofit activities a critical value-chain consideration. Developed economies are increasingly integrating whole-life-carbon assessments into permitting, which is reshaping supplier requirements.
Regional Outlook
Asia-Pacific commands the largest share of the global real estate market, driven by rapid urbanization and population growth in China, India, and Indonesia. The region's transition from rural to urban living is fueling demand for commercial real estate, office spaces, and retail centers. North America remains the second-largest market, supported by strong fundamentals in multifamily and industrial assets. In the U.S., the residential segment led with a 57.09% revenue share in 2024, while rental models accounted for 52.77% of transaction value, reflecting a shift toward renting due to affordability constraints.
Real Estate Industry Regional Market Share
Loading chart...
Europe's market is shaped by stringent energy-performance regulations and climate-risk disclosure requirements. The OECD highlights that compliance pathways and costs are set locally, creating fragmented transition risks across municipalities. South America and the Middle East & Africa offer emerging opportunities, particularly in smart-city developments and infrastructure-linked real estate.
Region
2025 Market Share
Key Growth Factors
Asia-Pacific
41%
Urbanization, population growth, commercial expansion
North America
26%
Multifamily demand, data centers, rental affordability
The market features a mix of global conglomerates and regional specialists. Key players include Brookfield Asset Management, Mitsui Fudosan, Sun Hung Kai Properties, Prologis, Simon Property Group, and Lennar Corporation, among others. Competitive differentiation is increasingly driven by:
Technology Integration: AI-powered platforms for property discovery and transaction management are becoming a core capability. The acquisition of Flyhomes' consumer search technology by The Real Brokerage Inc. in July 2025 exemplifies this trend.
Portfolio Diversification: Investors are favoring multifamily and industrial assets due to strong fundamentals and long-term tailwinds, while data centers are emerging as a high-growth niche, with pricing for 250-to-500-kW requirements rising 16% year-over-year in 2023.
Sustainability and Resilience: Compliance with energy-performance standards and climate-risk management is shifting from a compliance cost to a competitive advantage. The OECD emphasizes that embedding climate-risk management in property-level decisions improves asset marketability and reduces stranded-asset risk.
Capital Allocation: Institutional investors remain under-allocated to digital infrastructure by 1.5% to 3% compared to other asset classes, signaling significant white-space opportunity in data center and logistics real estate.
Strategic White-Space Analysis
Our primary research identifies several high-potential opportunity areas:
Smart Cities and Sustainable Development: Governments worldwide are investing in eco-friendly, tech-savvy urban environments. Real estate developers that integrate IoT, smart infrastructure, and energy-efficient designs can capture premium pricing and regulatory incentives.
Multifamily Housing in North America: With homeownership increasingly out of reach due to high mortgage rates, demand for rental properties is surging. The U.S. Census reports that 43.9 million homes (31.4% of total housing stock) house multiple generations, prompting developers to create adaptable multifamily units.
Data Center Expansion: The surge in AI and cloud computing is driving demand for data centers. Despite supply constraints, pricing continues to climb, attracting institutional investment.
Climate Adaptation Retrofits: As physical risks intensify, retrofitting existing building stock for resilience and energy efficiency represents a multi-trillion-dollar opportunity. The OECD estimates that aligning national climate targets with local delivery tools can reduce execution risk and stranded assets.
Import/Export & Supplier Dynamics
While real estate itself is not a tradable commodity, the sector's supply chain is deeply integrated with global trade in construction materials. Buildings account for 34% of total CO₂ emissions, with 55% of that coming from cement, steel, and aluminum, and an additional 3% from brick and glass. Trade flows in these materials directly influence construction costs and project viability.
Cement and Steel: Major exporters include China, India, and Turkey, while import-dependent regions such as the Middle East and Africa are vulnerable to price volatility.
Building Materials: The EU's Carbon Border Adjustment Mechanism (CBAM) is reshaping trade dynamics by imposing carbon costs on imported steel, cement, and aluminum, incentivizing low-carbon sourcing.
Equipment and Technology: Suppliers of smart building technologies, IoT sensors, and energy-management systems are increasingly critical value-chain partners, particularly in OECD markets where energy-performance standards are stringent.
Our analysis indicates that supply-chain bottlenecks in materials and skilled labor can amplify property price inflation, particularly in high-growth urban markets. Developers are responding by diversifying supplier bases and investing in modular construction techniques to reduce lead times.
Real Estate Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Real Estate Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.2% from 2020-2034
Segmentation
By Property Type
Residential
Commercial
Industrial
Land
By Transaction Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising urbanization and population growth
3.1.2. Expanding construction activity and infrastructure investment
3.1.3. Economic growth and employment strengthening purchasing power
3.2.1. AI-driven property discovery platforms and virtual tours
3.2.2. Shift toward multifamily and rental housing due to affordability constraints
3.2.3. Data center expansion driven by AI and cloud computing demand
3.2.4. Climate-risk integration into property valuation and investment decisions
3.3. Market Restrains
3.3.1. Regulatory and zoning constraints delaying project approvals
3.3.2. Economic uncertainties and interest rate volatility
3.3.3. Climate-related physical and transition risks increasing insurance and financing costs
3.4. Market Restraints
3.4.1. Regulatory and zoning constraints delaying project approvals
3.4.2. Economic uncertainties and interest rate volatility
Sales
Rental
Lease
By Service
Brokerage
Property Management
Appraisal
Development
By Geography
Asia-Pacific
China
India
Japan
Australia
Indonesia
South Korea
North America
USA
Canada
Mexico
Europe
UK
Germany
France
Italy
Spain
South America
Brazil
Chile
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Nigeria
3.4.3. Climate-related physical and transition risks increasing insurance and financing costs
3.5. Market Challenges
3.5.1. Insurance protection gaps in high-risk areas
3.5.2. Skilled labor shortages and supply-chain bottlenecks
3.5.3. Stranded asset risk from energy-performance regulations
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Property Type
5.1.1. Residential
5.1.2. Commercial
5.1.3. Industrial
5.1.4. Land
5.2. Market Analysis, Insights and Forecast - by Transaction Type
5.2.1. Sales
5.2.2. Rental
5.2.3. Lease
5.3. Market Analysis, Insights and Forecast - by Service
5.3.1. Brokerage
5.3.2. Property Management
5.3.3. Appraisal
5.3.4. Development
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Asia-Pacific
5.4.2. North America
5.4.3. Europe
5.4.4. South America
5.4.5. Middle East & Africa
6. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Property Type
6.1.1. Residential
6.1.2. Commercial
6.1.3. Industrial
6.1.4. Land
6.2. Market Analysis, Insights and Forecast - by Transaction Type
6.2.1. Sales
6.2.2. Rental
6.2.3. Lease
6.3. Market Analysis, Insights and Forecast - by Service
6.3.1. Brokerage
6.3.2. Property Management
6.3.3. Appraisal
6.3.4. Development
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Property Type
7.1.1. Residential
7.1.2. Commercial
7.1.3. Industrial
7.1.4. Land
7.2. Market Analysis, Insights and Forecast - by Transaction Type
7.2.1. Sales
7.2.2. Rental
7.2.3. Lease
7.3. Market Analysis, Insights and Forecast - by Service
7.3.1. Brokerage
7.3.2. Property Management
7.3.3. Appraisal
7.3.4. Development
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Property Type
8.1.1. Residential
8.1.2. Commercial
8.1.3. Industrial
8.1.4. Land
8.2. Market Analysis, Insights and Forecast - by Transaction Type
8.2.1. Sales
8.2.2. Rental
8.2.3. Lease
8.3. Market Analysis, Insights and Forecast - by Service
8.3.1. Brokerage
8.3.2. Property Management
8.3.3. Appraisal
8.3.4. Development
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Property Type
9.1.1. Residential
9.1.2. Commercial
9.1.3. Industrial
9.1.4. Land
9.2. Market Analysis, Insights and Forecast - by Transaction Type
9.2.1. Sales
9.2.2. Rental
9.2.3. Lease
9.3. Market Analysis, Insights and Forecast - by Service
9.3.1. Brokerage
9.3.2. Property Management
9.3.3. Appraisal
9.3.4. Development
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Property Type
10.1.1. Residential
10.1.2. Commercial
10.1.3. Industrial
10.1.4. Land
10.2. Market Analysis, Insights and Forecast - by Transaction Type
10.2.1. Sales
10.2.2. Rental
10.2.3. Lease
10.3. Market Analysis, Insights and Forecast - by Service
10.3.1. Brokerage
10.3.2. Property Management
10.3.3. Appraisal
10.3.4. Development
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Brookfield Asset Management Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Mitsui Fudosan Co. Ltd.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Sun Hung Kai Properties Limited
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Prologis Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Simon Property Group Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. DLF Limited
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Godrej Properties Limited
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Oberoi Realty Limited
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Brigade Enterprises Limited
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Mitsubishi Estate Co. Ltd.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Sumitomo Realty & Development Co. Ltd.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Nomura Real Estate Holdings Inc.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Sekisui House Ltd.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Lendlease Group
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Mirvac Group
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Stockland Corporation Limited
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. China Vanke Co. Ltd.
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Country Garden Holdings Co. Ltd.
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. China Resources Land Limited
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Sunac China Holdings Limited
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Evergrande Group
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Vonovia SE
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. SEGRO plc
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Grainger plc
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Lennar Corporation
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Real Estate Industry Revenue Breakdown (Trillion, %) by Region 2026 & 2034
Figure 2: Asia-Pacific Real Estate Industry Revenue (Trillion), by Property Type 2026 & 2034
Figure 3: Asia-Pacific Real Estate Industry Revenue Share (%), by Property Type 2026 & 2034
Figure 4: Asia-Pacific Real Estate Industry Revenue (Trillion), by Transaction Type 2026 & 2034
Figure 5: Asia-Pacific Real Estate Industry Revenue Share (%), by Transaction Type 2026 & 2034
Figure 6: Asia-Pacific Real Estate Industry Revenue (Trillion), by Service 2026 & 2034
Figure 7: Asia-Pacific Real Estate Industry Revenue Share (%), by Service 2026 & 2034
Figure 8: Asia-Pacific Real Estate Industry Revenue (Trillion), by Country 2026 & 2034
Figure 9: Asia-Pacific Real Estate Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: North America Real Estate Industry Revenue (Trillion), by Property Type 2026 & 2034
Figure 11: North America Real Estate Industry Revenue Share (%), by Property Type 2026 & 2034
Figure 12: North America Real Estate Industry Revenue (Trillion), by Transaction Type 2026 & 2034
Figure 13: North America Real Estate Industry Revenue Share (%), by Transaction Type 2026 & 2034
Figure 14: North America Real Estate Industry Revenue (Trillion), by Service 2026 & 2034
Figure 15: North America Real Estate Industry Revenue Share (%), by Service 2026 & 2034
Figure 16: North America Real Estate Industry Revenue (Trillion), by Country 2026 & 2034
Figure 17: North America Real Estate Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Real Estate Industry Revenue (Trillion), by Property Type 2026 & 2034
Figure 19: Europe Real Estate Industry Revenue Share (%), by Property Type 2026 & 2034
Figure 20: Europe Real Estate Industry Revenue (Trillion), by Transaction Type 2026 & 2034
Figure 21: Europe Real Estate Industry Revenue Share (%), by Transaction Type 2026 & 2034
Figure 22: Europe Real Estate Industry Revenue (Trillion), by Service 2026 & 2034
Figure 23: Europe Real Estate Industry Revenue Share (%), by Service 2026 & 2034
Figure 24: Europe Real Estate Industry Revenue (Trillion), by Country 2026 & 2034
Figure 25: Europe Real Estate Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: South America Real Estate Industry Revenue (Trillion), by Property Type 2026 & 2034
Figure 27: South America Real Estate Industry Revenue Share (%), by Property Type 2026 & 2034
Figure 28: South America Real Estate Industry Revenue (Trillion), by Transaction Type 2026 & 2034
Figure 29: South America Real Estate Industry Revenue Share (%), by Transaction Type 2026 & 2034
Figure 30: South America Real Estate Industry Revenue (Trillion), by Service 2026 & 2034
Figure 31: South America Real Estate Industry Revenue Share (%), by Service 2026 & 2034
Figure 32: South America Real Estate Industry Revenue (Trillion), by Country 2026 & 2034
Figure 33: South America Real Estate Industry Revenue Share (%), by Country 2026 & 2034
Figure 34: Middle East & Africa Real Estate Industry Revenue (Trillion), by Property Type 2026 & 2034
Figure 35: Middle East & Africa Real Estate Industry Revenue Share (%), by Property Type 2026 & 2034
Figure 36: Middle East & Africa Real Estate Industry Revenue (Trillion), by Transaction Type 2026 & 2034
Figure 37: Middle East & Africa Real Estate Industry Revenue Share (%), by Transaction Type 2026 & 2034
Figure 38: Middle East & Africa Real Estate Industry Revenue (Trillion), by Service 2026 & 2034
Figure 39: Middle East & Africa Real Estate Industry Revenue Share (%), by Service 2026 & 2034
Figure 40: Middle East & Africa Real Estate Industry Revenue (Trillion), by Country 2026 & 2034
Figure 41: Middle East & Africa Real Estate Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Real Estate Industry Revenue Trillion Forecast, by Property Type 2020 & 2034
Table 2: Global Real Estate Industry Revenue Trillion Forecast, by Transaction Type 2020 & 2034
Table 3: Global Real Estate Industry Revenue Trillion Forecast, by Service 2020 & 2034
Table 4: Global Real Estate Industry Revenue Trillion Forecast, by Region 2020 & 2034
Table 5: Asia-Pacific Real Estate Industry Revenue Trillion Forecast, by Property Type 2020 & 2034
Table 6: Asia-Pacific Real Estate Industry Revenue Trillion Forecast, by Transaction Type 2020 & 2034
Table 7: Asia-Pacific Real Estate Industry Revenue Trillion Forecast, by Service 2020 & 2034
Table 8: Asia-Pacific Real Estate Industry Revenue Trillion Forecast, by Country 2020 & 2034
Table 9: China Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 10: India Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 11: Japan Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 12: Australia Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 13: Indonesia Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 14: South Korea Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 15: North America Real Estate Industry Revenue Trillion Forecast, by Property Type 2020 & 2034
Table 16: North America Real Estate Industry Revenue Trillion Forecast, by Transaction Type 2020 & 2034
Table 17: North America Real Estate Industry Revenue Trillion Forecast, by Service 2020 & 2034
Table 18: North America Real Estate Industry Revenue Trillion Forecast, by Country 2020 & 2034
Table 19: USA Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 20: Canada Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 21: Mexico Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 22: Europe Real Estate Industry Revenue Trillion Forecast, by Property Type 2020 & 2034
Table 23: Europe Real Estate Industry Revenue Trillion Forecast, by Transaction Type 2020 & 2034
Table 24: Europe Real Estate Industry Revenue Trillion Forecast, by Service 2020 & 2034
Table 25: Europe Real Estate Industry Revenue Trillion Forecast, by Country 2020 & 2034
Table 26: UK Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 27: Germany Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 28: France Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 29: Italy Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 30: Spain Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 31: South America Real Estate Industry Revenue Trillion Forecast, by Property Type 2020 & 2034
Table 32: South America Real Estate Industry Revenue Trillion Forecast, by Transaction Type 2020 & 2034
Table 33: South America Real Estate Industry Revenue Trillion Forecast, by Service 2020 & 2034
Table 34: South America Real Estate Industry Revenue Trillion Forecast, by Country 2020 & 2034
Table 35: Brazil Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 36: Chile Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 37: Argentina Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 38: Middle East & Africa Real Estate Industry Revenue Trillion Forecast, by Property Type 2020 & 2034
Table 39: Middle East & Africa Real Estate Industry Revenue Trillion Forecast, by Transaction Type 2020 & 2034
Table 40: Middle East & Africa Real Estate Industry Revenue Trillion Forecast, by Service 2020 & 2034
Table 41: Middle East & Africa Real Estate Industry Revenue Trillion Forecast, by Country 2020 & 2034
Table 42: Saudi Arabia Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 43: UAE Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 44: South Africa Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Table 45: Nigeria Real Estate Industry Revenue (Trillion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the global real estate industry market?
The global real estate industry market is valued at USD 4.74 Trillion in 2026, growing from USD 4.44 Trillion in 2025 at a 6.8% year-over-year rate, based on our proprietary primary research.
2What is the projected growth rate (CAGR) of the real estate industry market through 2030?
The market is projected to expand at a 7.2% CAGR from 2026 to 2030, reaching USD 6.26 Trillion by the end of the forecast period.
3Which region dominates the global real estate industry market?
Asia-Pacific is the largest region, accounting for an estimated 41% of global market value in 2025, driven by rapid urbanization and population growth in countries such as China, India, and Indonesia. North America follows with a 26% share.
4Who are the key companies operating in the real estate industry market?
Major players include Brookfield Asset Management, Mitsui Fudosan Co., Ltd., Sun Hung Kai Properties Limited, Prologis, Inc., Simon Property Group, Inc., Lennar Corporation, and China Vanke Co., Ltd., among others.
5What are the main drivers of the real estate industry market?
Key growth drivers include rising urbanization (82.7% of the U.S. population lives in urban areas), expanding construction activity (240,813 dwellings under construction in Australia in Q1 2023), economic growth, and increasing adoption of AI-driven property technologies.
6How are climate-related risks affecting the real estate industry market?
Climate-related disasters cost up to USD 430 Billion annually (0.5% of global GDP), and physical risks such as floods and wildfires are increasingly factored into property valuations and insurance premiums, creating financial risk transmission through credit, market, and underwriting channels, according to OECD data.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, encompassing direct engagement with developers, property managers, brokers, institutional investors, and technology providers across the real estate value chain.
We conduct semi-structured interviews with C-level executives, including Chief Investment Officers at REITs, Heads of Property Management at asset management firms, Directors of Construction at development companies, and Portfolio Managers at pension funds.
Surveys and expert panels are deployed across 25+ countries to capture granular data on transaction volumes, rental rates, occupancy levels, and pipeline projects.
Our analyst team conducts on-site visits to key developments and participates in industry roundtables to validate market dynamics and identify emerging trends.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Investment Officer / Portfolio Manager
30%
Head of Property Management
25%
Director of Construction & Development
25%
Real Estate Broker / Leasing Director
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Real Estate Developers & Builders
30%
REITs & Institutional Investors
25%
Property Management & Brokerage Firms
20%
Construction & Materials Suppliers
15%
PropTech & Technology Providers
10%
Secondary Research & Industry Benchmarking
20–30% of research effort is dedicated to rigorous secondary analysis, triangulating data from official multilateral sources including the OECD, World Bank, UN Comtrade, and Eurostat.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to analyze corporate filings, investment flows, and M&A activity.
All data is updated to the date of purchase, ensuring the latest available statistics and market intelligence are reflected.
Demand Modeling & Market Estimation
We employ top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up market sizing is constructed using specific quantitative metrics: (1) total square footage of residential and commercial stock by property type and quality tier, (2) average rental and lease rates per square foot, (3) transaction volumes and brokerage commissions, and (4) property management fee revenues.
Demand modeling incorporates macroeconomic variables such as GDP growth, employment rates, urbanization rates, interest rates, and construction activity indices to forecast market trajectories to 2030.
Segment-level forecasts are built using regression analysis on historical data (2020–2025) and scenario planning for base, optimistic, and conservative cases.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous validation protocols.
Multi-level data triangulation cross-verifies primary interview findings with secondary trade statistics and independent official benchmarks.
All market size estimates are subjected to sensitivity analysis and margin-of-error testing to ensure robustness.
Our quality assurance team conducts peer review of all models, and final outputs are audited against historical forecast accuracy to maintain continuous improvement.