1What is the current size of the ready-to-cook food market?
The global ready-to-cook food market was valued at USD 209 billion in 2023 and is projected to reach USD 430 billion by 2033, growing at a CAGR of 7.5%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Ready to Cook Food Market
 by Type (Frozen Foods, Instant Noodles, Instant Pasta, Instant Soup, Ready-To-Mix, Others), by Packaging (Boxes, Bags, Pouches, Cans, Trays, Others), by End-User (Households, Food Service Industry, Others), by Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Online Retailers, Specialty Stores, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, Australia, South Korea, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034

Research Associate


 Related Reports

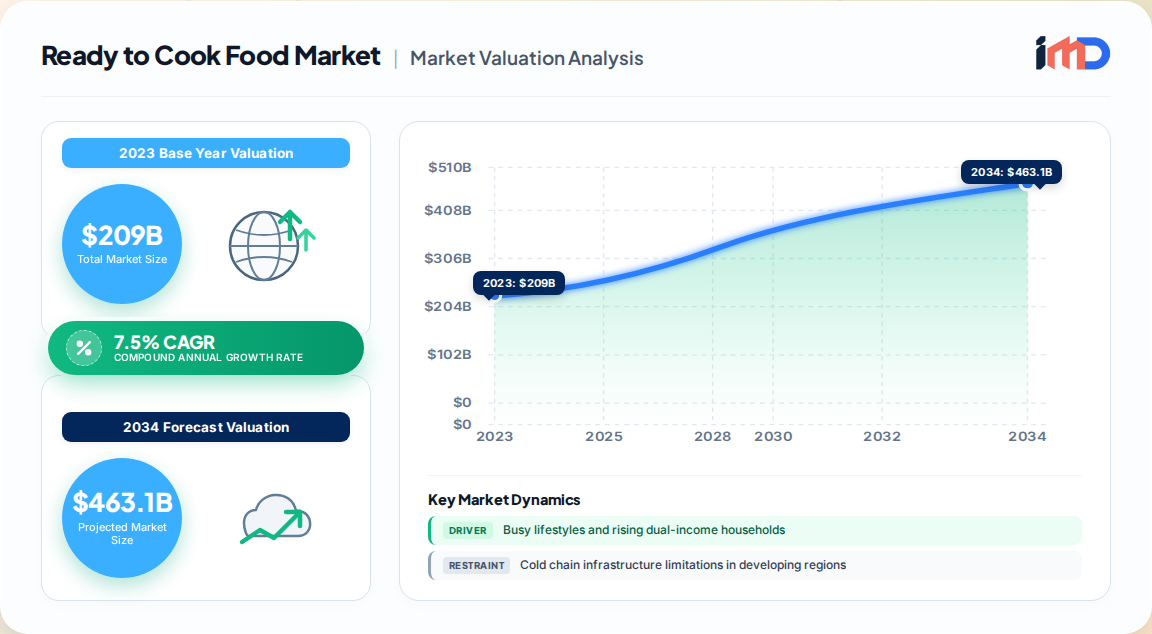
The global ready-to-cook (RTC) food market represents a dynamic and rapidly evolving segment of the food industry, characterized by products that are partially prepared and require minimal cooking or heating before consumption. Our proprietary primary research estimates the market at USD 209 billion in 2023, with a projected valuation of USD 430 billion by 2033, expanding at a robust CAGR of 7.5%. This growth is underpinned by shifting consumer lifestyles, urbanization, and an increasing demand for convenience without compromising on taste or nutritional value. The market encompasses a diverse range of product types, including frozen foods, instant noodles, instant pasta, instant soup, and ready-to-mix offerings, catering to both household and food service end-users.
The RTC food value chain is complex, involving multiple stakeholders from raw material sourcing to final consumption. Key stages include:
The RTC food market is increasingly globalized, with significant trade flows of frozen and shelf-stable products. According to UN Comtrade data, global exports of frozen prepared meals and instant noodles have grown steadily, driven by demand from North America and Europe. However, supply chain risks persist:
Asia-Pacific commands the largest share at 35% in 2023, driven by rapid urbanization, a large base of young consumers, and the popularity of instant noodles and frozen foods. The region is also the fastest-growing, with a projected CAGR of 7.5% through 2035. China and India are key markets, supported by expanding modern retail and e-commerce.
North America holds a significant share of 35%, with a mature market characterized by high consumption of frozen meals and meal kits. The presence of major players and advanced cold chain infrastructure supports growth, although the market is nearing saturation, leading to a focus on premium and health-oriented products.
Europe represents a substantial market, with countries like the UK and Germany leading in RTC consumption. The region is witnessing a shift towards sustainable packaging and plant-based options, driven by regulatory pressures and consumer demand for clean-label products.
These regions are emerging markets with growing demand for convenient foods. However, cold chain challenges and lower purchasing power may temper growth. Nevertheless, urbanization and changing dietary habits present opportunities for market expansion.
The RTC food market is highly competitive, with key players employing strategies such as product innovation, mergers and acquisitions, and geographic expansion. Notable developments include:
Several untapped opportunities exist in the RTC food market:
For manufacturers and retailers, effective procurement strategies are critical to maintaining cost competitiveness and quality:
The global ready-to-cook food market is poised for significant growth, driven by convenience trends, retail expansion, and product innovation. However, challenges related to cold chain infrastructure and regulatory compliance must be addressed. Stakeholders across the value chain can capitalize on opportunities in health-oriented and sustainable products to gain a competitive edge.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2023 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.5% from 2020-2034 |
| Segmentation |
|
By Packaging
By End-User
By Distribution Channel
| By Geography |
|
The global ready-to-cook food market was valued at USD 209 billion in 2023 and is projected to reach USD 430 billion by 2033, growing at a CAGR of 7.5%.
Asia-Pacific holds the largest share at approximately 35% in 2023, driven by urbanization and high demand for instant noodles and frozen foods. North America follows closely with a 35% share.
Key drivers include busy lifestyles, rising dual-income households, expansion of modern retail and e-commerce, and product innovation focused on health and convenience.
Challenges include cold chain infrastructure limitations in developing regions, regulatory scrutiny over ultra-processed foods, and consumer skepticism about additives and preservatives.
Supermarkets and hypermarkets lead with a 46.3% share in 2023, while online retail is the fastest-growing channel with a projected CAGR of 6.8% through 2035.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Supply Chain Manager | 25% |
| Marketing Director | 20% |
| R&D Manager | 15% |
| CEO/President | 10% |
| Company Type | Representation (%) |
|---|---|
| RTC Food Manufacturers | 35% |
| Packaging Suppliers | 20% |
| Distributors and Retailers | 25% |
| Food Service Providers | 15% |
| Regulatory Experts | 5% |