1What is the projected size of the PVC Emulsion Market by 2035?
The market is projected to reach USD 16.32 Billion by 2035, growing at a CAGR of 3.02% from USD 12.12 Billion in 2025.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 PVC Emulsion Market
 by Application (Paints & Coatings, Adhesives & Sealants, Paper & Paperboard, Textiles, Others), by End-User Industry (Construction, Automotive, Packaging, Furniture, Others), by Grade (General-Purpose, High-Performance, Specialty), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia), by Asia Pacific (China, Japan, India, South Korea, Indonesia, Malaysia, Australia), by South America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034

Senior Analyst


 Related Reports

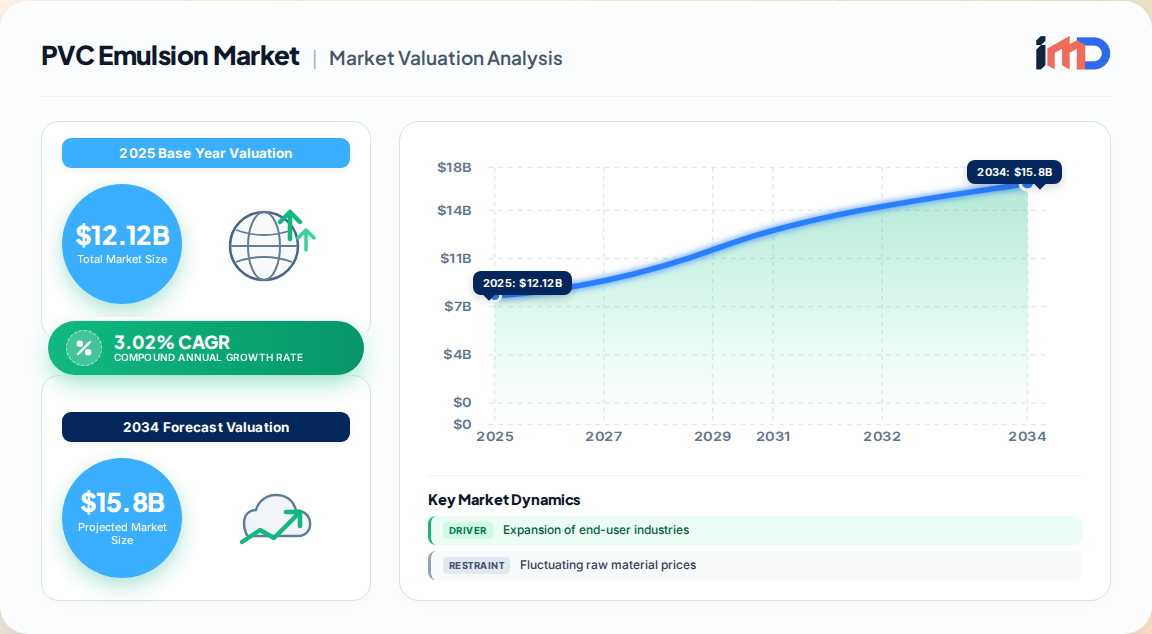
The global PVC Emulsion Market represents a specialized yet strategically vital segment of the polyvinyl chloride industry, characterized by the production of fine-particle resins via emulsion and micro-suspension polymerization. Our proprietary primary research estimates the market at USD 12.12 Billion in 2025, with a projected expansion to USD 16.32 Billion by 2035, reflecting a steady CAGR of 3.02% over the forecast period. Emulsion-grade PVC, accounting for approximately 10% of global PVC resin volume, commands a premium price point due to its unique plastisol-forming capabilities, high purity, and superior film-forming properties. These characteristics render it indispensable in applications requiring flexibility, durability, and aesthetic finish, such as synthetic leather, flooring, wall coverings, and automotive sealants.
Despite facing headwinds from raw material volatility and stringent environmental regulations, the market demonstrates resilient growth fundamentals. The construction sector remains the largest end-user, while the automotive and packaging industries are emerging as high-velocity growth vectors. Geographically, Asia-Pacific is the dominant and fastest-growing region, underpinned by rapid urbanization and infrastructure investment, while North America and Europe maintain significant shares driven by technological innovation and sustainability imperatives.
The PVC emulsion value chain is characterized by a complex network of raw material suppliers, specialized manufacturers, and diverse end-users. Upstream, the supply of vinyl chloride monomer (VCM) is dominated by large petrochemical conglomerates, whose production economics are closely tied to ethylene and chlorine prices. Emulsion polymerization, conducted in aqueous systems with surfactants and initiators, is more energy-intensive than suspension polymerization, resulting in a premium product.
Downstream, PVC emulsion manufacturers formulate resins into plastisols, organosols, and compounds tailored to specific applications. These formulations are supplied to converters and end-users in the construction, automotive, textile, and packaging sectors. Strategic partnerships and long-term contracts between resin producers and raw material suppliers are common to mitigate price volatility and ensure supply security.
Trade flows for PVC emulsion are shaped by regional production capacities and consumption patterns. Asia-Pacific, particularly China, is a net exporter of emulsion PVC, while North America and Europe maintain balanced trade with a focus on high-performance grades. Recent supply chain disruptions, exacerbated by geopolitical tensions and logistical bottlenecks, have prompted manufacturers to diversify sourcing and increase regional self-sufficiency. The Red Sea shipping crisis and ongoing trade tensions have elevated freight costs and extended lead times, underscoring the importance of supply chain resilience. Key risks include raw material price volatility, regulatory changes, and potential trade barriers.
The PVC Emulsion Market is segmented by application, end-user industry, grade, and geography. Paints & coatings represent the largest application segment, while adhesives & sealants are projected to grow at the fastest rate. Construction is the dominant end-user industry, whereas automotive is expected to witness accelerated demand. General-purpose grade holds the largest share, but high-performance and specialty grades are gaining traction due to their superior properties.
| Segment | Sub-Segment | Market Position |
|---|---|---|
| By Application | Paints & Coatings | Largest |
| Adhesives & Sealants | Fastest-Growing | |
| Paper & Paperboard | Mature | |
| Textiles | Growing | |
| By End-User Industry | Construction | Largest |
| Automotive | Fastest-Growing | |
| Packaging | Steady | |
| Furniture | Moderate | |
| By Grade | General-Purpose | Largest |
| High-Performance | Fastest-Growing | |
| Specialty | Niche |
Major global players include BASF SE, Dow Inc., SABIC, Wacker Chemie AG, Arkema S.A., Huntsman Corporation, Mitsubishi Chemical Corporation, Solvay S.A., Clariant AG, Shin-Etsu Chemical Co. Ltd., Westlake Corporation, Formosa Plastics Corporation, LG Chem Ltd., INEOS Group, Reliance Industries Limited, Kem One, Hanwha Solutions, Vinnolit GmbH, Xinjiang Zhongtai Chemical, Tianjin Dagu Chemical, Tosoh Corporation, China National Chemical Corporation (ChemChina), Shintech Incorporated, Orbia Advance Corporation, Occidental Chemical Corporation, SCG Chemicals, and Anhui Conch Group. Competitive strategies revolve around capacity expansion, product innovation, and sustainability initiatives.
Asia-Pacific leads the market, accounting for an estimated 41% share in 2025, driven by China's construction boom and India's infrastructure push. North America and Europe follow with shares of 27% and 24%, respectively, supported by technological advancements and renovation activities. South America and the Middle East & Africa represent smaller but emerging markets, with opportunities in infrastructure development and automotive production. Investment attractiveness is highest in Asia-Pacific due to low production costs and growing demand, while North America and Europe offer opportunities in high-value, eco-friendly products.
Significant white-space opportunities exist in the development of bio-based and low-VOC PVC emulsions, particularly for packaging and automotive interior applications. The shift toward circular economy principles presents potential for recycling and upcycling of PVC emulsion waste. Additionally, untapped markets in Africa and South America offer growth potential for cost-effective, general-purpose PVC emulsions in construction and infrastructure projects.
Procurement strategies for PVC emulsion should prioritize supply security and cost optimization. Buyers are advised to:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.02% from 2020-2034 |
| Segmentation |
|
By Grade
| By Geography |
|
The market is projected to reach USD 16.32 Billion by 2035, growing at a CAGR of 3.02% from USD 12.12 Billion in 2025.
Asia-Pacific is the largest and fastest-growing region, holding an estimated 41% market share in 2025, driven by construction and automotive demand.
Major applications include paints & coatings, adhesives & sealants, synthetic leather, flooring, wall coverings, and automotive sealants.
Key players include BASF SE, Dow Inc., Westlake Corporation, Shin-Etsu Chemical, and Formosa Plastics, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| R&D Manager | 25% |
| Plant Operations Manager | 25% |
| Sustainability Officer | 20% |
| Company Type | Representation (%) |
|---|---|
| PVC Resin Manufacturers | 35% |
| Plastisol Formulators | 25% |
| Synthetic Leather Producers | 20% |
| Flooring Manufacturers | 12% |
| Automotive Sealant Suppliers | 8% |