1What is the PropTech market size in 2026?
The global PropTech market is estimated at USD 53.24 billion in 2026, up from USD 45.20 billion in 2025. It is projected to reach USD 120.74 billion by 2031, growing at a 17.79% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 PropTech Market
 by Property Type (Residential, Commercial, Industrial and Logistics, Hospitality), by Solution (Software, Services), by Deployment (Cloud, On-Premise, Hybrid), by End-User (Property Owners and Developers, Real-Estate Agents and Brokerages, Facility Managers, Housing Associations, Investors, Tenants), by Technology (IoT and Smart-Sensor Networks, AI/Big-Data Analytics, AR/VR and Digital Twins, Blockchain), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, Australia), by South America (Brazil, Argentina), by Middle East & Africa (GCC, South Africa) Forecast 2026-2034

Research Analyst

 Related Reports

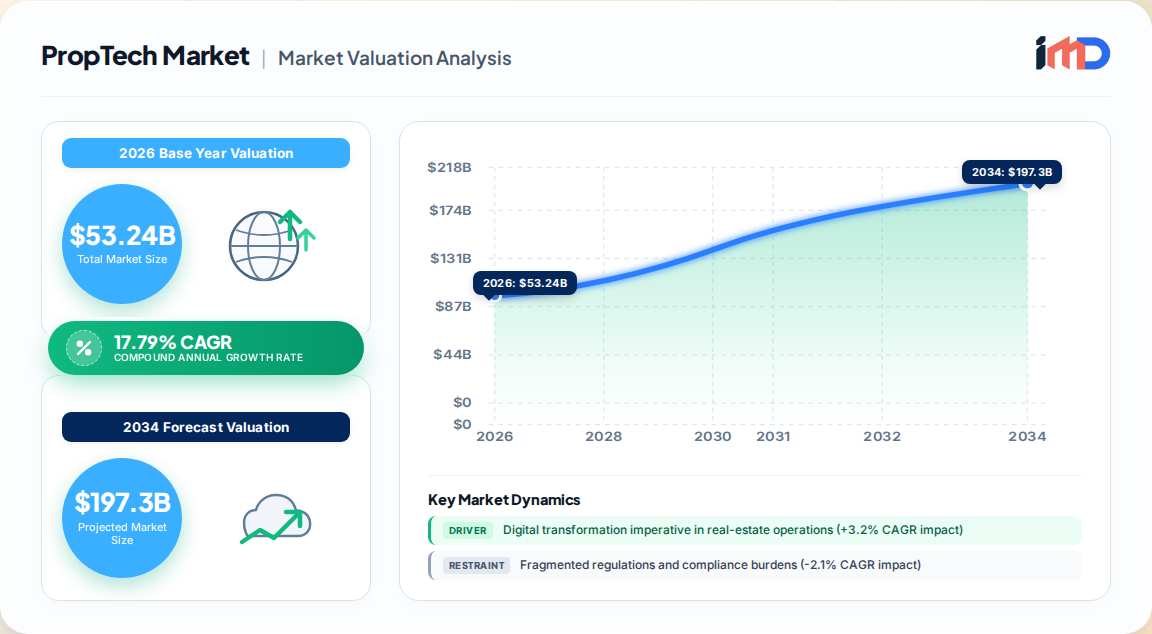
The global PropTech market is undergoing a structural re-rating. Our proprietary primary research and expert interview program estimates the market at USD 53.24 billion in 2026, expanding from USD 45.20 billion in 2025 and on track to reach USD 120.74 billion by 2031, implying a 17.79% CAGR over the forecast window. This is not a cyclical rebound but a durable platform shift: property technology has moved from a point-solution experimentation phase into the core operating infrastructure of real-estate ownership, development, and management.
Three forces define the current cycle. First, institutional capital has become decisive: dedicated PropTech vehicles attracted more than USD 1.1 billion in fresh commitments during 2024, with growth-stage funding now eclipsing seed activity. Second, regulatory compulsion has arrived in force, most visibly through New York City's Local Law 97 and the EU Energy Performance of Buildings Directive, converting ESG analytics from discretionary spend into capital-protection necessity. Third, the connected building has become economically self-justifying: integrated building-management and analytics platforms reliably cut operating costs by up to 30%, with documented energy-consumption reductions of 20-35% versus conventionally managed properties.
| Metric | 2026 Value | 2031 Projection |
|---|---|---|
| Global market size | USD 53.24 billion | USD 120.74 billion |
| Forecast CAGR (2026-2031) | 17.79% | - |
| Largest region | North America (36.29% share, 2025) | - |
| Fastest-growing region | Asia-Pacific | 15.02% CAGR |
| Leading property segment | Commercial (54.98% share, 2025) | - |
| Leading solution segment | Software (66.85% share, 2025) | - |
| Leading deployment model | Cloud (77.35% share, 2025) | - |
| Market concentration | Medium | - |
Our driver-impact modeling quantifies the contribution of each growth vector to the forecast CAGR, drawing on more than 40 expert interviews across owners, operators, and technology vendors.
| Driver | CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Digital transformation of real-estate operations | +3.2% | Global; North America and Europe leading | Medium term (2-4 yrs) |
| Rapid adoption of smart and connected buildings | +2.8% | Global, concentrated in developed markets | Short term (≤2 yrs) |
| Rising institutional real-estate fund investment | +2.1% | North America, Europe, APAC core markets | Medium term (2-4 yrs) |
| Mandatory ESG data-reporting | +1.9% | Europe and North America, expanding to APAC | Long term (≥4 yrs) |
| Insurance-backed rent-guarantee platforms | +1.4% | North America and Europe | Medium term (2-4 yrs) |
| Digital twins in zoning-approval processes | +1.1% | Global; early smart-city adoption | Long term (≥4 yrs) |
The digital transformation imperative is the single largest multiplier. AI-driven leasing engines improve lead-to-lease conversions by 85%, fundamentally reshaping marketing and tenant-management economics. PropTech platforms now act as a control hub, unifying energy, occupancy, and tenant-communication data on a single dashboard to unlock portfolio-wide optimization.
Smart buildings have crossed from perk to necessity. Modern commercial structures integrate more than 8,000 real-time data points covering air quality, occupancy, and equipment health. Automated energy controls slash utility expenses and improve sustainability ratings required for green financing. JLL's PropTech investment tracking identifies occupant-experience platforms and predictive building analytics as the fastest-growing technology segments in commercial real estate, with investment up 47% year on year.
Restraints are material but bounded. Fragmented regulations and compliance burdens impose a -2.1% drag on CAGR, particularly in Europe and Asia-Pacific, where data-protection, tenant-rights, and building-safety rules diverge across jurisdictions. Cybersecurity and data-privacy concerns subtract -1.8%, with stricter enforcement in Europe and California. Land-registry data quality hinders blockchain pilots (-1.2%, primarily emerging markets), while escalating cloud-usage fees squeeze SaaS unit economics (-0.9%). High implementation and technology-integration costs remain a structural barrier for legacy building stock and smaller operators.
Segment-level data reveals a market whose center of gravity is shifting from software licenses toward recurring, outcome-based services.
| Segment | Leading Share (2025) | Fastest-Growing Sub-Segment | Sub-Segment CAGR |
|---|---|---|---|
| Property type | Commercial (54.98%) | Industrial & logistics | 16.92% |
| Solution | Software (66.85%) | Services | 16.15% |
| Deployment | Cloud (77.35%) | Hybrid | 20.10% |
| End-user | Property owners (37.15%) | Facility managers | 18.05% |
| Technology | IoT & sensors (40.88%) | AR/VR & digital twins | 23.05% |
Commercial assets dominate current spend because building-management analytics deliver the most measurable ROI at portfolio scale. However, industrial and logistics is the fastest-expanding property vertical at 16.92% CAGR, driven by warehouse automation and the capital intensity of modern logistics assets. By solution, software platforms command 66.85% of value, but services are growing at 16.15% CAGR as outcome-based service models reshape vendor revenue streams.
Deployment economics are unambiguous: cloud models secured 77.35% of market value in 2025, with 78% of users favoring the scalability and anytime-access benefits of SaaS architectures. Hybrid deployment, at 20.10% CAGR, is the fastest-growing model as enterprises balance data-sovereignty requirements against cloud flexibility. The European market's emphasis on EU data residency, including Frankfurt-hosted processing infrastructure and EU Standard Contractual Clauses, is a direct demand signal for hybrid and sovereign-cloud configurations.
By end-user, property owners held 37.15% of value in 2025, yet facility managers lead growth at 18.05% CAGR as operational analytics move from head-office dashboards to on-site decision workflows. Technology segmentation confirms the IoT foundation: IoT and smart-sensor networks contributed 40.88% of value, while AR/VR and digital twins are advancing fastest at 23.05% CAGR, underpinned by smartphone-based 3D spatial capture, Gaussian Splatting reconstruction, and floor-plan automation that now embed directly into broker and valuation software.
North America led with 36.29% of global PropTech value in 2025, supported by deep institutional capital, mature REIT structures, and aggressive state-level ESG mandates. The U.S. remains the single largest country market, with AI-driven valuation and iBuying models setting global product benchmarks.
Asia-Pacific is the fastest-growing region at 15.02% CAGR through 2031, propelled by urbanization, smart-city investment programs, and greenfield digital infrastructure that avoids legacy-integration costs. Europe holds a structurally important position: the EU Energy Performance of Buildings Directive, combined with national carbon caps, has made building-performance analytics a procurement requirement rather than an option. Rental premiums of 7-15% for certified sustainable assets and vacancy-rate reductions of 40-50% versus conventional buildings underwrite the investment case.
| Region | 2025 Share | Growth Profile | Primary Demand Catalyst |
|---|---|---|---|
| North America | 36.29% | Mature, high-value | Institutional capital, Local Law 97 |
| Europe | ~24.5% | Compliance-led | EPBD, GRESB/SFDR disclosure |
| Asia-Pacific | ~28.2% | 15.02% CAGR, fastest | Smart cities, urbanization |
| South America | ~6.0% | Emerging | Fintech-enabled transactions |
| Middle East & Africa | ~5.0% | Early-stage | Gulf megaprojects, digitization |
The PropTech market exhibits medium concentration, with no single vendor controlling end-to-end workflows. Competition is organized around four strategic archetypes:
Consolidation is accelerating. The institutional investment wave is enabling well-capitalized players to acquire niche specialists and assemble full-stack solutions, reducing perceived adoption risk for cautious owners. Growth-stage capital now favors firms with proven unit economics addressing ESG compliance, energy efficiency, and tenant experience. Recent development activity includes Brigade Group and Gruhas launching an INR 300 crore Earth Fund (with an INR 100 crore green shoe option) to foster real-estate technology and sustainability startups, and InovaReal securing USD 270,000 in pre-seed funding for its mobile-first digital brokerage platform.
The PropTech value chain is compressing. Historically fragmented across hardware vendors, software vendors, integrators, and service bureaus, it is now consolidating into platform ecosystems that own the customer relationship.
A critical shift is the move toward embeddable infrastructure. Rather than directing users to third-party capture applications, platforms now embed spatial-capture functionality natively into their own iOS and Android apps, retaining the customer relationship and converting a cost center into a recurring revenue line. Non-exclusive licensing, portable export formats, and configurable data-ownership terms are becoming standard procurement requirements to prevent vendor lock-in.
Our opportunity assessment identifies five under-penetrated zones with asymmetric upside through 2031:
Risk factors warrant disciplined monitoring. Fragmented regulation (-2.1% CAGR drag) will slow cross-border scaling; cybersecurity and privacy concerns (-1.8%) will raise compliance costs; and cloud-fee escalation (-0.9%) will pressure gross margins for single-tenant SaaS providers. Vendors that combine regulatory-grade data governance, demonstrable ROI, and open, non-lock-in architectures are best positioned to capture the next leg of the 17.79% CAGR expansion.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.79% from 2020-2034 |
| Segmentation |
|
By Deployment
By End-User
By Technology
| By Geography |
|
The global PropTech market is estimated at USD 53.24 billion in 2026, up from USD 45.20 billion in 2025. It is projected to reach USD 120.74 billion by 2031, growing at a 17.79% CAGR.
North America led with a 36.29% share of the global PropTech market in 2025, supported by deep institutional capital and stringent ESG mandates like New York City's Local Law 97. Asia-Pacific is the fastest-growing region at a 15.02% CAGR through 2031.
Digital transformation of real-estate operations (+3.2% CAGR impact), smart and connected building adoption (+2.8%), institutional fund investment (+2.1%), and mandatory ESG data-reporting (+1.9%) are the principal growth catalysts. Integrated building-management platforms can cut operating costs by up to 30%.
Cloud deployment dominates, securing 77.35% of the market in 2025, as 78% of users favor SaaS scalability and anytime access. Hybrid deployment is the fastest-growing model at a 20.10% CAGR through 2031, driven by data-sovereignty requirements.
Leading players include CoStar Group Inc., RealPage Inc., Opendoor Technologies Inc., Procore Technologies Inc., Matterport Inc., Altus Group, Zumper Inc., Zillow Inc., Guesty Inc., and VergeSense, spanning data marketplaces, property management, transaction fintech, and smart-building analytics.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 30% |
| Head of Property Management | 25% |
| Director of Sustainability and ESG | 20% |
| VP of Asset Management | 15% |
| Chief Operating Officer | 10% |
| Company Type | Representation (%) |
|---|---|
| PropTech platform and SaaS vendors | 38% |
| Smart-building IoT and hardware OEMs | 22% |
| Real estate brokers and property managers | 20% |
| Institutional investors and REITs | 12% |
| Cloud infrastructure and spatial-capture SDK providers | 8% |