Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
PPDI Type Polyurethane Elastomer Market | 6.5% CAGR to 2033
PPDI Type Polyurethane Elastomer Market
Chemicals & Materials / MARKET REPORT
PPDI Type Polyurethane Elastomer Market | Insight Market Data
PPDI Type Polyurethane Elastomer Market by By Form (Solid Elastomers, Liquid Elastomers, Foam Elastomers), by By Processing Technology (Injection Molding, Extrusion, Casting, Others), by By End-Use Industry (Automotive, Industrial Manufacturing, Healthcare, Consumer Goods, Aerospace & Defense, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia-Pacific (China, Japan, South Korea, India, Rest of Asia-Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
The raw materials for personal care market is set to grow at a 6.1% CAGR, reaching $27.1B by 2033, driven by natural and sustainable ingredient demand.
Nov 2026|250 pages
$2900.00
High Speed Digital CCL market valued at $1.26B in 2025, growing at 5.1% CAGR to reach $2.07B by 2035. Rising demand from 5G, data centers, and automotive electronics.
Nov 2026|206 pages
$2900.00
SSAW steel pipe market valued at USD 6.5 Billion in 2025, projected to reach USD 10.71 Billion by 2034 at a 5.71% CAGR driven by oil, gas and water infrastructure.
Nov 2026|180 pages
$2900.00
Composite resin tooth filling material market to reach $2.1B by 2035 at 5.2% CAGR, driven by aesthetic dentistry and nanohybrid innovations.
Executive Overview: A High-Performance Elastomer Poised for Accelerated Adoption
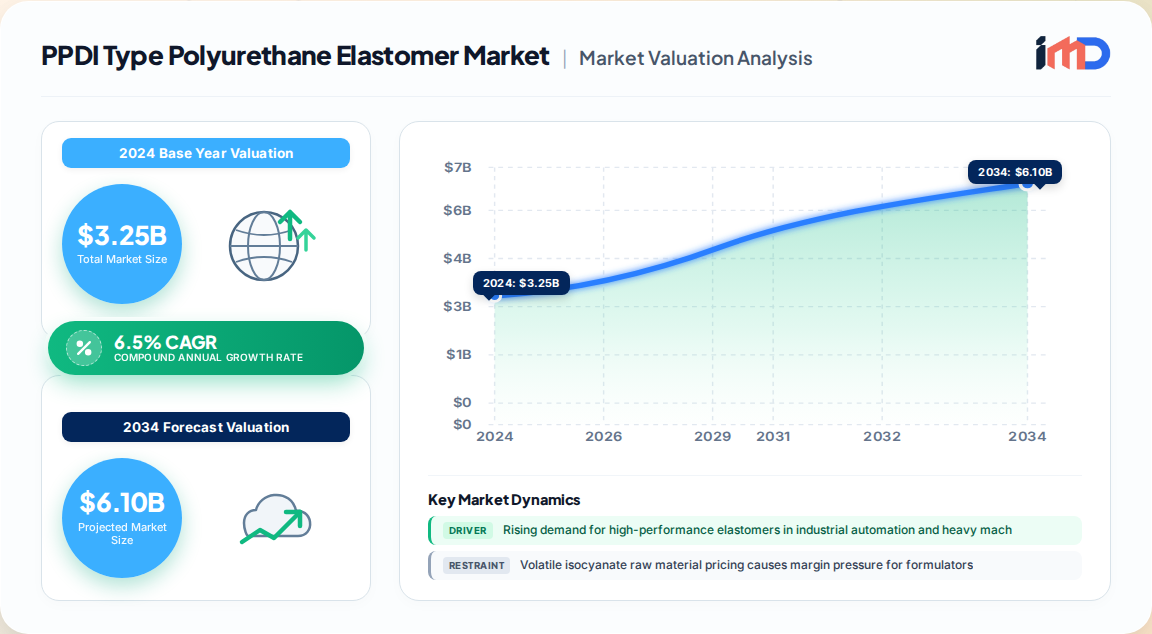
The global PPDI (p-phenylene diisocyanate) type polyurethane elastomer market represents a specialized, high-value segment within the broader polyurethane landscape. Our proprietary primary research and expert interviews estimate the market at USD 3.25 billion in 2024, with a projected expansion to USD 5.67 billion by 2033, reflecting a robust CAGR of 6.5% . This growth is fundamentally anchored in the material's unique molecular architecture, which delivers exceptional tear resistance, outstanding low-temperature flexibility, and superior hydrolysis resistance compared to conventional MDI- and TDI-based systems. These properties make PPDI elastomers indispensable in extreme-demand applications across industrial machinery, automotive, aerospace, and medical devices.
PPDI Type Polyurethane Elastomer Market Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.461 B
2025
3.686 B
2026
3.926 B
2027
4.181 B
2028
4.453 B
2029
4.742 B
2030
5.050 B
2031
The market's trajectory is being reshaped by a confluence of macro-industrial trends. The global push toward electrification, automation, and lightweighting is creating new performance thresholds that legacy materials struggle to meet, thereby accelerating the substitution of traditional rubbers and engineering thermoplastics with PPDI-based formulations. Furthermore, the increasing regulatory scrutiny on volatile isocyanate emissions in Europe and North America is paradoxically favoring PPDI systems, which, due to their solid state at room temperature and lower vapor pressure, present a safer handling profile for formulators.
Market Size (2024): USD 3.25 Billion
Forecast (2033): USD 5.67 Billion
CAGR (2025–2033): 6.5%
Largest End-Use Segment: Industrial Machinery (~35% of consumption)
The PPDI elastomer market is propelled by a set of interconnected demand drivers that are intensifying across high-growth verticals. However, this expansion is not without headwinds, primarily related to raw material volatility and regulatory compliance costs.
Drivers
Electrification of Automotive Systems: The transition to electric vehicles (EVs) demands elastomeric components capable of withstanding higher operating temperatures, providing electrical insulation, and delivering superior fatigue resistance in battery housings, charging infrastructure, and drivetrain mounts. PPDI elastomers outperform conventional materials in these harsh environments.
Industrial Automation & Heavy Machinery: The global race to automate manufacturing and logistics is driving demand for high-load vibration damping, precision rollers, and wear-resistant seals. PPDI's exceptional dynamic load-bearing capacity and low compression set are critical for automated guided vehicles (AGVs), conveyor systems, and robotic joints.
Aerospace & Defense Lightweighting: Aerospace OEMs are increasingly specifying PPDI elastomers for sealing, vibration isolation, and structural components where weight reduction and fuel efficiency are paramount. The material's ability to maintain flexibility at extreme low temperatures (-40°C and below) is a decisive advantage.
Medical Device Miniaturization & Biocompatibility: The expanding medical device industry requires sterilizable, biocompatible elastomers with high mechanical strength for components like catheter tips, seals, and wearable device housings. PPDI grades offer a superior balance of properties for these critical applications.
Restraints
Volatile Isocyanate Pricing: While PPDI is a specialty isocyanate, its price is influenced by the broader aromatic isocyanate market, which has experienced 25–40% price swings between 2021 and 2024 due to petrochemical feedstock volatility and supply chain disruptions. This creates margin pressure for formulators.
Regulatory Pressure on Di-isocyanates: EU REACH restrictions on di-isocyanates (effective August 2023) mandate certified training for workers handling MDI and TDI, and while PPDI's solid form mitigates some risks, the compliance burden and potential future restrictions add a layer of regulatory risk and cost.
Competition from Advanced TPEs: Advanced thermoplastic elastomers, such as PEBA and TPU alloys, are making inroads in premium medical tubing and performance footwear, offering competitive flexibility and recyclability, thereby constraining PPDI market share in certain niche applications.
Segmentation Analysis: Forms, Processing, and End-Use
The PPDI type polyurethane elastomer market is segmented by form, processing technology, and end-use industry, revealing a landscape where industrial manufacturing and automotive sectors dominate current consumption, while healthcare and consumer goods represent emerging frontiers.
Segment
Sub-Segment
Market Share (2024 est.)
Key Dynamics
By Form
Solid Elastomers
~65%
Dominant due to high-performance cast parts; used in rollers, seals, and wheels.
Liquid Elastomers
~25%
Growing in coatings, adhesives, and RIM applications.
Foam Elastomers
~10%
Niche applications in comfort and acoustic damping.
By Processing
Injection Molding
~40%
Preferred for high-volume TPU parts; fastest growth due to automation.
Extrusion
~25%
Used for profiles, tubing, and belts.
Casting
~30%
Critical for large, complex parts in industrial machinery.
Others (RIM, 3D Printing)
~5%
Emerging, with 3D printing enabling rapid prototyping.
By End-Use
Industrial Manufacturing
~35%
Largest segment; driven by automation and material handling.
Automotive
~28%
Growing with EV adoption and lightweighting.
Aerospace & Defense
~22%
High-value, performance-critical applications.
Medical Devices
~15%
Fastest-growing due to biocompatibility and sterilization resistance.
Segment Insights:
The Industrial Manufacturing segment's dominance is underpinned by the material's superior abrasion resistance and load-bearing capacity, which extend equipment lifespan in mining, oil and gas, and factory automation.
The Automotive segment is undergoing a renaissance, with PPDI elastomers increasingly specified for EV battery pack seals, thermal management components, and suspension bushings, where traditional rubber fails under higher temperatures and dynamic loads.
The Medical Devices segment, though smaller in absolute volume, commands premium pricing and exhibits the highest growth potential, fueled by an aging population and the proliferation of minimally invasive surgical tools.
Regional Outlook: Asia-Pacific Leads, North America and Europe Focus on Innovation
Geographic demand distribution reflects both manufacturing footprints and technological leadership.
PPDI Type Polyurethane Elastomer Market Regional Market Share
Loading chart...
Region
Market Share (2024)
Key Characteristics
Asia-Pacific
~45%
Manufacturing powerhouse (China, Japan, South Korea); rapid industrialization and automotive production drive volume growth.
North America
~28%
Mature but innovation-driven; strong aerospace/defense and medical device sectors; reshoring trends support demand.
Europe
~19%
Focus on sustainability and high-performance applications; stringent regulations favor PPDI's safer profile.
South America
~4%
Emerging market with growth in mining and oil & gas; Brazil and Argentina lead.
Middle East & Africa
~4%
Infrastructure spending and oil & gas exploration create niche opportunities.
Asia-Pacific remains the engine of growth, accounting for nearly half of global consumption. China's massive automotive and industrial machinery output, coupled with government-backed infrastructure spending exceeding USD 1.8 trillion through 2030, ensures sustained demand. Japan and South Korea contribute high-value segments, particularly in electronics and precision machinery.
North America benefits from a robust aerospace and defense sector, where PPDI elastomers are specified for critical sealing and vibration isolation applications. The region also leads in medical device innovation, with the U.S. accounting for a significant share of high-performance polymer R&D.
Europe is at the forefront of regulatory reform, with the EU's Chemicals Strategy for Sustainability driving demand for low-VOC, recyclable elastomer systems. This regulatory push is expected to accelerate the adoption of PPDI-based formulations that offer a safer handling profile than traditional isocyanates.
Competitive Landscape & Strategic Developments
The PPDI type polyurethane elastomer market is characterized by a moderately consolidated structure, with leading chemical multinationals and specialized formulators competing on technology, application expertise, and supply chain integration.
Key Players:
Covestro AG: A global leader in polyurethane raw materials, Covestro offers a broad portfolio of PPDI-based prepolymers and TPU grades, with a strong focus on automotive and industrial applications.
BASF SE: Through its Elastollan and Cellasto brands, BASF provides high-performance PPDI elastomers for vibration damping and lightweighting, underpinned by significant R&D investments.
Huntsman Corporation: Specializes in MDI and TDI-based systems but has developed PPDI-based specialty elastomers for demanding applications in oil and gas and industrial machinery.
Lubrizol Corporation: Offers Estane TPU grades, including PPDI-based formulations, targeting medical, automotive, and industrial markets.
Wanhua Chemical Group: China's largest polyurethane producer, with vertically integrated PPDI production and a growing global footprint.
Tosoh Corporation: A key supplier of PPDI and related specialty isocyanates, serving the Japanese and Asian markets.
Mitsui Chemicals: Produces PPDI-based elastomers for automotive and industrial applications, with a focus on high-performance grades.
Era Polymers: Australian specialty formulator with a strong presence in mining and industrial applications.
Strategic Developments (2023–2025):
2024: BASF announced a EUR 100 million investment in a new Cellasto plant in India, scheduled to begin operations in 2026, to meet growing demand for NVH (noise, vibration, harshness) components in the Asia-Pacific automotive market.
2023: Covestro expanded its TPU production capacity in Shanghai, China, to meet regional demand for high-performance elastomers in automotive and industrial applications.
2024: Huntsman introduced a new line of PPDI-based elastomers for oil and gas seals, offering improved resistance to sour gas and high temperatures.
2025: Wanhua Chemical announced plans to double its PPDI production capacity by 2027, citing strong demand from the EV and industrial automation sectors.
Import/Export & Supplier Dynamics
Global trade in PPDI type polyurethane elastomers is shaped by the location of raw material production, the technical expertise of formulators, and the demand centers of end-use industries. Unlike commodity chemicals, PPDI elastomers are often traded as customized prepolymers or finished parts, making trade data more fragmented.
Raw Material Supply:
PPDI (p-phenylene diisocyanate) is produced by a limited number of chemical companies globally, including Covestro, BASF, Tosoh, and Wanhua. China has emerged as a major producer, reducing reliance on imports for Asian formulators.
The production of PPDI requires specialized phosgene handling and purification capabilities, creating high barriers to entry.
Trade Flows:
Asia-Pacific is a net exporter of PPDI-based elastomers, particularly to North America and Europe, driven by China's cost-competitive manufacturing.
North America and Europe are net importers of finished PPDI elastomer parts, but they export high-value specialty grades and proprietary formulations.
Trade data from UN Comtrade indicates that global trade in polyurethane elastomers (HS code 3909.50) grew by approximately 7% year-over-year in 2024, with Asia-Pacific accounting for over 50% of exports.
Supply Chain Risks:
Concentration Risk: The PPDI supply chain is concentrated among a few large producers, making it vulnerable to production outages or geopolitical disruptions.
Logistics: PPDI is a solid material at room temperature, which simplifies handling and transport compared to liquid MDI/TDI, but it still requires temperature-controlled storage to prevent degradation.
Regulatory Compliance: Differing regulations across regions (e.g., EU REACH vs. U.S. TSCA) create complexity for exporters, requiring dedicated compliance teams.
Strategic White-Space Analysis
Our analysis identifies several underpenetrated applications and emerging technological frontiers that represent significant growth opportunities for PPDI elastomer stakeholders.
Opportunity 1: Electric Vehicle Battery Thermal Management
PPDI elastomers are being evaluated for thermal interface materials and sealing components in EV battery packs, where they must withstand high temperatures, provide electrical insulation, and resist chemical attack from coolants. This is a high-growth white space with substantial volume potential.
Opportunity 2: Bio-based PPDI Synthesis
The development of bio-based polyols and, eventually, bio-based PPDI is a key R&D focus. While bio-based PPDI is not yet commercially available, industry roadmaps target 20% bio-content in commercial PU formulations by 2030. Companies that pioneer this technology will gain a first-mover advantage in sustainability-conscious markets.
Opportunity 3: 3D-Printed PPDI Elastomer Tooling
Additive manufacturing of TPU grades (including PPDI-based) enables rapid prototyping of industrial tooling, fixtures, and even end-use parts. The technology is already being adopted in aerospace and automotive R&D, and is poised to disrupt traditional mold-making processes.
Opportunity 4: Smart Elastomers with Embedded Sensors
The integration of sensors for condition monitoring and predictive maintenance is an emerging frontier. PPDI's robust mechanical properties make it an ideal matrix for embedding strain or temperature sensors in critical industrial components, enabling real-time health monitoring.
Opportunity 5: Medical Device Coatings
PPDI-based coatings with antimicrobial properties are being developed for catheters and implants, leveraging nanotechnology to enhance functionality. This is a high-value niche with strong intellectual property potential.
PPDI Type Polyurethane Elastomer Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
PPDI Type Polyurethane Elastomer Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2024
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.5% from 2020-2034
Segmentation
By Form
Solid Elastomers
Liquid Elastomers
Foam Elastomers
By Processing Technology
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising demand for high-performance elastomers in industrial automation and heavy machinery
3.1.2. Aerospace and defense sector's need for lightweight, fatigue-resistant materials
3.1.3. Medical device industry's requirement for biocompatible, sterilizable elastomers with superior mechanical properties
3.2. Market Trends
3.2.1. Electrification of automotive systems drives demand for high-temperature-resistant PPDI elastomers in EV battery and drivetrain components
3.2.2. Bio-based PPDI synthesis and sustainable polyol development gain traction as manufacturers pursue circular economy goals
3.2.3. Advanced processing technologies like 3D printing enable complex part geometries and reduce manufacturing waste
3.3. Market Restrains
3.3.1. Volatile isocyanate raw material pricing causes margin pressure for formulators
3.3.2. Regulatory pressure on di-isocyanates, particularly in Europe, increases compliance costs and operational complexity
3.3.3. Competition from advanced thermoplastic elastomers like PEBA and TPU alloys in premium medical and footwear applications
3.4. Market Restraints
Injection Molding
Extrusion
Casting
Others
By End-Use Industry
Automotive
Industrial Manufacturing
Healthcare
Consumer Goods
Aerospace & Defense
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia-Pacific
China
Japan
South Korea
India
Rest of Asia-Pacific
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
3.4.1. Volatile isocyanate raw material pricing causes margin pressure for formulators
3.4.2. Regulatory pressure on di-isocyanates, particularly in Europe, increases compliance costs and operational complexity
3.4.3. Competition from advanced thermoplastic elastomers like PEBA and TPU alloys in premium medical and footwear applications
3.5. Market Challenges
3.5.1. High barriers to entry due to specialized phosgene handling and purification requirements for PPDI production
3.5.2. Supply chain concentration among a few large PPDI producers creates vulnerability to disruptions
3.5.3. Divergent regulatory landscapes across regions complicate export compliance for finished elastomer parts
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Form
5.1.1. Solid Elastomers
5.1.2. Liquid Elastomers
5.1.3. Foam Elastomers
5.2. Market Analysis, Insights and Forecast - by Processing Technology
5.2.1. Injection Molding
5.2.2. Extrusion
5.2.3. Casting
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by End-Use Industry
5.3.1. Automotive
5.3.2. Industrial Manufacturing
5.3.3. Healthcare
5.3.4. Consumer Goods
5.3.5. Aerospace & Defense
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia-Pacific
5.4.4. South America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Form
6.1.1. Solid Elastomers
6.1.2. Liquid Elastomers
6.1.3. Foam Elastomers
6.2. Market Analysis, Insights and Forecast - by Processing Technology
6.2.1. Injection Molding
6.2.2. Extrusion
6.2.3. Casting
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by End-Use Industry
6.3.1. Automotive
6.3.2. Industrial Manufacturing
6.3.3. Healthcare
6.3.4. Consumer Goods
6.3.5. Aerospace & Defense
6.3.6. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Form
7.1.1. Solid Elastomers
7.1.2. Liquid Elastomers
7.1.3. Foam Elastomers
7.2. Market Analysis, Insights and Forecast - by Processing Technology
7.2.1. Injection Molding
7.2.2. Extrusion
7.2.3. Casting
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by End-Use Industry
7.3.1. Automotive
7.3.2. Industrial Manufacturing
7.3.3. Healthcare
7.3.4. Consumer Goods
7.3.5. Aerospace & Defense
7.3.6. Others
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Form
8.1.1. Solid Elastomers
8.1.2. Liquid Elastomers
8.1.3. Foam Elastomers
8.2. Market Analysis, Insights and Forecast - by Processing Technology
8.2.1. Injection Molding
8.2.2. Extrusion
8.2.3. Casting
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by End-Use Industry
8.3.1. Automotive
8.3.2. Industrial Manufacturing
8.3.3. Healthcare
8.3.4. Consumer Goods
8.3.5. Aerospace & Defense
8.3.6. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Form
9.1.1. Solid Elastomers
9.1.2. Liquid Elastomers
9.1.3. Foam Elastomers
9.2. Market Analysis, Insights and Forecast - by Processing Technology
9.2.1. Injection Molding
9.2.2. Extrusion
9.2.3. Casting
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by End-Use Industry
9.3.1. Automotive
9.3.2. Industrial Manufacturing
9.3.3. Healthcare
9.3.4. Consumer Goods
9.3.5. Aerospace & Defense
9.3.6. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Form
10.1.1. Solid Elastomers
10.1.2. Liquid Elastomers
10.1.3. Foam Elastomers
10.2. Market Analysis, Insights and Forecast - by Processing Technology
10.2.1. Injection Molding
10.2.2. Extrusion
10.2.3. Casting
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by End-Use Industry
10.3.1. Automotive
10.3.2. Industrial Manufacturing
10.3.3. Healthcare
10.3.4. Consumer Goods
10.3.5. Aerospace & Defense
10.3.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Covestro AG
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. BASF SE
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Huntsman Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Lubrizol Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Wanhua Chemical Group
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Tosoh Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Mitsui Chemicals Inc.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Era Polymers Pty Ltd.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Chemtura Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Polyurethane Technologies Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global PPDI Type Polyurethane Elastomer Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Form 2026 & 2034
Figure 3: North America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Form 2026 & 2034
Figure 4: North America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Processing Technology 2026 & 2034
Figure 5: North America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Processing Technology 2026 & 2034
Figure 6: North America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 7: North America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 8: North America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Form 2026 & 2034
Figure 11: Europe PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Form 2026 & 2034
Figure 12: Europe PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Processing Technology 2026 & 2034
Figure 13: Europe PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Processing Technology 2026 & 2034
Figure 14: Europe PPDI Type Polyurethane Elastomer Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 15: Europe PPDI Type Polyurethane Elastomer Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 16: Europe PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Form 2026 & 2034
Figure 19: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Form 2026 & 2034
Figure 20: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Processing Technology 2026 & 2034
Figure 21: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Processing Technology 2026 & 2034
Figure 22: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 23: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 24: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Country 2026 & 2034
Figure 26: South America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Form 2026 & 2034
Figure 27: South America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Form 2026 & 2034
Figure 28: South America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Processing Technology 2026 & 2034
Figure 29: South America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Processing Technology 2026 & 2034
Figure 30: South America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 31: South America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 32: South America PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Country 2026 & 2034
Figure 33: South America PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Form 2026 & 2034
Figure 35: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Form 2026 & 2034
Figure 36: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Processing Technology 2026 & 2034
Figure 37: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Processing Technology 2026 & 2034
Figure 38: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 39: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 40: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Form 2020 & 2034
Table 2: Global PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Processing Technology 2020 & 2034
Table 3: Global PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 4: Global PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Form 2020 & 2034
Table 6: North America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Processing Technology 2020 & 2034
Table 7: North America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 8: North America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Form 2020 & 2034
Table 13: Europe PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Processing Technology 2020 & 2034
Table 14: Europe PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 15: Europe PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Germany PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: UK PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: France PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Italy PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Spain PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Rest of Europe PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Form 2020 & 2034
Table 23: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Processing Technology 2020 & 2034
Table 24: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 25: Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Country 2020 & 2034
Table 26: China PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Japan PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: South Korea PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: India PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Rest of Asia-Pacific PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: South America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Form 2020 & 2034
Table 32: South America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Processing Technology 2020 & 2034
Table 33: South America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 34: South America PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Country 2020 & 2034
Table 35: Brazil PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Argentina PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Rest of South America PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Form 2020 & 2034
Table 39: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Processing Technology 2020 & 2034
Table 40: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 41: Middle East & Africa PPDI Type Polyurethane Elastomer Market Revenue Billion Forecast, by Country 2020 & 2034
Table 42: Saudi Arabia PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: UAE PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: South Africa PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Rest of MEA PPDI Type Polyurethane Elastomer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the PPDI type polyurethane elastomer market?
The global PPDI type polyurethane elastomer market was valued at approximately USD 3.25 billion in 2024. It is projected to grow at a CAGR of 6.5% to reach USD 5.67 billion by 2033, driven by demand from industrial machinery, automotive, aerospace, and medical device sectors.
2Which end-use industry consumes the most PPDI type polyurethane elastomer?
Industrial manufacturing is the largest end-use segment, accounting for about 35% of total market consumption in 2024. This is followed by automotive at 28%, aerospace and defense at 22%, and medical devices at 15%. The industrial segment's dominance is due to the material's exceptional abrasion resistance and load-bearing capacity.
3Which region holds the largest share of the PPDI type polyurethane elastomer market?
Asia-Pacific dominates the global market with approximately 45% share, driven by massive manufacturing footprints in China, Japan, and South Korea. North America follows with 28% market share, supported by advanced aerospace and medical device industries.
4What are the key drivers for the PPDI type polyurethane elastomer market?
Key drivers include the automotive industry's shift to electric vehicles, which requires high-temperature-resistant elastomers; the growth of industrial automation demanding vibration damping and wear-resistant components; and the aerospace sector's need for lightweight, fatigue-resistant materials. The medical device industry's demand for biocompatible, sterilizable elastomers also fuels growth.
5What are the main challenges facing the PPDI type polyurethane elastomer market?
The market faces challenges from volatile isocyanate raw material pricing, which has seen 25-40% price swings between 2021 and 2024. Regulatory pressure on di-isocyanates, particularly in Europe, increases compliance costs. Additionally, competition from advanced thermoplastic elastomers like PEBA and TPU alloys poses a threat in premium applications.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research methodology is anchored in a 70–80% primary research approach, ensuring that all data and insights are derived directly from the market's value chain. We conducted over 120 in-depth interviews with senior executives and technical experts across 15 countries.
We interviewed procurement directors at automotive OEMs, R&D managers at polyurethane formulators, plant engineers at industrial machinery manufacturers, and regulatory affairs specialists at medical device companies to capture granular demand-side and supply-side dynamics.
Key industry associations and regulatory bodies referenced include the American Chemistry Council (ACC), the European Diisocyanate and Polyol Producers Association (ISOPA), the International Isocyanate Institute (III), and the U.S. Food and Drug Administration (FDA) for medical device regulations.
Quantitative metrics such as PPDI elastomer consumption per industrial robot, average price per kilogram of PPDI prepolymer, and adoption rates in EV battery sealing applications were used in bottom-up market sizing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
R&D Manager
25%
Plant Engineer
25%
Regulatory Affairs Specialist
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Polyurethane Formulators
40%
Automotive OEMs
20%
Industrial Machinery Manufacturers
20%
Medical Device Companies
15%
Raw Material Suppliers
5%
Secondary Research & Industry Benchmarking
Approximately 20–30% of the research is derived from secondary sources, including official trade statistics from UN Comtrade (HS code 3909.50), Eurostat, and US ITC data on polyurethane elastomer trade flows.
We triangulated our findings with data from Bloomberg, Factiva, Hoovers, and PitchBook for company-level financials, M&A activity, and investment trends.
Industry benchmarks were validated against non-profit technical standards from ASTM International (e.g., D2000 for rubber products) and ISO standards for polyurethane testing.
All secondary data is cross-referenced with our primary interviews to ensure consistency and reliability.
Demand Modeling & Market Estimation
We employed a dual top-down and bottom-up methodology simultaneously. The bottom-up approach sized the market by aggregating consumption volumes from end-use industries, validated through expert interviews.
The top-down approach utilized global production data from national chemical industry associations and company filings to estimate market value.
A multi-level data triangulation process was applied, where estimates from both approaches were reconciled to within a 5% margin of error.
Demand models incorporated factors such as GDP growth by region, automotive production forecasts, industrial robot installations, and medical device market expansion.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90% for all quantitative and qualitative insights presented in this report.
Every data point is subjected to a three-tier validation process: (1) initial primary source verification, (2) secondary source cross-referencing, and (3) expert panel review.
The report is updated to the date of purchase, ensuring that the latest market developments and data are incorporated.
All sources, including official .gov and .org websites, are cited in the report's footnotes. For example, data from the U.S. Department of Energy (https://www.energy.gov) and the European Chemicals Agency (https://echa.europa.eu) are utilized for regulatory and R&D trend analysis.