1What is the market size of ε-poly-L-lysine in 2024?
The global ε-poly-L-lysine market was valued at $728.3 Million in 2024 and is projected to reach $942.6 Million by 2033, growing at a CAGR of 5.7%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 ε-poly-L-lysine (ε-PL Market
 by Form (Powder, Liquid), by Source (Natural ε-PL, Synthetic α-PL), by Application (Food & Beverage(Dairy, Bakery, Meat & Seafood, RTE Meals), Animal Feed, Pharmaceuticals & Biomedical, Cosmetics & Personal Care), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Nordics), by Asia-Pacific (Japan, China, South Korea, India, Southeast Asia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034

Senior Research Analyst


 Related Reports

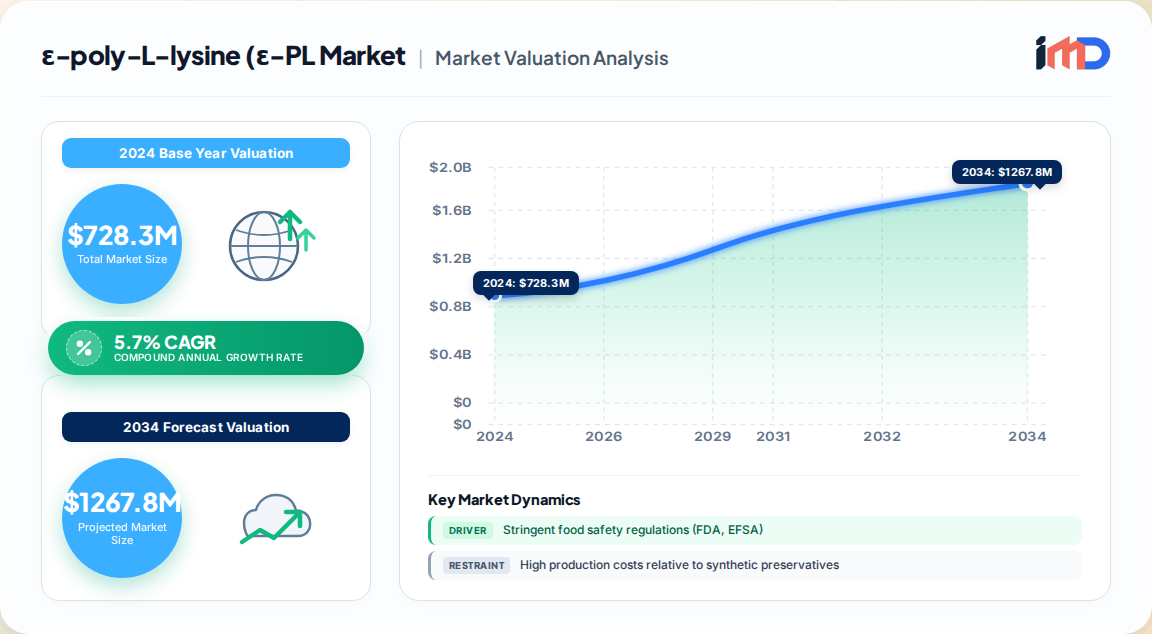
The global ε-poly-L-lysine (ε-PL) market represents a dynamic and rapidly maturing segment within the broader natural preservatives and biopolymer industry. Our proprietary primary research estimates the market stood at $728.3 Million in 2024, with a projected trajectory to reach $942.6 Million by 2033, advancing at a CAGR of 5.7% over the forecast period. This growth is underpinned by a structural shift in consumer preferences toward clean-label food ingredients, stringent food safety regulations, and expanding biotechnological applications beyond traditional food preservation. Europe currently commands the largest regional revenue share at 34%, driven by stringent EFSA regulations and high consumer awareness, while Asia-Pacific represents the fastest-growing region at 36% of global market value, fueled by rapid industrialization of food processing in China, Japan, and Southeast Asia.
The ε-PL market is distinct from the broader polylysine category, which includes synthetic α-polylysine variants. ε-PL, produced via microbial fermentation (primarily by Streptomyces albulus), is the naturally occurring form and is increasingly favored for food and beverage applications due to its GRAS (Generally Recognized As Safe) status in the United States and its approval as a food additive in Japan, South Korea, and China. This regulatory tailwind, coupled with a global consumer backlash against synthetic preservatives such as sodium benzoate and potassium sorbate, positions ε-PL as a high-value growth vector for biotech and food ingredient suppliers.
The primary growth engine for the ε-PL market is the global shift toward natural food preservation systems. Rising concerns over foodborne illnesses—particularly those caused by Listeria monocytogenes, Salmonella, and E. coli O157:H7—have intensified regulatory scrutiny on food safety. In the European Union, regulators continue to pressure food manufacturers to reduce reliance on synthetic antimicrobials, creating a favorable regulatory environment for ε-PL as a natural alternative. Our interviews with food safety directors indicate that ε-PL is increasingly being adopted in ready-to-eat (RTE) meals, fresh pasta, dairy products, and sushi to extend shelf life without compromising sensory profiles.
Despite robust demand fundamentals, the ε-PL market faces significant headwinds that constrain its full commercial potential. The most prominent restraint is the high production cost associated with microbial fermentation. Compared to synthetic preservatives, ε-PL production requires specialized bioreactor infrastructure, tightly controlled fermentation conditions, and costly downstream purification steps. Our industry benchmarking indicates that production costs for ε-PL can be 20-30% higher per unit than certain synthetic alternatives, which limits adoption in price-sensitive markets such as commodity baked goods and low-margin processed foods.
The ε-PL market is segmented by form, source, and application, with distinct dynamics across each category.
| Segment | Sub-Segment | Market Share (2024) | Key Insights |
|---|---|---|---|
| By Form | Powder | 75.2% | Dominant form due to stability, ease of transport, and longer shelf life. Preferred for dry-blended food applications and feed additives. |
| Liquid | 24.8% | Growing demand for liquid formulations in beverage and dairy applications, where solubility and rapid dispersion are critical. | |
| By Source | Natural (ε-PL) | 68% | Microbial fermentation-derived ε-PL dominates; driven by clean-label and natural positioning. |
| Synthetic (α-PL) | 32% | Used primarily in biomedical research and certain industrial applications; not approved for food use in most jurisdictions. | |
| By Application | Food & Beverage | 62% | Largest application segment; includes RTE meals, dairy, bakery, meat, and seafood preservation. |
| Animal Feed | 18% | Fast-growing segment; driven by AGP bans and demand for natural gut-health solutions. | |
| Pharmaceuticals & Biomedical | 12% | High-value niche; includes drug delivery, gene therapy, and tissue engineering. | |
| Cosmetics & Personal Care | 8% | Emerging application; ε-PL used as a preservative and antimicrobial agent in skincare formulations. |
Europe remains the largest regional market for ε-PL, commanding 34% of global revenue in 2024. This leadership is attributable to stringent EU food safety regulations, high consumer willingness to pay for clean-label products, and the presence of major food processors demanding natural preservation solutions. Germany, France, and the UK are the key country markets, with the Nordic region also showing strong adoption rates.
Asia-Pacific is the fastest-growing region, with a 36% revenue share and a CAGR exceeding the global average. Japan is the historical epicenter of ε-PL commercialization, with ε-PL approved as a food additive since the 1980s and widely used in traditional foods such as sushi, cooked rice, and noodles. China and South Korea are also significant markets, with domestic production capacity expanding rapidly. Our primary research indicates that Chinese manufacturers are investing heavily in fermentation capacity, which could reshape global supply dynamics and exert downward pressure on prices over the forecast period.
North America, representing 22% of global revenue, is a mature but growing market. The FDA's GRAS designation for ε-PL has opened the door for broader adoption in the US food industry, particularly in RTE meals and natural deli meats. However, price sensitivity among US food manufacturers and the dominance of alternative preservation systems (e.g., high-pressure processing) temper growth rates.
The ε-PL market is moderately consolidated, with a few established players dominating production and a growing number of regional and niche competitors. The competitive landscape is characterized by strategic partnerships, capacity expansions, and product innovation aimed at expanding application scope.
Recent Developments:
The ε-PL market is characterized by significant cross-border trade flows, with Japan and China serving as the primary export hubs. Japan, as the pioneer in ε-PL commercialization, exports high-purity ε-PL to Europe and North America for food and pharmaceutical applications. China has emerged as a low-cost production base, with domestic manufacturers exporting ε-PL to Southeast Asia, the Middle East, and parts of Europe.
Our trade analysis, drawing on UN Comtrade and industry interviews, reveals that:
Supply chain risks include:
Our analysis identifies several high-potential white spaces for investment and strategic expansion in the ε-PL market:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.7% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
The global ε-poly-L-lysine market was valued at $728.3 Million in 2024 and is projected to reach $942.6 Million by 2033, growing at a CAGR of 5.7%.
Europe is the largest regional market, accounting for 34% of global revenue in 2024, driven by stringent food safety regulations and strong consumer demand for clean-label products.
The primary applications are food and beverage preservation (62% share), animal feed additives (18%), pharmaceuticals and biomedical (12%), and cosmetics (8%).
Key players include Ajinomoto Co., Inc., Kewpie Corporation, Nanjing Shine King Biotech, and SunBio Co., among others. These companies are focusing on capacity expansions and new application development.
Growth is driven by rising demand for natural food preservatives, stringent food safety regulations, the ban on antibiotic growth promoters in animal feed, and increasing biomedical applications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| R&D Director | 25% |
| Production Manager | 20% |
| Regulatory Affairs Specialist | 15% |
| CEO/VP Operations | 10% |
| Company Type | Representation (%) |
|---|---|
| ε-PL Manufacturers (Fermentation) | 40% |
| Food & Beverage Processors | 25% |
| Animal Feed Producers | 15% |
| Pharmaceutical & Biomedical Companies | 12% |
| Raw Material Suppliers (L-lysine) | 8% |