1What is the Plasma Dicing System market size in 2026?
The market is valued at USD 140.87 million in 2026 and is projected to reach USD 209.20 million by 2032, growing at a CAGR of 6.85%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Plasma Dicing System
 by By Equipment Type (Batch Dicing System, Single Wafer Dicing System), by By Wafer Size (12 Inch, 8 Inch, 6 Inch, Less Than 6 Inch), by By Wafer Thickness (Less Than 200 Micrometer, 200 To 400 Micrometer, Greater Than 400 Micrometer), by By Application (Logic and Memory, Power Devices, MEMS Devices, CMOS Image Sensors, LED and Photonics), by By End-User (Foundries, IDMs, OSATs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, Taiwan, India, Southeast Asia), by Middle East (GCC Countries), by South America (Brazil), by Africa Forecast 2026-2034

Senior Research Analyst


 Related Reports

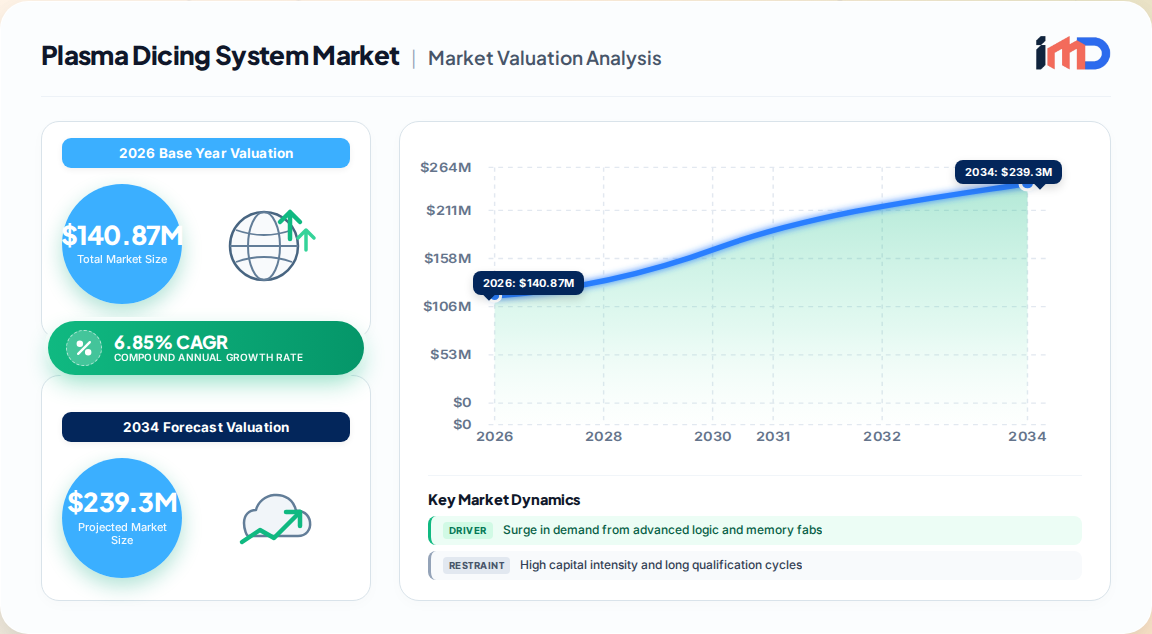
The global Plasma Dicing System market is valued at USD 140.87 million in 2026 and is projected to reach USD 209.20 million by 2032, expanding at a CAGR of 6.85%. This trajectory is underpinned by a structural shift away from mechanical blade singulation for fragile, thin, and high-value semiconductor devices. Plasma dicing — a dry-etch process that simultaneously separates all die streets across a wafer — is transitioning from a niche yield-enhancement tool to a core enabler of advanced packaging and heterogeneous integration.
Plasma dicing eliminates mechanical stress, achieves 5–10 µm street widths versus the 15–50 µm kerf of blade saws, and improves die-per-wafer yield by 1–4%. For ultra-thin wafers below 50 µm and compound semiconductor substrates, these advantages translate directly into scrap avoidance and gross-margin protection.
The plasma dicing value chain spans specialty gas and chemical suppliers, etch chamber and plasma source OEMs, integration and automation providers, and downstream qualification at foundries, IDMs, and OSATs.
| Value Chain Stage | Key Inputs / Activities | Primary Participants |
|---|---|---|
| Upstream materials | Specialty etch gases (SF6, C4F8, O2), mask materials, carrier tapes | Gas and chemical suppliers |
| Equipment OEM | Plasma etch chambers, RF power systems, endpoint detection, wafer handling | Plasma dicing system manufacturers |
| Integration & automation | Lithography alignment, MES connectivity, AI-enabled process control | Automation and metrology vendors |
| Qualification & production | Process recipes, yield validation, downstream assembly | Foundries, IDMs, OSATs |
| Service & aftermarket | Chamber cleaning, spare parts, recipe optimization, training | OEM service networks and application engineers |
A critical dynamic is the co-development relationship between equipment OEMs and advanced packaging R&D consortia. As fabs evaluate plasma dicing against laser and stealth methods, suppliers that provide application engineering, regional service coverage, and validated process data are best positioned to secure anchor orders.
Asia-Pacific anchored 56.57% of global dicing equipment sales in 2025, and its dominance extends to plasma dicing adoption. Taiwan, South Korea, Japan, and China collectively host the world's densest concentration of wafer fabs and OSATs.
| Region | Market Share (2026) | Key Adoption Drivers |
|---|---|---|
| Asia-Pacific | 57% | Advanced foundry and memory fabs, OSAT concentration, government localization incentives |
| North America | 18% | Advanced packaging R&D, defense electronics, reshoring initiatives |
| Europe | 15% | Automotive power devices, industrial semiconductors, research consortia |
| Middle East | 6% | Emerging fab construction, technology diversification programs |
| South America | 2% | Selective electronics assembly and research activity |
| Africa | 2% | Early-stage industrial and research applications |
The Middle East is expected to log the fastest regional CAGR as new fabs evaluate baseline process flows and seek sub-micrometer run-out solutions. Europe's growth is tied to SiC and GaN power device capacity expansions supporting the automotive transition.
The plasma dicing system market is moderately concentrated, with a mix of dedicated etch OEMs, diversified semiconductor equipment majors, and emerging regional challengers.
Strategic activity centers on co-development agreements with foundries and OSATs, regional service expansion, and AI-enabled process control. The competitive moat increasingly depends on validated yield data, recipe libraries, and integration with manufacturing execution systems rather than equipment specifications alone.
Plasma dicing equipment trade flows are shaped by export-control regimes, regional localization incentives, and the concentration of specialty gas and component supply.
Fabs are responding by diversifying critical suppliers, establishing buffer inventories of specialty gases, and qualifying dual-source platforms for high-volume lines.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.85% from 2020-2034 |
| Segmentation |
|
By Wafer Thickness
By Application
By End-User
| By Geography |
|
The market is valued at USD 140.87 million in 2026 and is projected to reach USD 209.20 million by 2032, growing at a CAGR of 6.85%.
Plasma dicing achieves 5–10 µm street widths versus 15–50 µm blade kerf, improves die-per-wafer yield by 1–4%, and eliminates mechanical stress that causes micro-cracks in thin wafers and compound semiconductors.
Asia-Pacific accounts for approximately 57% of the global market, driven by the concentration of wafer fabs and OSATs in Taiwan, South Korea, Japan, and China.
Key applications include advanced logic and memory, power devices (SiC/GaN), MEMS, CMOS image sensors, and LED/photonics, with power devices growing fastest due to electric-vehicle demand.
Major players include Panasonic Connect, Hitachi High-Tech, DISCO Corporation, Applied Materials, Plasma-Therm, Oxford Instruments Plasma Technology, and Tokyo Seimitsu (ACCRETECH).
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Fab Process Integration Engineers | 30% |
| Packaging R&D Directors | 25% |
| Equipment Procurement Managers | 25% |
| Advanced Packaging Program Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Plasma Etch Equipment OEMs | 35% |
| Specialty Gas and Chemical Suppliers | 20% |
| Foundries and IDMs | 25% |
| OSATs and Packaging Houses | 15% |
| Research Institutes and Consortia | 5% |