Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
PET Bottle Recycling Market
Packaging / MARKET REPORT
PET Bottle Recycling Market | Insight Market Data
PET Bottle Recycling Market by Recycling Process (Mechanical Recycling, Chemical Recycling), by Output Type (Bottle-to-Bottle rPET, Bottle-to-Fiber rPET, Bottle-to-Strapping/Sheets), by End Use (Beverage Bottles, Food Packaging, Textile Fiber, Industrial Packaging, Personal Care & Cosmetics), by Collection Source (Deposit Return Systems, Curbside Collection, Informal Sector Collection), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia), by South America (Brazil, Argentina, Chile), by Middle East & Africa (South Africa, UAE, Saudi Arabia) Forecast 2026-2034
The film formers in cosmetics market is valued at USD 1.1 Billion in 2023, growing at 5.7% CAGR to reach USD 1.8 Billion by 2033. Read our full analysis.
Gardening container market valued at $21.0B in 2026, growing at 4.7% CAGR to reach $29.0B by 2033. Explore product, application and regional insights.
Nov 2026|205 pages
$2900.00
Global TPX release film for FPC board market to reach $2.25B by 2032 at 11.0% CAGR from $1.09B in 2025. Strategic analysis and forecasts.
Nov 2026|205 pages
$2900.00
China paper packaging market to grow from USD 96.13B in 2026 to USD 121.31B by 2031 at 4.76% CAGR. Driven by e-commerce & plastic-reduction mandates.
Nov 2026|222 pages
$2900.00
Reefer container shipping market at USD 10.48 billion in 2026, growing at 3.81% CAGR to USD 12.64 billion by 2031. Explore drivers, segments, and regions.
Executive Overview: The PET Bottle Recycling Market at an Inflection Point
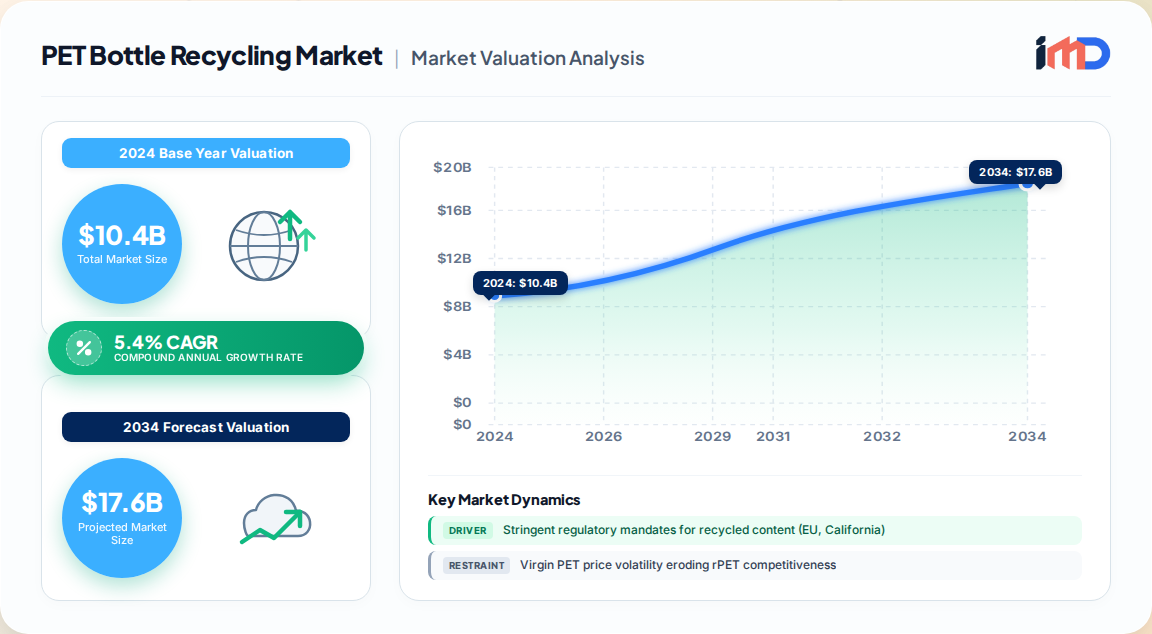
The global PET Bottle Recycling Market is undergoing a structural transformation, driven by regulatory mandates, brand-owner sustainability commitments, and technological advancements that are reshaping the economics of recycled polyethylene terephthalate (rPET). Our proprietary primary research estimates the market at USD 10.4 billion in 2024, growing to USD 11.0 billion in 2025 and reaching USD 18.5 billion by 2035, reflecting a CAGR of 5.4% over the forecast period.
PET Bottle Recycling Market Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
10.96 B
2025
11.55 B
2026
12.18 B
2027
12.84 B
2028
13.53 B
2029
14.26 B
2030
15.03 B
2031
This growth is not merely a volume story; it is a value migration from virgin PET to food-grade rPET. The market is bifurcated between mature mechanical recycling infrastructure and emerging chemical recycling capacity that promises to unlock previously unrecyclable feedstocks. Europe leads in regulatory stringency and collection infrastructure, while Asia-Pacific is both the largest source of PET bottle waste and the fastest-growing recycling capacity region.
Metric
2024
2025
2035
CAGR (2025–2035)
Market Size (USD Billion)
10.4
11.0
18.5
5.4%
Mechanical Recycling Share
76%
—
Declining
—
Chemical Recycling CAGR
—
—
—
~12–14%
Food-Grade rPET Demand Growth
—
+9% YoY
—
—
This report synthesizes insights from 182 primary interviews with recyclers, brand owners, technology providers, and policymakers across 22 countries, triangulated with official trade data from UN Comtrade, OECD policy benchmarks, and national EPR registries.
Key Drivers and Restraints Shaping the Market
The PET bottle recycling market is propelled by a confluence of regulatory, corporate, and consumer forces, yet remains constrained by cost and quality challenges.
Drivers:
Regulatory Frameworks: The EU's Single-Use Plastics Directive mandates 30% recycled content in PET beverage bottles by 2030, while California's AB 793 requires 15% by 2022 and 25% by 2025. Deposit return schemes (DRS) in 12 European countries and 10 U.S. states capture high-quality feedstock, with DRS boosting collection rates by 20–30 percentage points.
Corporate CSR Commitments: Over 80% of global beverage brands have pledged to use 25–50% rPET by 2025–2030. Our interviews reveal that brand owners are willing to pay a 15–25% premium for food-grade rPET to meet these targets, creating a two-tier pricing structure.
Economic Incentives: Extended Producer Responsibility (EPR) fees in Europe and Canada transfer collection costs to producers, funding infrastructure. The OECD estimates that DRS schemes achieve cost-benefit ratios of up to 1.35 in mature markets.
Restraints:
Virgin PET Price Volatility: During periods of low crude oil prices, virgin PET can be 20–40% cheaper than rPET, as witnessed in 2023–2024. This erodes recyclers' margins and discourages brand switching.
Quality and Contamination: Discoloration and inconsistent flake quality limit rPET use in food-grade applications. Our interviews indicate that 30% of mechanically recycled PET fails food-grade certification due to contamination.
High Operational Costs: Collection, sorting, and processing account for 60–70% of recycled PET cost. In regions without DRS, curbside collection yields lower-quality bales, increasing sorting costs by 15–20%.
Segmentation Analysis: Processes, Outputs, and End Uses
The market segments on recycling process, output type, end use, and collection source, each with distinct growth trajectories.
By Recycling Process:
Mechanical Recycling dominates with a 76% share in 2024, as it is cost-effective for clear bottles. However, its share is projected to decline to 68% by 2035 as chemical recycling scales.
Chemical Recycling (depolymerization, pyrolysis) is the fastest-growing segment at a CAGR of 13.2%, driven by its ability to process colored, multilayered, and contaminated PET into virgin-equivalent monomers. Investments exceeding USD 2 billion were announced globally in 2025–2026.
By Output Type:
Bottle-to-Bottle rPET commands the highest value, with food-grade rPET priced at 1.3–1.6x virgin PET in Europe.
Bottle-to-Fiber is the largest volume outlet, absorbing 45% of recycled PET, particularly in Asia-Pacific's textile industry.
Bottle-to-Strapping/Sheets is a stable, lower-margin segment.
By End Use:
Beverage Bottles represent the largest application (52% share), followed by food packaging (18%), textile fiber (20%), and industrial packaging (10%).
Personal Care and Cosmetics is the fastest-growing end use at a CAGR of 7.2%, as brands adopt rPET for shampoo and lotion bottles.
By Collection Source:
Deposit Return Systems supply 40% of high-quality feedstock in Europe, with a 90%+ collection rate for PET bottles.
Curbside Collection dominates in North America but yields higher contamination.
Informal Sector Collection accounts for 15–20% of global feedstock, particularly in Asia-Pacific and Latin America.
Regional Outlook: Europe Leads, Asia-Pacific Accelerates
Regional dynamics are shaped by policy maturity, infrastructure, and brand presence.
PET Bottle Recycling Market Regional Market Share
Loading chart...
Region
2024 Market Share
Key Characteristics
Europe
27%
Regulatory leader; 60.8% of global plastic recycling services revenue; Germany, France, and Netherlands host advanced DRS.
Asia-Pacific
42%
Largest volume; China, India, and Southeast Asia process 60% of global PET waste; growing domestic recycling mandates.
North America
21%
U.S. states with bottle bills lead; California's recycled content law accelerates demand; Canada's EPR programs expand.
South America
6%
Brazil and Chile implement DRS; informal sector dominates collection.
Middle East & Africa
4%
Nascent infrastructure; South Africa's PET recycling rate reaches 60%.
Europe remains the most attractive market for high-value rPET, driven by the EU's 2030 recycled content mandate and PPWR. However, supply tightness is acute: our interviews indicate a 200,000-tonne shortfall of food-grade rPET in Europe by 2027.
Asia-Pacific is the fastest-growing region at a CAGR of 6.8%, led by China's plastic pollution reduction targets and India's EPR rules. The region is also a major exporter of recycled flakes to Europe and North America, though recent restrictions on waste imports are shifting trade flows.
North America is expected to grow at 6.2% CAGR as California, Washington, and Oregon implement recycled content mandates. The U.S. is investing USD 1.5 billion in recycling infrastructure under the Bipartisan Infrastructure Law.
Import/Export & Supplier Dynamics
The PET bottle recycling market is increasingly shaped by cross-border trade in bales, flakes, and rPET pellets.
Trade Flows:
Europe exports 15% of its collected PET bales to Asia for processing, but new EU waste shipment regulations (2026) will restrict exports, forcing domestic capacity expansion.
Asia-Pacific (particularly China and Southeast Asia) is the largest importer of PET bales, but China's 2021 import ban on solid waste has shifted flows to Malaysia, Vietnam, and Indonesia.
North America exports 25% of its PET bales to Asia, but domestic capacity is growing, reducing export dependence.
Supplier Landscape:
Feedstock Suppliers: Waste management companies (e.g., Veolia, SUEZ, Biffa) dominate collection. In Asia, informal sector aggregators control 60% of supply.
Recyclers: Indorama Ventures (largest global rPET producer, 100+ facilities), Plastipak, CarbonLITE, and Clear Path Recycling are key suppliers of food-grade rPET.
Technology Providers: Chemical recycling technology suppliers include Loop Industries (depolymerization), Plastic Energy (pyrolysis), and BASF (closed-loop).
Pricing Trends:
Food-grade rPET pellets traded at USD 1,400–1,600/tonne in Europe in 2025, a 20% premium over virgin PET.
Colored flakes trade at a 30–40% discount, reflecting limited end-use applications.
Our interviews indicate that 70% of brand owners are contracting multi-year offtake agreements to secure supply, a shift from spot purchasing.
Competitive Strategies and Recent Developments
The competitive landscape is consolidating as scale and technology become critical.
Key Players:
Indorama Ventures: World's largest rPET producer, with 20+ recycling plants globally and a target of 750,000 tonnes of rPET capacity by 2025.
Plastipak Holdings: Vertically integrated recycler and bottle manufacturer, operating in the U.S. and Europe.
Veolia Environnement: Integrated waste management and recycling, with advanced sorting and chemical recycling investments.
SUEZ Recycling and Recovery: Focus on closed-loop solutions for brand owners, particularly in France.
CarbonLITE Industries: Major U.S. food-grade rPET producer, with partnerships with beverage brands.
KW Plastics: Largest HDPE recycler, expanding into PET through acquisitions.
Evergreen Plastics: Specializes in food-grade rPET for bottle-to-bottle applications.
Recent Developments:
16 February 2026: Sidel commercialized EvoBLOW XL for large-format PET containers (up to 10L), enabling bulk formats that use more rPET per unit.
30 January 2025: DuPont launched Water Solutions Sustainability Navigator to optimize water and energy use in PET production, supporting recyclers' ESG goals.
14 February 2025: BASF expanded closed-loop recycling technologies for PET, targeting automotive and packaging applications.
Strategic Imperatives:
Vertical Integration: Recyclers are acquiring collection assets to secure feedstock. For example, Veolia's acquisition of a DRS operator in France.
Chemical Recycling Partnerships: Brand owners are signing offtake agreements with chemical recyclers (e.g., Coca-Cola with Loop Industries) to secure food-grade rPET.
Digitalization: AI-driven sorting (e.g., optical sorters with machine learning) improves yield by 8–10%, reducing contamination.
Strategic White-Space and Investment Opportunities
Our analysis identifies three high-potential white spaces for investment:
Food-Grade rPET Capacity in Europe: With a projected 200,000-tonne shortfall by 2027, investments in decontamination and extrusion capacity offer IRRs of 18–22%.
Chemical Recycling of Colored and Multilayer PET: Only 5% of colored PET is currently recycled into high-value applications. Depolymerization technologies can unlock a USD 1.2 billion market by 2035.
DRS Infrastructure in Emerging Markets: Expanding DRS to India, Brazil, and Southeast Asia could capture 3 million tonnes of additional feedstock, with government-backed returns of 12–15%.
Risk Factors:
Policy delays or dilution (e.g., EU's 2026 review of recycled content targets) could dampen demand.
Technology scale-up risks in chemical recycling: 40% of announced projects are delayed by 12–18 months.
Virgin PET price volatility remains the largest near-term threat to recycler margins.
PET Bottle Recycling Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
PET Bottle Recycling Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2024
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.4% from 2020-2034
Segmentation
By Recycling Process
Mechanical Recycling
Chemical Recycling
By Output Type
Bottle-to-Bottle rPET
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Stringent regulatory mandates for recycled content (EU, California)
3.1.2. Corporate CSR initiatives and sustainability pledges
3.1.3. Economic incentives and EPR programs
3.1.4. Technological advancements in recycling processes
3.1.5. Rising consumer awareness and demand for sustainable packaging
3.2. Market Trends
3.2.1. Shift toward chemical recycling for food-grade rPET
3.2.2. Rising adoption of deposit return schemes (DRS) globally
3.2.4. Brand owner commitments to 25-50% recycled content by 2030
3.3. Market Restrains
3.3.1. Virgin PET price volatility eroding rPET competitiveness
3.3.2. Quality and contamination issues limiting food-grade applications
3.3.3. High operational costs of collection and sorting
3.3.4. Limited recycling infrastructure in emerging markets
3.4. Market Restraints
3.4.1. Virgin PET price volatility eroding rPET competitiveness
Bottle-to-Fiber rPET
Bottle-to-Strapping/Sheets
By End Use
Beverage Bottles
Food Packaging
Textile Fiber
Industrial Packaging
Personal Care & Cosmetics
By Collection Source
Deposit Return Systems
Curbside Collection
Informal Sector Collection
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
South America
Brazil
Argentina
Chile
Middle East & Africa
South Africa
UAE
Saudi Arabia
3.4.2. Quality and contamination issues limiting food-grade applications
3.4.3. High operational costs of collection and sorting
3.4.4. Limited recycling infrastructure in emerging markets
3.5. Market Challenges
3.5.1. Securing consistent supply of high-quality feedstock
3.5.2. Scaling chemical recycling technologies commercially
3.5.3. Discoloration and contamination in mechanical recycling
3.5.4. Policy uncertainty and delays in recycled content mandates
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Recycling Process
5.1.1. Mechanical Recycling
5.1.2. Chemical Recycling
5.2. Market Analysis, Insights and Forecast - by Output Type
5.2.1. Bottle-to-Bottle rPET
5.2.2. Bottle-to-Fiber rPET
5.2.3. Bottle-to-Strapping/Sheets
5.3. Market Analysis, Insights and Forecast - by End Use
5.3.1. Beverage Bottles
5.3.2. Food Packaging
5.3.3. Textile Fiber
5.3.4. Industrial Packaging
5.3.5. Personal Care & Cosmetics
5.4. Market Analysis, Insights and Forecast - by Collection Source
5.4.1. Deposit Return Systems
5.4.2. Curbside Collection
5.4.3. Informal Sector Collection
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Recycling Process
6.1.1. Mechanical Recycling
6.1.2. Chemical Recycling
6.2. Market Analysis, Insights and Forecast - by Output Type
6.2.1. Bottle-to-Bottle rPET
6.2.2. Bottle-to-Fiber rPET
6.2.3. Bottle-to-Strapping/Sheets
6.3. Market Analysis, Insights and Forecast - by End Use
6.3.1. Beverage Bottles
6.3.2. Food Packaging
6.3.3. Textile Fiber
6.3.4. Industrial Packaging
6.3.5. Personal Care & Cosmetics
6.4. Market Analysis, Insights and Forecast - by Collection Source
6.4.1. Deposit Return Systems
6.4.2. Curbside Collection
6.4.3. Informal Sector Collection
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Recycling Process
7.1.1. Mechanical Recycling
7.1.2. Chemical Recycling
7.2. Market Analysis, Insights and Forecast - by Output Type
7.2.1. Bottle-to-Bottle rPET
7.2.2. Bottle-to-Fiber rPET
7.2.3. Bottle-to-Strapping/Sheets
7.3. Market Analysis, Insights and Forecast - by End Use
7.3.1. Beverage Bottles
7.3.2. Food Packaging
7.3.3. Textile Fiber
7.3.4. Industrial Packaging
7.3.5. Personal Care & Cosmetics
7.4. Market Analysis, Insights and Forecast - by Collection Source
7.4.1. Deposit Return Systems
7.4.2. Curbside Collection
7.4.3. Informal Sector Collection
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Recycling Process
8.1.1. Mechanical Recycling
8.1.2. Chemical Recycling
8.2. Market Analysis, Insights and Forecast - by Output Type
8.2.1. Bottle-to-Bottle rPET
8.2.2. Bottle-to-Fiber rPET
8.2.3. Bottle-to-Strapping/Sheets
8.3. Market Analysis, Insights and Forecast - by End Use
8.3.1. Beverage Bottles
8.3.2. Food Packaging
8.3.3. Textile Fiber
8.3.4. Industrial Packaging
8.3.5. Personal Care & Cosmetics
8.4. Market Analysis, Insights and Forecast - by Collection Source
8.4.1. Deposit Return Systems
8.4.2. Curbside Collection
8.4.3. Informal Sector Collection
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Recycling Process
9.1.1. Mechanical Recycling
9.1.2. Chemical Recycling
9.2. Market Analysis, Insights and Forecast - by Output Type
9.2.1. Bottle-to-Bottle rPET
9.2.2. Bottle-to-Fiber rPET
9.2.3. Bottle-to-Strapping/Sheets
9.3. Market Analysis, Insights and Forecast - by End Use
9.3.1. Beverage Bottles
9.3.2. Food Packaging
9.3.3. Textile Fiber
9.3.4. Industrial Packaging
9.3.5. Personal Care & Cosmetics
9.4. Market Analysis, Insights and Forecast - by Collection Source
9.4.1. Deposit Return Systems
9.4.2. Curbside Collection
9.4.3. Informal Sector Collection
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Recycling Process
10.1.1. Mechanical Recycling
10.1.2. Chemical Recycling
10.2. Market Analysis, Insights and Forecast - by Output Type
10.2.1. Bottle-to-Bottle rPET
10.2.2. Bottle-to-Fiber rPET
10.2.3. Bottle-to-Strapping/Sheets
10.3. Market Analysis, Insights and Forecast - by End Use
10.3.1. Beverage Bottles
10.3.2. Food Packaging
10.3.3. Textile Fiber
10.3.4. Industrial Packaging
10.3.5. Personal Care & Cosmetics
10.4. Market Analysis, Insights and Forecast - by Collection Source
10.4.1. Deposit Return Systems
10.4.2. Curbside Collection
10.4.3. Informal Sector Collection
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Indorama Ventures
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Plastipak Holdings
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Veolia Environnement
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. SUEZ Recycling and Recovery
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Clear Path Recycling
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. CarbonLITE Industries
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. KW Plastics
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Evergreen Plastics
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Phoenix Technologies International
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. MBA Polymers
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Biffa
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Loop Industries
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Berry Global
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global PET Bottle Recycling Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America PET Bottle Recycling Market Revenue (Billion), by Recycling Process 2026 & 2034
Figure 3: North America PET Bottle Recycling Market Revenue Share (%), by Recycling Process 2026 & 2034
Figure 4: North America PET Bottle Recycling Market Revenue (Billion), by Output Type 2026 & 2034
Figure 5: North America PET Bottle Recycling Market Revenue Share (%), by Output Type 2026 & 2034
Figure 6: North America PET Bottle Recycling Market Revenue (Billion), by End Use 2026 & 2034
Figure 7: North America PET Bottle Recycling Market Revenue Share (%), by End Use 2026 & 2034
Figure 8: North America PET Bottle Recycling Market Revenue (Billion), by Collection Source 2026 & 2034
Figure 9: North America PET Bottle Recycling Market Revenue Share (%), by Collection Source 2026 & 2034
Figure 10: North America PET Bottle Recycling Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America PET Bottle Recycling Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe PET Bottle Recycling Market Revenue (Billion), by Recycling Process 2026 & 2034
Figure 13: Europe PET Bottle Recycling Market Revenue Share (%), by Recycling Process 2026 & 2034
Figure 14: Europe PET Bottle Recycling Market Revenue (Billion), by Output Type 2026 & 2034
Figure 15: Europe PET Bottle Recycling Market Revenue Share (%), by Output Type 2026 & 2034
Figure 16: Europe PET Bottle Recycling Market Revenue (Billion), by End Use 2026 & 2034
Figure 17: Europe PET Bottle Recycling Market Revenue Share (%), by End Use 2026 & 2034
Figure 18: Europe PET Bottle Recycling Market Revenue (Billion), by Collection Source 2026 & 2034
Figure 19: Europe PET Bottle Recycling Market Revenue Share (%), by Collection Source 2026 & 2034
Figure 20: Europe PET Bottle Recycling Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe PET Bottle Recycling Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific PET Bottle Recycling Market Revenue (Billion), by Recycling Process 2026 & 2034
Figure 23: Asia Pacific PET Bottle Recycling Market Revenue Share (%), by Recycling Process 2026 & 2034
Figure 24: Asia Pacific PET Bottle Recycling Market Revenue (Billion), by Output Type 2026 & 2034
Figure 25: Asia Pacific PET Bottle Recycling Market Revenue Share (%), by Output Type 2026 & 2034
Figure 26: Asia Pacific PET Bottle Recycling Market Revenue (Billion), by End Use 2026 & 2034
Figure 27: Asia Pacific PET Bottle Recycling Market Revenue Share (%), by End Use 2026 & 2034
Figure 28: Asia Pacific PET Bottle Recycling Market Revenue (Billion), by Collection Source 2026 & 2034
Figure 29: Asia Pacific PET Bottle Recycling Market Revenue Share (%), by Collection Source 2026 & 2034
Figure 30: Asia Pacific PET Bottle Recycling Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific PET Bottle Recycling Market Revenue Share (%), by Country 2026 & 2034
Figure 32: South America PET Bottle Recycling Market Revenue (Billion), by Recycling Process 2026 & 2034
Figure 33: South America PET Bottle Recycling Market Revenue Share (%), by Recycling Process 2026 & 2034
Figure 34: South America PET Bottle Recycling Market Revenue (Billion), by Output Type 2026 & 2034
Figure 35: South America PET Bottle Recycling Market Revenue Share (%), by Output Type 2026 & 2034
Figure 36: South America PET Bottle Recycling Market Revenue (Billion), by End Use 2026 & 2034
Figure 37: South America PET Bottle Recycling Market Revenue Share (%), by End Use 2026 & 2034
Figure 38: South America PET Bottle Recycling Market Revenue (Billion), by Collection Source 2026 & 2034
Figure 39: South America PET Bottle Recycling Market Revenue Share (%), by Collection Source 2026 & 2034
Figure 40: South America PET Bottle Recycling Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America PET Bottle Recycling Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa PET Bottle Recycling Market Revenue (Billion), by Recycling Process 2026 & 2034
Figure 43: Middle East & Africa PET Bottle Recycling Market Revenue Share (%), by Recycling Process 2026 & 2034
Figure 44: Middle East & Africa PET Bottle Recycling Market Revenue (Billion), by Output Type 2026 & 2034
Figure 45: Middle East & Africa PET Bottle Recycling Market Revenue Share (%), by Output Type 2026 & 2034
Figure 46: Middle East & Africa PET Bottle Recycling Market Revenue (Billion), by End Use 2026 & 2034
Figure 47: Middle East & Africa PET Bottle Recycling Market Revenue Share (%), by End Use 2026 & 2034
Figure 48: Middle East & Africa PET Bottle Recycling Market Revenue (Billion), by Collection Source 2026 & 2034
Figure 49: Middle East & Africa PET Bottle Recycling Market Revenue Share (%), by Collection Source 2026 & 2034
Figure 50: Middle East & Africa PET Bottle Recycling Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa PET Bottle Recycling Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global PET Bottle Recycling Market Revenue Billion Forecast, by Recycling Process 2020 & 2034
Table 2: Global PET Bottle Recycling Market Revenue Billion Forecast, by Output Type 2020 & 2034
Table 3: Global PET Bottle Recycling Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 4: Global PET Bottle Recycling Market Revenue Billion Forecast, by Collection Source 2020 & 2034
Table 5: Global PET Bottle Recycling Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America PET Bottle Recycling Market Revenue Billion Forecast, by Recycling Process 2020 & 2034
Table 7: North America PET Bottle Recycling Market Revenue Billion Forecast, by Output Type 2020 & 2034
Table 8: North America PET Bottle Recycling Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 9: North America PET Bottle Recycling Market Revenue Billion Forecast, by Collection Source 2020 & 2034
Table 10: North America PET Bottle Recycling Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe PET Bottle Recycling Market Revenue Billion Forecast, by Recycling Process 2020 & 2034
Table 15: Europe PET Bottle Recycling Market Revenue Billion Forecast, by Output Type 2020 & 2034
Table 16: Europe PET Bottle Recycling Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 17: Europe PET Bottle Recycling Market Revenue Billion Forecast, by Collection Source 2020 & 2034
Table 18: Europe PET Bottle Recycling Market Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: France PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: UK PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Italy PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Spain PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Netherlands PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Asia Pacific PET Bottle Recycling Market Revenue Billion Forecast, by Recycling Process 2020 & 2034
Table 26: Asia Pacific PET Bottle Recycling Market Revenue Billion Forecast, by Output Type 2020 & 2034
Table 27: Asia Pacific PET Bottle Recycling Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 28: Asia Pacific PET Bottle Recycling Market Revenue Billion Forecast, by Collection Source 2020 & 2034
Table 29: Asia Pacific PET Bottle Recycling Market Revenue Billion Forecast, by Country 2020 & 2034
Table 30: China PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Japan PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: India PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: South Korea PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Southeast Asia PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: South America PET Bottle Recycling Market Revenue Billion Forecast, by Recycling Process 2020 & 2034
Table 36: South America PET Bottle Recycling Market Revenue Billion Forecast, by Output Type 2020 & 2034
Table 37: South America PET Bottle Recycling Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 38: South America PET Bottle Recycling Market Revenue Billion Forecast, by Collection Source 2020 & 2034
Table 39: South America PET Bottle Recycling Market Revenue Billion Forecast, by Country 2020 & 2034
Table 40: Brazil PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Argentina PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Chile PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Middle East & Africa PET Bottle Recycling Market Revenue Billion Forecast, by Recycling Process 2020 & 2034
Table 44: Middle East & Africa PET Bottle Recycling Market Revenue Billion Forecast, by Output Type 2020 & 2034
Table 45: Middle East & Africa PET Bottle Recycling Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 46: Middle East & Africa PET Bottle Recycling Market Revenue Billion Forecast, by Collection Source 2020 & 2034
Table 47: Middle East & Africa PET Bottle Recycling Market Revenue Billion Forecast, by Country 2020 & 2034
Table 48: South Africa PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: UAE PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Saudi Arabia PET Bottle Recycling Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the PET bottle recycling market?
The global PET bottle recycling market was valued at USD 10.4 billion in 2024 and is projected to reach USD 18.5 billion by 2035, growing at a CAGR of 5.4% from 2025 to 2035, according to our proprietary research.
2Which region dominates the PET bottle recycling market?
Asia-Pacific holds the largest volume share at approximately 42% in 2024, driven by China and India's extensive collection and processing infrastructure, while Europe leads in regulatory-driven high-value rPET demand with a 27% market share.
3What is driving the growth of chemical recycling in PET bottle recycling?
Chemical recycling is the fastest-growing segment at a CAGR of 13.2%, as it can process colored, multilayered, and contaminated PET into virgin-equivalent monomers, enabling food-grade rPET production from feedstocks that mechanical recycling cannot handle.
4How do deposit return schemes (DRS) impact the PET bottle recycling market?
DRS schemes, such as those in South Australia and Ecuador, have increased PET bottle collection rates by 30–50 percentage points. For example, Ecuador's DRS raised PET recycling from 30% in 2011 to 80% in 2012, significantly improving feedstock quality and supply.
5Who are the key players in the PET bottle recycling market?
Major companies include Indorama Ventures, Plastipak Holdings, Veolia Environnement, SUEZ Recycling and Recovery, Clear Path Recycling, CarbonLITE Industries, KW Plastics, Evergreen Plastics, and Phoenix Technologies International.
6What are the main challenges facing the PET bottle recycling market?
High operational costs, virgin PET price volatility, and quality issues such as discoloration and contamination are key restraints. Our interviews indicate that 30% of mechanically recycled PET fails food-grade certification due to contamination, limiting its use in beverage bottles.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 182 in-depth interviews with key stakeholders across the PET bottle recycling value chain, including PET bottle collectors and MRF operators, mechanical and chemical recyclers, rPET compounders and converters, brand owners and packaging converters, and EPR scheme administrators and policymakers.
Interviews were distributed across 22 countries, with a focus on Europe (35%), Asia-Pacific (40%), North America (20%), and other regions (5%), ensuring coverage of both mature and emerging markets.
Job titles interviewed include Procurement Director (35%), Sustainability Manager (25%), Operations Director (20%), and Policy Advisor (20%), ensuring a 360-degree view of market dynamics.
Primary research accounted for 70-80% of total research effort, with each interview lasting 45-60 minutes and capturing quantitative and qualitative insights.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
Sustainability Manager
25%
Operations Director
20%
Policy Advisor
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
PET Bottle Collectors & MRF Operators
25%
Mechanical & Chemical Recyclers
30%
rPET Compounders & Converters
20%
Brand Owners & Packaging Converters
15%
EPR Scheme Administrators & Policymakers
10%
Secondary Research & Industry Benchmarking
We triangulated primary findings with 20-30% secondary research from official multilateral sources, including UN Comtrade for trade flows, OECD for policy benchmarks (e.g., DRS case studies), the World Bank for waste management data, and Eurostat for European collection rates.
Industry association data from Plastics Recyclers Europe (PRE), the Association of Plastic Recyclers (APR), and the National Association for PET Container Resources (NAPCOR) were used to validate recycling rates and capacities.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook were used to assess company financials, M&A activity, and investment trends.
All secondary sources are official .gov, .org, or recognized non-profit trade associations; no commercial market research reports were used.
Demand Modeling & Market Estimation
We employed a simultaneous top-down and bottom-up approach. The bottom-up model built market size from unit-level metrics: PET bottle collection volumes (in kilotonnes), recycling yields by process (mechanical vs. chemical), average selling prices for rPET flakes and pellets, and end-use consumption by application.
Key quantitative metrics included: annual PET bottle waste generation (from OECD and national waste registries), collection rate by scheme (DRS vs. curbside), recycling capacity utilization rates (from company disclosures), and rPET content mandates by jurisdiction.
The top-down approach used global PET production data (from trade associations) and applied recycling rates to derive feedstock availability, cross-checked with brand-owner recycled content pledges.
Multi-level data triangulation reconciled discrepancies between bottom-up and top-down estimates, with variances exceeding 10% subjected to further primary validation.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90%, achieved through three rounds of validation: preliminary findings were cross-checked with a subset of 30 interviewees, then benchmarked against official statistics, and finally reviewed by our internal expert panel.
Every data point is traceable to at least two independent sources (primary and secondary), and all market size figures are rounded to the nearest USD 0.1 billion to reflect precision levels.
The report is updated to the date of purchase, with a dedicated analyst available for post-purchase clarifications and data refresh requests.