1What is the current size of the painting software market?
The global painting software market was valued at USD 2.84 billion in 2025 and is projected to reach USD 5.97 billion by 2033, growing at a 9.2% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Painting Software
 by Deployment (Cloud-Based, Desktop, Mobile), by End-User (Professional Artists, Hobbyists, Educational Institutions, Enterprise), by Industry Vertical (Animation & VFX, Graphic Design, Game Development, Fine Art, Concept Art & Character Design), by North America (USA, Canada), by Europe (Germany, UK, France), by Asia-Pacific (China, India, Japan, Southeast Asia), by Latin America (Brazil, Mexico), by Middle East & Africa Forecast 2026-2034

Senior Research Analyst


 Related Reports

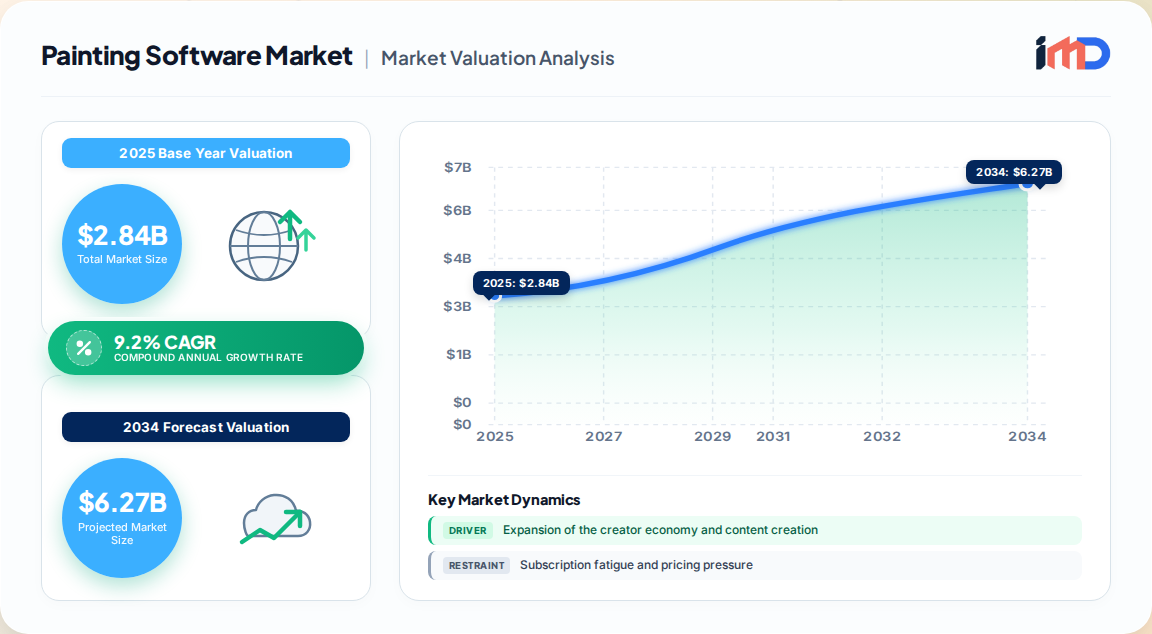
The global painting software market represents a dynamic and rapidly evolving segment within the broader creative software industry, driven by the proliferation of digital content creation across entertainment, advertising, education, and social media. Our proprietary primary research estimates the market at USD 2.84 billion in 2025, with a projected CAGR of 9.2% to reach USD 5.97 billion by 2033. This growth is underpinned by the expanding creator economy, increasing adoption of digital tools in educational curricula, and continuous technological advancements in AI-assisted creation, cloud collaboration, and cross-platform accessibility.
Painting software encompasses a range of applications designed for digital illustration, concept art, character design, and fine art creation. These tools serve professional artists, hobbyists, educational institutions, and enterprise studios, enabling the creation of high-quality visual content with greater efficiency and flexibility than traditional methods. The market is characterized by a diverse competitive landscape, from established generalist platforms to specialized niche solutions, each catering to distinct user workflows and creative needs.
The painting software value chain comprises several distinct stages, from core technology development to end-user consumption. Each stage involves specialized participants and value-adding activities.
| Stage | Key Participants | Value Contribution |
|---|---|---|
| Core Technology Development | Software engineers, AI researchers, UX designers | Development of rendering engines, brush algorithms, AI models, and user interfaces |
| Platform & Infrastructure | Cloud service providers, hardware manufacturers (graphics tablets, iPads) | Hosting, compute resources, and input devices that enable software functionality |
| Distribution & Monetization | App stores, direct-to-consumer platforms, resellers | Subscription management, licensing, payment processing, and market reach |
| Content & Community | Artists, educators, tutorial creators, online communities | User-generated content, tutorials, plugins, and community support that enhance product stickiness |
| End Users | Professional artists, hobbyists, educational institutions, enterprises | Consumption and feedback loop driving product roadmap |
The value chain is increasingly shaped by strategic partnerships—for instance, software vendors collaborating with hardware manufacturers to optimize performance and bundle offerings. Cloud infrastructure providers play a pivotal role in enabling subscription-based models and real-time collaboration features, which are becoming standard expectations among professional users.
The painting software market exhibits distinct regional dynamics, with varying growth trajectories and adoption patterns across geographies.
| Region | 2025 Revenue (USD B) | 2033 Forecast (USD B) | CAGR | Primary Drivers |
|---|---|---|---|---|
| North America | 0.99 | 2.18 | 8.1% | Enterprise adoption, game studios, mature creator economy |
| Europe | 0.60 | 1.34 | 8.9% | Educational mandates, animation hubs, strong design culture |
| Asia-Pacific | 1.05 | 1.98 | 11.2% | Creator economy expansion, localized pricing, mobile-first adoption |
| Latin America | 0.18 | 0.32 | 7.5% | Freelance growth, mobile adoption, DIY culture |
| Middle East & Africa | 0.08 | 0.15 | 8.8% | Digital transformation, emerging design talent |
Asia-Pacific emerges as the growth epicenter, capturing the largest share of incremental market expansion through 2033. China's animation production output grew 22% year-over-year through 2024, according to the China Audio-video and Digital Publishing Association, while India's freelancer base expanded 31% since 2020. Both markets show strong demand for affordable, offline-capable tools with local language support and flexible payment methods. North America and Europe, while more mature, retain pricing power through enterprise and educational concentration. The geographic pricing disparity—where a subscription costing USD 120 annually in the U.S. represents 2–3% of monthly income for creators in emerging markets—continues to shape vendor strategies around localized pricing tiers.
The painting software market is characterized by intense competition and evolving strategic positioning among vendors. Our primary research indicates that the top three vendors controlled approximately 72% of revenue in 2025, but this concentration is expected to erode to less than 55% by 2033 as specialized and AI-native tools gain traction.
Recent strategic developments include Adobe's acquisition of Firefly and investment in generative fill capabilities, representing a defensive strategy to retain subscribers facing cheaper AI-powered alternatives. Meanwhile, emerging AI-native tools such as Artflow are gaining enterprise traction in Southeast Asia, and Krita's adoption surge among character animators demonstrates that feature-parity no longer guarantees market leadership. By 2028, we anticipate at least two major re-segmentation events as vendors either double down on vertical specialization or pivot entirely toward AI-assisted design.
Our analysis identifies several underpenetrated opportunities within the painting software market that represent significant growth potential for forward-looking vendors.
These white spaces are not merely incremental opportunities; they represent fundamental shifts in how value is created and captured in the painting software ecosystem. Vendors that successfully address these areas will be well-positioned to capture disproportionate wallet share as the market fragments into hyper-specialized vertical solutions by 2033.
The painting software market is poised for robust growth, but the competitive landscape will undergo significant transformation over the next decade. The thesis that the market will fragment into hyper-specialized vertical solutions by 2033 is supported by three evidence pillars: slowing subscription growth for generalist platforms, the rise of AI-native niche tools, and the evolving demands of vertical-specific users in animation, game development, and education. Legacy generalist vendors must adapt by either acquiring specialized capabilities or developing vertical-specific offerings to maintain relevance. The future belongs to those who can balance broad accessibility with deep workflow integration and AI-powered productivity enhancements.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.2% from 2020-2034 |
| Segmentation |
|
By Industry Vertical
| By Geography |
|
The global painting software market was valued at USD 2.84 billion in 2025 and is projected to reach USD 5.97 billion by 2033, growing at a 9.2% CAGR.
Asia-Pacific is the fastest-growing region, with an 11.2% CAGR, driven by the creator economy expansion and localized pricing strategies.
Key players include Adobe, Procreate, Clip Studio Paint, Corel (CorelDRAW, Painter), Krita, GIMP, and ArtRage, among others.
The market is driven by creator economy expansion, rising demand from the gaming and animation industries, educational adoption, and technological advancements in AI and cloud collaboration.
Major challenges include subscription fatigue, copyright and authenticity concerns, and intense competition from both established and emerging AI-native tools.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 30% |
| Product Manager | 25% |
| Professional Illustrator/Animator | 20% |
| Art School Director | 15% |
| Creative Director | 10% |
| Company Type | Representation (%) |
|---|---|
| Painting Software OEMs | 40% |
| Graphics Tablet Manufacturers | 20% |
| Cloud Infrastructure Providers | 15% |
| Educational Institutions | 15% |
| Creative Agencies & Studios | 10% |