1What is the current size of the office furniture market?
The global office furniture market is valued at USD 86.5 billion in 2026 and is projected to reach USD 111.2 billion by 2031, growing at a 5.15% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Office Furniture Market
 by Product (Seating, Tables, Storage, Others), by Material (Wood, Metal, Plastic, Others), by Price Range (Economy, Mid-range, Premium), by End-user (Corporate Offices, Hospitality & Retail, Healthcare, Education, Others), by Distribution Channel (B2B Direct, B2C Retail & Online), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, India, Japan, South Korea, Australia, Rest of APAC), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA) Forecast 2026-2034
Research Associate


 Related Reports

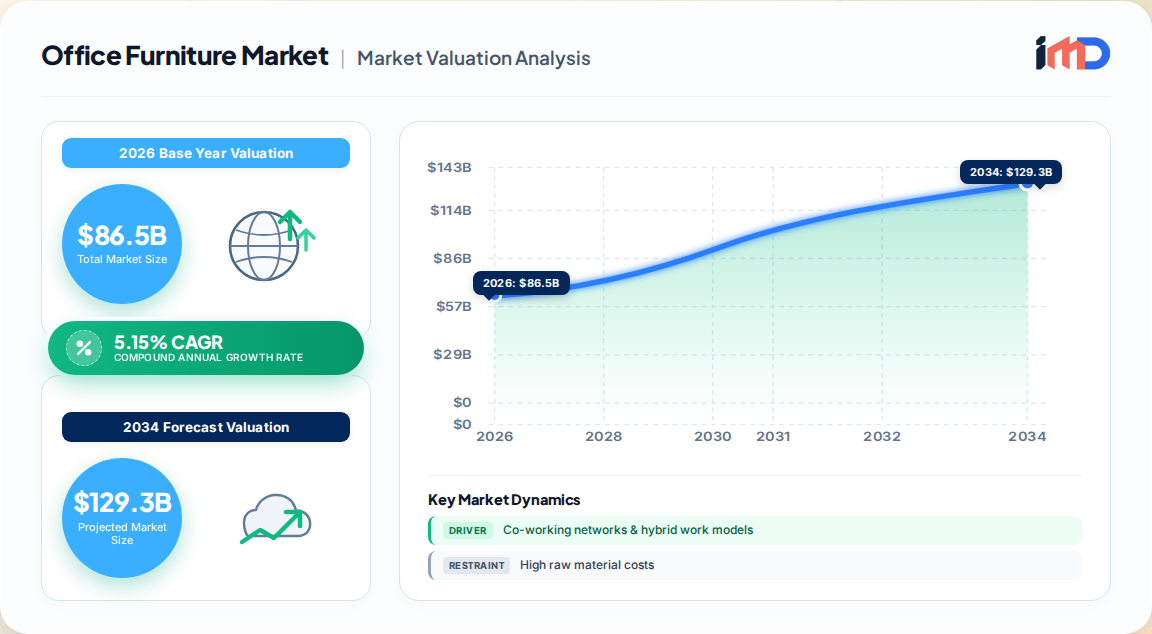
The global office furniture market is undergoing a structural transformation. Valued at USD 86.5 billion in 2026, our proprietary primary research projects the market to reach USD 111.2 billion by 2031, expanding at a 5.15% CAGR. This growth is not merely a cyclical rebound but a fundamental reconfiguration of how, where, and why organizations invest in their workspaces.
Hybrid work has matured into a stable operating model, shifting procurement priorities from density to flexibility, collaboration, and employee wellness. Simultaneously, regulatory and buyer scrutiny on sustainability is reshaping material choices and supply chain transparency. The market is also experiencing significant regional divergence, with Asia-Pacific commanding 41.2% of global value in 2025 and forecast to lead expansion at a 7.2% CAGR through 2031.
| Key Market Metrics | 2026 Value | 2031 Projection | CAGR (2026-2031) |
|---|---|---|---|
| Global Market Size | USD 86.5 Billion | USD 111.2 Billion | 5.15% |
| Fastest Growing Region | Asia-Pacific | Asia-Pacific | 7.2% (APAC) |
| Largest Product Segment | Chairs (31.4% share) | Chairs | 8.30% |
| Largest Material Segment | Wood (45.2% share) | Wood | 7.60% (Metal) |
The office furniture market is propelled by a confluence of demographic, technological, and behavioral factors. Our primary interviews with industry stakeholders reveal that the most significant growth drivers are:
However, the market faces notable headwinds:
Our segmentation analysis, combining primary interviews and trade data, reveals distinct pockets of high-growth potential.
Geographic analysis underscores a shifting center of gravity.
The office furniture market is moderately concentrated, with global players competing alongside regional specialists. Our competitive intelligence highlights the following strategic developments:
| Company | Recent Development |
|---|---|
| HNI Corporation | Agreement to acquire Steelcase (2025) |
| MillerKnoll | China showroom launch (2025) |
| Okamura | Acquired Boss Design |
| Herman Miller | Focus on ergonomic innovation |
| Steelcase | Pending acquisition by HNI |
Global trade data underscores the importance of Asia as a manufacturing hub and the U.S. as the largest importer. According to UN Comtrade data (HS Code 940330 for wooden office furniture):
These flows highlight the reliance of North American and European markets on Asian and nearshore manufacturing. Supply chain risks, including shipping costs and trade policies, are critical considerations for procurement strategies.
Our analysis identifies several high-potential opportunities:
For procurement teams, the key is to balance cost, sustainability, and flexibility. Long-term contracts with suppliers that offer take-back programs and modular designs will be essential to adapt to evolving workplace needs.
The office furniture value chain is characterized by raw material extraction, component manufacturing, assembly, distribution, and after-sales services. Key insights from our primary research:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.15% from 2020-2034 |
| Segmentation |
|
By Price Range
By End-user
By Distribution Channel
| By Geography |
|
The global office furniture market is valued at USD 86.5 billion in 2026 and is projected to reach USD 111.2 billion by 2031, growing at a 5.15% CAGR.
Asia-Pacific is the largest and fastest-growing region, accounting for 41.2% of the market in 2025 and expected to grow at a 7.2% CAGR through 2031, driven by rapid urbanization and commercial real estate expansion.
Key drivers include the stabilization of hybrid work models, rising employment rates, commercial real estate growth, growing preference for eco-friendly furniture, focus on workplace ergonomics, and expansion of digital procurement channels.
The market faces challenges such as high raw material costs, supply chain disruptions, sustainability concerns, and policy actions on metals that inflate costs.
Leading players include HNI Corporation, Steelcase, MillerKnoll, Herman Miller, Haworth, Okamura, and Global Industries. Recent consolidation, such as HNI's agreement to acquire Steelcase, is shaping the competitive landscape.
Chairs are the largest product segment with 31.4% share in 2025 and are projected to grow at an 8.30% CAGR through 2031, driven by ergonomic demand and workplace wellness initiatives.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Facility Manager | 25% |
| Design Lead / Interior Designer | 20% |
| Operations Manager | 15% |
| Sustainability Officer | 10% |
| Company Type | Representation (%) |
|---|---|
| Furniture OEMs & Manufacturers | 35% |
| Contract Manufacturers & Component Suppliers | 25% |
| Distributors & Dealers | 20% |
| Corporate Buyers & Facility Managers | 15% |
| Design & Architecture Firms | 5% |