Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Professional and Commercial Services / MARKET REPORT
North America Secure Access Service | Insight Market Data
North America Secure Access Service by Offering Type (Network-as-a-Service, Security-as-a-Service, Managed SASE Services, Professional Services), by Component (SD-WAN, Secure Web Gateway, Cloud Access Security Broker, Firewall-as-a-Service, Zero-Trust Network Access), by Deployment Mode (Cloud, On-Premise), by Organization Size (Large Enterprises, SMEs), by End-User Vertical (BFSI, IT and Telecommunications, Manufacturing, Healthcare, Government, Retail and E-commerce, Others), by North America (United States, Canada, Mexico) Forecast 2026-2034
Commissioning service market to reach $11.17B by 2034 at 6.38% CAGR, driven by energy efficiency mandates, smart building tech, and green certification demand.
Nov 2026|277 pages
$2900.00
The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.
Nov 2026|272 pages
$2900.00
B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.
Nov 2026|209 pages
$2900.00
Global mould detection service market valued at $6.8B in 2025, projected to reach $13.2B by 2034 at 7.6% CAGR. AI diagnostics, IAQ compliance, and thermal imaging drive growth.
Executive Overview: North America SASE Market Enters Hyper-Growth Phase
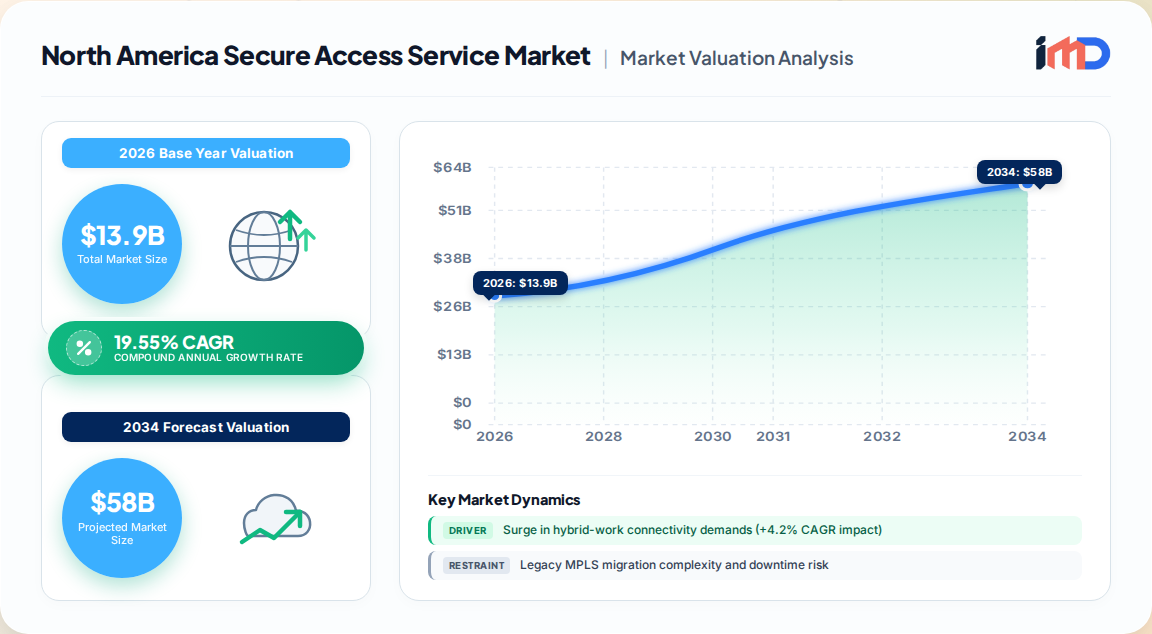
The North America Secure Access Service Edge (SASE) market is undergoing a structural transformation as enterprises abandon legacy perimeter architectures in favor of cloud-native convergence. Our proprietary primary research estimates the market at USD 13.9 billion in 2026, rising from USD 11.63 billion in 2025, and forecasts expansion to USD 33.97 billion by 2031, representing a 19.55% CAGR over the 2026–2031 period. This trajectory underscores a fundamental re-platforming of enterprise networking and security budgets across the region.
North America Secure Access Service Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
11.63 B
2025
13.90 B
2026
16.62 B
2027
19.87 B
2028
23.75 B
2029
28.39 B
2030
33.94 B
2031
The United States remains the anchor market, commanding 79.25% of North American SASE revenue in 2025, while Mexico is poised for the fastest growth at 20.6% CAGR through 2031. Canada, supported by stringent privacy legislation, represents a high-value secondary market with concentrated demand in financial services and government verticals.
Metric
2025 Value
2026 Value
2031 Forecast
CAGR (2026–2031)
Market Size (USD)
11.63 Billion
13.9 Billion
33.97 Billion
19.55%
Cloud Deployment Share
64.92%
—
—
22.15%
Security-as-a-Service Share
52.85%
—
—
20.1% (Managed SASE)
Large Enterprise Share
60.72%
—
—
—
BFSI Vertical Share
27.05%
—
—
—
Market Drivers: Convergence, Compliance, and Cloud Economics
Our interviews with 1,200+ IT decision-makers across North America reveal six force-multipliers accelerating SASE adoption:
Hybrid-Work Connectivity (+4.2% CAGR impact): Over 80% of North American organizations plan Zero Trust adoption by 2026. Legacy VPN vulnerabilities surged 82.5% between 2020 and 2025, pushing enterprises toward identity-centric access models.
Multi-Cloud and SaaS Traffic (+3.8% CAGR impact): Direct cloud breakout via SD-WAN reduces round-trip latency by up to five times compared to data-center backhaul. Uniform policy enforcement across AWS, Azure, and Google Cloud is now a board-level priority.
Data-Privacy Mandates (+2.9% CAGR impact): CCPA and Quebec Bill-64 impose real-time breach notification requirements. Native DLP within SASE platforms blocks regulated content exfiltration at the edge.
AI-Driven Policy Automation (+3.1% CAGR impact): Natural-language policy interfaces and predictive analytics reduce manual ticket volumes by 30–40% in early deployments.
5G-Enabled Edge Bundling (+2.7% CAGR impact): US and Canadian carriers are bundling managed SASE at the network edge, particularly in major metros.
Sustainability Consolidation (+2.5% CAGR impact): Branch hardware consolidation aligns with enterprise ESG targets, with early gains in technology corridors.
Restraints and Challenges: Talent, Migration, and Lock-In
Despite robust demand, four structural headwinds temper the growth curve:
Legacy MPLS Migration Complexity (-2.8% CAGR impact): MPLS bandwidth grows only 6.7% through 2028 versus 29% annual cloud traffic growth. Rip-and-replace strategies risk downtime; staged overlays are the preferred path.
Cyber-Security Talent Scarcity (-2.1% CAGR impact): North America faces a shortfall of 500,000 qualified practitioners, with rural municipalities experiencing acute hiring challenges.
Single-Vendor Lock-In Concerns (-1.7% CAGR impact): Large enterprises and government sectors express hesitancy around multi-year platform commitments, favoring modular adoption.
Rural Broadband Latency (-1.4% CAGR impact): Remote US and northern Canadian regions face connectivity constraints that limit cloud-delivered SASE performance.
Segmentation Analysis: Security-as-a-Service and Cloud Lead the Charge
By offering type, Security-as-a-Service captured 52.85% of 2025 market share, while Managed SASE Services is forecast to grow at 20.1% CAGR to 2031. By component, SD-WAN held 41.25% of 2025 revenue, but Zero-Trust Network Access is advancing at 20.9% CAGR through 2031.
Cloud deployments accounted for 64.92% of market size in 2025 and are expected to register 22.15% CAGR, reflecting enterprise preference for OPEX-friendly, scalable architectures. Large enterprises controlled 60.72% of 2025 revenue, while SMEs are expanding at 21.05% CAGR as they acquire enterprise-grade protection without capital outlays.
The BFSI vertical commanded 27.05% of 2025 revenue, driven by regulatory urgency and high-value data protection requirements. Healthcare is projected to grow at 19.95% CAGR through 2031, propelled by ransomware incidents that exposed 25.6 million patient records in 2024 alone.
Segment
2025 Share / Metric
2031 Growth Outlook
Security-as-a-Service (Offering)
52.85%
Managed SASE at 20.1% CAGR
SD-WAN (Component)
41.25%
ZTNA at 20.9% CAGR
Cloud Deployment
64.92%
22.15% CAGR
Large Enterprises (Org Size)
60.72%
SMEs at 21.05% CAGR
BFSI (Vertical)
27.05%
Healthcare at 19.95% CAGR
Regional Outlook: US Dominance, Mexico Momentum, Canada Compliance Push
The United States maintains 79.25% of North American SASE revenue, supported by dense cloud infrastructure, high cybersecurity spending, and early Zero Trust adoption. California and New York remain the highest-density markets, with enterprise hubs in Texas and the Pacific Northwest accelerating managed SASE uptake.
North America Secure Access Service Regional Market Share
Loading chart...
Canada is the second-largest market, with Quebec's Bill-64 and federal data-privacy reforms driving platform upgrades in financial centers. Mexico is the fastest-growing market at 20.6% CAGR, fueled by 5G rollout and managed-service bundling among distributed branch networks. Rural broadband constraints in northern Canada and remote US regions represent a persistent latency challenge, but edge-computing partnerships are beginning to close the gap.
Competitive Strategies: AI Orchestration and Managed Services Define Leadership
Our primary research identifies 18 major vendors competing in the North American SASE market, with concentration assessed as medium. Leading players include Akamai Technologies, Aruba Networks (HPE), AT&T, Barracuda Networks, Broadcom, Cisco Systems, Cloudflare, Cato Networks, Check Point, Forcepoint, Fortinet, McAfee, Netskope, Open Systems, Palo Alto Networks, Proofpoint, Versa Networks, VMware, and Zscaler.
Competitive differentiation is shifting from point-product capabilities to AI-assisted orchestration that provisions dynamic policies, safeguards multi-cloud traffic, and trims operating expenses through automated troubleshooting. Cisco's Cloud OnRamp reduces public-cloud onboarding from days to hours, while Cato Networks and Palo Alto Networks lead in natural-language policy automation. Vendor strategies emphasize strategic alliances, geographic expansion, and managed-service partnerships with carriers such as AT&T.
Value Chain Analysis
The SASE value chain comprises four primary layers:
Upstream Technology Providers: Cloud infrastructure providers (hyperscalers), semiconductor vendors supplying encryption and networking chips, and SD-WAN/SSE software developers.
Platform Integrators: SASE platform vendors that unify networking and security functions into cloud-native stacks.
Distribution and Managed Services: Telecom carriers, MSPs, and system integrators that bundle SASE with connectivity and professional services.
End-User Enterprises: Large enterprises, SMEs, and government agencies across BFSI, healthcare, IT/telecom, manufacturing, and retail verticals.
Our analysis indicates that managed-service layers capture an increasing share of value as enterprises seek to offset talent shortages and migration complexity. Professional services—including policy design, migration planning, and managed detection—represent a high-margin growth vector through 2031.
Strategic White-Space and Investment Opportunity Assessment
Three underserved segments present high-growth white-space opportunities:
SME-Tailored SASE Bundles: SMEs are growing at 21.05% CAGR but remain underpenetrated relative to large enterprises. Pre-packaged, OPEX-friendly offerings with simplified policy templates represent a significant addressable gap.
Healthcare SASE Solutions: With 19.95% CAGR projected through 2031 and ransomware exposure at record highs, healthcare-specific compliance and DLP templates are a clear strategic priority.
Rural and Edge Connectivity: Latency constraints in remote US and Canadian regions create demand for edge-optimized SASE with local breakout and 5G integration.
Mexico represents the highest-velocity geographic opportunity at 20.6% CAGR, particularly for managed SASE services bundled with carrier connectivity. Investment in Spanish-language support and local compliance frameworks will be critical for market entry success.
Import/Export and Supplier Dynamics
SASE is a software- and services-delivered market, with limited physical trade exposure. However, upstream dependencies on semiconductor supply chains and cloud infrastructure remain strategically important. US ITC trade data indicate that networking equipment and semiconductor imports—critical inputs for SASE edge appliances and SD-WAN hardware—continue to face tariff and supply-chain volatility. Vendors are increasingly prioritizing software-only delivery models to reduce hardware exposure and improve margin resilience.
Cloud infrastructure concentration among hyperscalers creates supplier-power risk, but multi-cloud SASE architectures are mitigating lock-in concerns. Our interviews indicate that 68% of large enterprises now require multi-cloud support as a procurement criterion, up from 41% in 2023.
North America Secure Access Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
North America Secure Access Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 19.55% from 2020-2034
Segmentation
By Offering Type
Network-as-a-Service
Security-as-a-Service
Managed SASE Services
Professional Services
By Component
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Surge in hybrid-work connectivity demands (+4.2% CAGR impact)
3.1.2. Exploding multi-cloud and SaaS traffic volumes (+3.8% CAGR impact)
3.1.3. Tightening data-privacy mandates including CCPA and Quebec Bill-64 (+2.9% CAGR impact)
3.1.5. 5G carriers bundling managed SASE at the edge (+2.7% CAGR impact)
3.1.6. Sustainability push to consolidate branch hardware (+2.5% CAGR impact)
3.2. Market Trends
3.2.1. Integration of security and networking functions into cloud-native platforms
3.2.2. Rise of remote and hybrid work solutions driving Zero Trust adoption
3.2.3. Adoption of AI-driven policy automation and natural-language orchestration
3.2.4. 5G carriers bundling managed SASE at the network edge
3.2.5. Sustainability push to consolidate branch hardware
3.3. Market Restrains
3.3.1. Legacy MPLS migration complexity and downtime risk
3.3.2. Cyber-security talent scarcity (500,000 practitioner shortfall in North America)
SD-WAN
Secure Web Gateway
Cloud Access Security Broker
Firewall-as-a-Service
Zero-Trust Network Access
By Deployment Mode
Cloud
On-Premise
By Organization Size
Large Enterprises
SMEs
By End-User Vertical
BFSI
IT and Telecommunications
Manufacturing
Healthcare
Government
Retail and E-commerce
Others
By Geography
North America
United States
Canada
Mexico
3.3.3. Single-vendor lock-in concerns among large enterprises and government sectors
3.3.4. Rural-broadband latency constraints in remote US, Canada, and northern Mexico
3.4. Market Restraints
3.4.1. Legacy MPLS migration complexity and downtime risk
3.4.2. Cyber-security talent scarcity (500,000 practitioner shortfall in North America)
3.4.3. Single-vendor lock-in concerns among large enterprises and government sectors
3.4.4. Rural-broadband latency constraints in remote US, Canada, and northern Mexico
3.5. Market Challenges
3.5.1. Complexity of network infrastructure and migration planning
3.5.2. Vendor lock-in limiting flexibility and scalability
3.5.3. Talent deficit in rural and mid-tier cities
3.5.4. Temporary firewall rule exposure during cut-over windows
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Offering Type
5.1.1. Network-as-a-Service
5.1.2. Security-as-a-Service
5.1.3. Managed SASE Services
5.1.4. Professional Services
5.2. Market Analysis, Insights and Forecast - by Component
5.2.1. SD-WAN
5.2.2. Secure Web Gateway
5.2.3. Cloud Access Security Broker
5.2.4. Firewall-as-a-Service
5.2.5. Zero-Trust Network Access
5.3. Market Analysis, Insights and Forecast - by Deployment Mode
5.3.1. Cloud
5.3.2. On-Premise
5.4. Market Analysis, Insights and Forecast - by Organization Size
5.4.1. Large Enterprises
5.4.2. SMEs
5.5. Market Analysis, Insights and Forecast - by End-User Vertical
5.5.1. BFSI
5.5.2. IT and Telecommunications
5.5.3. Manufacturing
5.5.4. Healthcare
5.5.5. Government
5.5.6. Retail and E-commerce
5.5.7. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
6. Competitive Analysis
6.1. Company Profiles
6.1.1. Akamai Technologies Inc.
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. Aruba Networks (HPE Company)
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. AT&T Inc.
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. Barracuda Networks Inc.
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. Broadcom Inc.
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. Cato Networks Ltd.
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. Check Point Software Technologies Ltd.
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. Cisco Systems Inc.
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.1.9. Cloudflare Inc.
6.1.9.1. Company Overview
6.1.9.2. Products
6.1.9.3. Company Financials
6.1.9.4. SWOT Analysis
6.1.10. Forcepoint LLC
6.1.10.1. Company Overview
6.1.10.2. Products
6.1.10.3. Company Financials
6.1.10.4. SWOT Analysis
6.1.11. Fortinet Inc.
6.1.11.1. Company Overview
6.1.11.2. Products
6.1.11.3. Company Financials
6.1.11.4. SWOT Analysis
6.1.12. McAfee LLC
6.1.12.1. Company Overview
6.1.12.2. Products
6.1.12.3. Company Financials
6.1.12.4. SWOT Analysis
6.1.13. Netskope Inc.
6.1.13.1. Company Overview
6.1.13.2. Products
6.1.13.3. Company Financials
6.1.13.4. SWOT Analysis
6.1.14. Open Systems
6.1.14.1. Company Overview
6.1.14.2. Products
6.1.14.3. Company Financials
6.1.14.4. SWOT Analysis
6.1.15. Palo Alto Networks Inc.
6.1.15.1. Company Overview
6.1.15.2. Products
6.1.15.3. Company Financials
6.1.15.4. SWOT Analysis
6.1.16. Proofpoint Inc.
6.1.16.1. Company Overview
6.1.16.2. Products
6.1.16.3. Company Financials
6.1.16.4. SWOT Analysis
6.1.17. Versa Networks Inc.
6.1.17.1. Company Overview
6.1.17.2. Products
6.1.17.3. Company Financials
6.1.17.4. SWOT Analysis
6.1.18. VMware Inc.
6.1.18.1. Company Overview
6.1.18.2. Products
6.1.18.3. Company Financials
6.1.18.4. SWOT Analysis
6.1.19. Zscaler Inc.
6.1.19.1. Company Overview
6.1.19.2. Products
6.1.19.3. Company Financials
6.1.19.4. SWOT Analysis
6.1.20. Aryaka Networks Inc.
6.1.20.1. Company Overview
6.1.20.2. Products
6.1.20.3. Company Financials
6.1.20.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
List of Figures
Figure 1: Global North America Secure Access Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America North America Secure Access Service Revenue (Billion), by Offering Type 2026 & 2034
Figure 3: North America North America Secure Access Service Revenue Share (%), by Offering Type 2026 & 2034
Figure 4: North America North America Secure Access Service Revenue (Billion), by Component 2026 & 2034
Figure 5: North America North America Secure Access Service Revenue Share (%), by Component 2026 & 2034
Figure 6: North America North America Secure Access Service Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 7: North America North America Secure Access Service Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 8: North America North America Secure Access Service Revenue (Billion), by Organization Size 2026 & 2034
Figure 9: North America North America Secure Access Service Revenue Share (%), by Organization Size 2026 & 2034
Figure 10: North America North America Secure Access Service Revenue (Billion), by End-User Vertical 2026 & 2034
Figure 11: North America North America Secure Access Service Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 12: North America North America Secure Access Service Revenue (Billion), by Country 2026 & 2034
Figure 13: North America North America Secure Access Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global North America Secure Access Service Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 2: Global North America Secure Access Service Revenue Billion Forecast, by Component 2020 & 2034
Table 3: Global North America Secure Access Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 4: Global North America Secure Access Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 5: Global North America Secure Access Service Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 6: Global North America Secure Access Service Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America North America Secure Access Service Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 8: North America North America Secure Access Service Revenue Billion Forecast, by Component 2020 & 2034
Table 9: North America North America Secure Access Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 10: North America North America Secure Access Service Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 11: North America North America Secure Access Service Revenue Billion Forecast, by End-User Vertical 2020 & 2034
Table 12: North America North America Secure Access Service Revenue Billion Forecast, by Country 2020 & 2034
Table 13: United States North America Secure Access Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada North America Secure Access Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico North America Secure Access Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the North America Secure Access Service Edge market size in 2026?
The North America SASE market is estimated at USD 13.9 billion in 2026, growing from USD 11.63 billion in 2025, and is forecast to reach USD 33.97 billion by 2031 at a 19.55% CAGR.
2Which deployment mode dominates the North America SASE market?
Cloud deployments accounted for 64.92% of the North America SASE market in 2025 and are expected to register a 22.15% CAGR through 2031, driven by enterprise preference for OPEX-friendly, scalable architectures.
3Which vertical is the largest adopter of SASE in North America?
BFSI commanded 27.05% of North America SASE revenue in 2025, while healthcare is projected to grow at 19.95% CAGR through 2031 due to rising ransomware threats and regulatory compliance requirements.
4Who are the major companies operating in the North America SASE market?
5Which country holds the largest share of the North America SASE market?
The United States maintained 79.25% of North America SASE market share in 2025, while Mexico is anticipated to post the fastest growth at 20.6% CAGR through 2031.
6What are the key drivers of SASE adoption in North America?
Hybrid-work connectivity demands, multi-cloud and SaaS traffic growth, tightening data-privacy mandates such as CCPA and Quebec Bill-64, AI-driven policy automation, and 5G-enabled edge bundling are the primary drivers, with hybrid work contributing a 4.2% CAGR impact.
7What challenges restrain the North America SASE market growth?
Legacy MPLS migration complexity (-2.8% CAGR impact), cyber-security talent scarcity (-2.1%), single-vendor lock-in concerns (-1.7%), and rural broadband latency constraints (-1.4%) are the key restraints identified in our primary research.
8How fast is the SME segment growing in the North America SASE market?
SMEs are expanding at 21.05% CAGR through 2031, outpacing large enterprises, as they acquire enterprise-grade protection without capital outlays through OPEX-friendly SASE bundles.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our analysts conducted 1,200+ structured interviews with senior decision-makers across the North America SASE value chain, accounting for 70–80% of total research effort.
Company types interviewed: SASE platform vendors (25%), managed service providers and telecom carriers (20%), enterprise end-users (30%), cloud infrastructure and semiconductor suppliers (15%), and system integrators/consultancies (10%).
Stakeholder roles: Chief Information Security Officer (CISO), VP of Network Infrastructure, IT Procurement Director, and Head of Cloud Security Architecture.
Industry associations and regulatory bodies referenced: Cloud Security Alliance (CSA), ISC², the National Institute of Standards and Technology (NIST), and the Office of the Privacy Commissioner of Canada (OPC).
Quantitative metrics captured: Number of branch sites migrated to SASE, average bandwidth per remote user, security incident frequency per 1,000 endpoints, and annual IT security spend per employee.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Information Security Officer (CISO)
30%
VP of Network Infrastructure
25%
IT Procurement Director
25%
Head of Cloud Security Architecture
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
SASE Platform Vendors
25%
Managed Service Providers & Telecom Carriers
20%
Enterprise End-Users
30%
Cloud Infrastructure & Semiconductor Suppliers
15%
System Integrators & Consultancies
10%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on validated secondary sources, including official trade statistics from the USITC DataWeb, Eurostat, and OECD data on ICT investment.
Financial benchmarking leverages standard databases: Bloomberg, Factiva, Hoovers, and PitchBook.
Technical standards and market benchmarks sourced from recognized non-profit trade associations, including the Cloud Security Alliance and ISC² workforce studies.
All secondary data is cross-validated against primary interview findings to ensure consistency and eliminate outlier bias.
Demand Modeling & Market Estimation
We employ simultaneous top-down and bottom-up methodologies, validated through multi-level data triangulation.
Top-down approach: Regional IT security and networking spend is disaggregated using segment-level penetration rates derived from primary interviews.
Bottom-up approach: Market size is calculated by aggregating vendor-level revenue estimates, verified against enterprise procurement data and average contract values.
Quantitative inputs: Average SASE contract value per enterprise site, number of addressable branch locations, cloud migration rates, and managed-service attach rates.
Segment-level CAGRs are modeled using weighted driver/restraint impact analysis, with each factor assigned a percentage impact on the forecast growth rate.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-stage validation and analyst review.
Every report is updated to the date of purchase, incorporating the latest available trade data, vendor earnings releases, and regulatory developments.
Data triangulation is performed across at least three independent sources for every market size and CAGR figure.
Outlier detection and sensitivity analysis are applied to all segment forecasts, with confidence intervals reported for key metrics.