1What is the network slicing market size in 2025?
The global network slicing market is valued at USD 6.1 billion in 2025, according to our proprietary research, and is projected to reach USD 67.5 billion by 2030.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Network Slicing Market
 by Component (Infrastructure [RAN, Core, Transport], Software [MANO, Analytics, Security]), by Service Model (Managed Services, Network-as-a-Service, Professional [Consulting, Integration, Testing]), by Application (Remote Monitoring & Surveillance, Network Function Virtualization & Cloud RAN, Mobile Cloud Gaming, Connected Vehicles [V2X]), by End-User Industry (Automotive & Transportation, Media & Entertainment, Healthcare, Manufacturing, Energy & Utilities), by North America (USA, Canada), by Europe (Germany, UK, France, Italy, Spain, Nordics), by Asia Pacific (China, Japan, South Korea, India, Australia), by Middle East & Africa (UAE, Saudi Arabia, South Africa), by South America (Brazil, Argentina) Forecast 2026-2034

Senior Research Analyst


 Related Reports

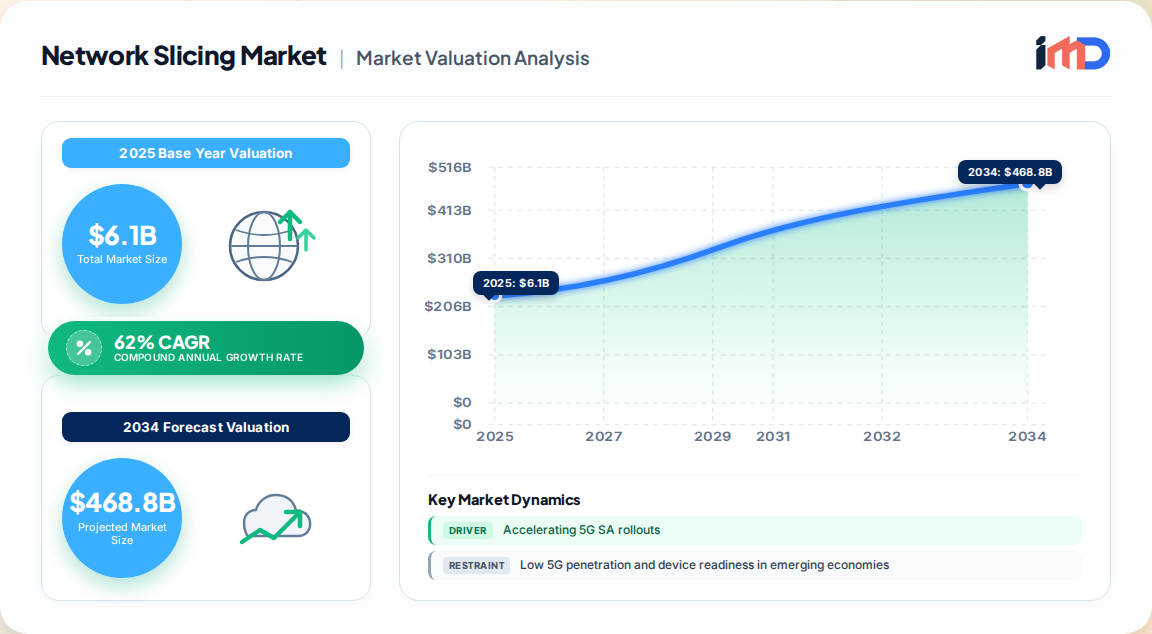
The global network slicing market is undergoing a period of explosive growth as communication service providers (CSPs) transition from best-effort connectivity to programmable, service-differentiated 5G networks. Our proprietary primary research estimates the market at USD 6.1 billion in 2025, projected to reach USD 67.5 billion by 2030, representing a remarkable CAGR of 62% over the forecast period. This acceleration is primarily fueled by the global rollout of 5G Standalone (SA) core networks, which unlock end-to-end slicing capabilities, and the urgent need for CSPs to monetize their 5G investments through premium enterprise and consumer offerings.
Asia-Pacific currently dominates the market, accounting for approximately 73% of global revenue in 2025, driven overwhelmingly by China's aggressive 5G SA deployment and early commercial slicing launches. However, growth is rapidly diversifying; while Asia-Pacific will maintain a robust 55% CAGR, all other regions are expected to grow at rates between 121% and 127%, significantly reducing Asia-Pacific's share to 73% by 2030. North America and the Middle East & Africa are the second and third-largest regional markets, with North America projected to overtake the latter by 2029. The competitive landscape is intensifying as infrastructure vendors, cloud-native software specialists, and hyperscalers race to deliver orchestration platforms that automate slice lifecycle management.
The market's exponential growth is underpinned by several structural drivers. The most significant is the proliferation of 5G SA core deployments, which provide the architectural foundation for network slicing. With over 89 public operators running live SA networks and more than 180 actively investing, the addressable base for slicing is expanding rapidly. In parallel, enterprise demand for ultra-reliable low-latency communication (URLLC) in Industry 4.0 settings—where sub-5ms latency and 99.999% reliability are mandatory—is compelling manufacturers to adopt private 5G slices. Furthermore, the emergence of Network-as-a-Service (NaaS) and network-as-code APIs is enabling CSPs to monetize slicing through developer-friendly, self-service portals, with early movers like Deutsche Telekom and Telefónica demonstrating strong commercial pipelines.
Despite the bullish outlook, the market faces notable headwinds. Low 5G penetration and device readiness in emerging economies remain a critical restraint, particularly in APAC emerging markets, MEA, and Latin America, where 5G SA coverage lags significantly behind China and North America. Additionally, multi-domain orchestration complexity and the associated OPEX burden—cross-vendor integration can drive costs 30-50% higher than legacy management—are deterring smaller operators from deploying slicing platforms. Fragmented slice-SLA security certification standards and regulatory uncertainty over spectrum-sharing for dynamic slices further temper growth, though these are expected to be addressed as standards bodies mature.
The network slicing market is segmented by component, service model, application, and end-user industry, each exhibiting distinct growth trajectories.
By Component: Software accounted for 48.2% of the market share in 2025, reflecting heavy investment in MANO, analytics, and security platforms. Infrastructure software, spanning RAN, core, and transport layers, is advancing at a 39.5% CAGR through 2030, boosted by SDN upgrades. The solutions segment (including hardware and software) dominates with a 60.3% revenue share, while services are anticipated to witness the fastest CAGR of 52.3%.
By Service Model: Managed services commanded a 58.4% share in 2025, as operators outsource slice orchestration complexity. However, Network-as-a-Service is the fastest-growing segment, posting a 41.3% CAGR to 2030, driven by demand for programmatic, on-demand connectivity.
By Application: Remote monitoring and surveillance held 36.25% of the market in 2025, but mobile cloud gaming is projected to grow at a 39.7% CAGR, fueled by demand for ultra-low-latency virtual network segments. Other key applications include network function virtualization (NFV) and cloud RAN, connected vehicles (V2X), and fixed wireless access.
By End-User Industry: Automotive & transportation led with 27.85% of the market share in 2025, as connected vehicles and V2X communication require deterministic network performance. Media & entertainment is expanding at a 41.95% CAGR, driven by remote broadcasting and cloud gaming, while healthcare, manufacturing, and energy & utilities are also adopting slices for mission-critical applications.
Asia-Pacific's dominance is undeniable, with China alone accounting for over 95% of regional revenue in 2025. The region's early 5G SA rollout, government support for industrial digitalization, and large-scale deployments by operators like China Mobile and China Unicom have created a mature slicing ecosystem. However, growth will moderate to a 55% CAGR as other regions accelerate.
North America is the second-largest market, characterized by advanced enterprise adoption and a strong focus on private 5G. The region is expected to become consumer-majority by 2030, driven by applications like cloud gaming and enhanced mobile broadband. Europe holds the third-largest share, anchored by industrial IoT mandates in Germany and the Nordics. The region is also witnessing significant operator investments, exemplified by Orange's selection of Ericsson to automate 5G network slicing across its European affiliates, a deployment scheduled to begin in 2025. The Middle East & Africa and South America are smaller but rapidly growing markets, with MEA expected to be overtaken by North America by 2029.
The network slicing market is highly competitive, with a mix of established telecom equipment vendors, cloud-native software specialists, and hyperscalers. Key players include Ericsson, Huawei, Nokia, Cisco Systems, Samsung Networks, ZTE, BT Group, NTT DOCOMO, Amdocs, and VMware. Competition is intensifying around orchestration platforms that automate slice lifecycle management, with vendors differentiating through AI-driven automation, multi-vendor interoperability, and integration with public cloud edge zones.
Hyperscaler-telco convergence is a defining trend, with AWS, Microsoft Azure, and Google Cloud launching telco-specific edge zones that pre-integrate slice orchestration. Partnerships, such as AWS Wavelength with Verizon and KDDI, demonstrate how multi-tenant network architecture can extend into the public cloud, enabling developers to request specific slice characteristics via cloud-native APIs. Operators are also increasingly partnering with vendors for managed services to reduce OPEX and accelerate time-to-market.
Several high-growth opportunities are emerging. Enterprise private 5G slicing represents a significant white space, particularly in manufacturing, logistics, and healthcare, where dedicated slices can deliver guaranteed performance. Slice brokering and wholesale platforms are also gaining traction, enabling operators to monetize excess capacity by leasing slices to third parties. In emerging markets, fixed wireless access (FWA) slicing offers a leapfrog opportunity, allowing operators to deliver broadband services without extensive fiber deployment. Additionally, the development of network-as-code APIs is opening new revenue streams from developer communities, with Ericsson's alliance with 12 tier-one operators targeting a USD 30 billion network-API market by 2030.
The network slicing value chain spans from component suppliers to end-users. At the upstream, semiconductor and hardware vendors provide the chips and equipment for 5G RAN, core, and transport networks. Supply-chain constraints, notably 56-week semiconductor lead times, have historically impacted deployment timelines, but operators continue to prioritize software investments to capture developer-led revenue streams.
Midstream, infrastructure vendors and software specialists deliver slicing platforms, orchestration, and assurance solutions. Integration services and managed services are critical to deploy and operate slices across multi-vendor environments. Downstream, CSPs commercialize slices to enterprises and consumers, often through partnerships with hyperscalers and system integrators. The value chain is characterized by increasing collaboration between telcos and cloud providers, as evidenced by Orange's partnership with Ericsson for automated slicing orchestration.
As a software-centric market, network slicing does not involve significant physical trade flows, but supply chain dynamics are still relevant. The market relies heavily on semiconductor components for 5G infrastructure, with global supply concentrated in a few regions. Trade tensions and export controls, such as the U.S. CHIPS and Science Act, are shaping the supply landscape, prompting operators to diversify their vendor base. However, the software layer is less constrained by physical trade barriers, though regulatory fragmentation across jurisdictions can affect deployment. Overall, supply chain risks are moderate but require proactive management, particularly for hardware-dependent components.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 62% from 2020-2034 |
| Segmentation |
|
By Service Model
By Application
By End-User Industry
| By Geography |
|
The global network slicing market is valued at USD 6.1 billion in 2025, according to our proprietary research, and is projected to reach USD 67.5 billion by 2030.
The market is expected to grow at a CAGR of 62% from 2025 to 2030, driven by 5G SA rollouts and enterprise demand for differentiated connectivity.
Asia-Pacific leads the market with a 73% share in 2025, primarily due to China's early and widespread 5G SA deployments, but other regions are growing faster.
Key drivers include 5G SA core deployments, industrial URLLC demand, network-as-a-service monetization models, and hyperscaler-telco convergence.
Major players include Ericsson, Huawei, Nokia, Cisco Systems, Samsung Networks, ZTE, and Amdocs, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CTO / VP of Network Strategy | 30% |
| Enterprise CIO / IT Director | 25% |
| Product Manager – 5G & Edge | 25% |
| Procurement & Sourcing Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Telecom Equipment Vendors (OEMs) | 35% |
| Cloud-Native Software Specialists | 20% |
| Communication Service Providers (CSPs) | 25% |
| Hyperscalers & Edge Providers | 10% |
| System Integrators & Managed Service Providers | 10% |