1What is the current market size of the multimode optical modules market?
The global multimode optical modules market was valued at USD 11.64 billion in 2024 and is projected to reach USD 25.15 billion by 2032, growing at a CAGR of 10.10%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Multimode Optical Modules Market
 by Form Factor (SFF and SFP; SFP+ and SFP28; QSFP, QSFP+, QSFP14, and QSFP28; CFP, CFP2, and CFP4; XFP; CXP; OSFP), by Data Rate (Less Than 10 GBPS, 10 GBPS to 40 GBPS, 41 GBPS to 100 GBPS, More Than 100 GBPS), by Distance (Less Than 1 KM, 1 to 10 KM, 11 to 100 KM, More Than 100 KM), by Wavelength (850 NM Band, 1310 NM Band, 1550 NM Band, Others), by Connector (LC Connector, SC Connector, MPO Connector, RJ-45), by Application (Telecommunication, Data Center, Enterprise, HPC), by End User (Cloud Service Providers & Hyperscalers, Telecom Operators, Enterprises, Government & Defense), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Singapore, Australia, Rest of Asia Pacific), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA), by South America (Brazil, Argentina, Rest of South America) Forecast 2026-2034


Senior Research Analyst

 Related Reports


Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
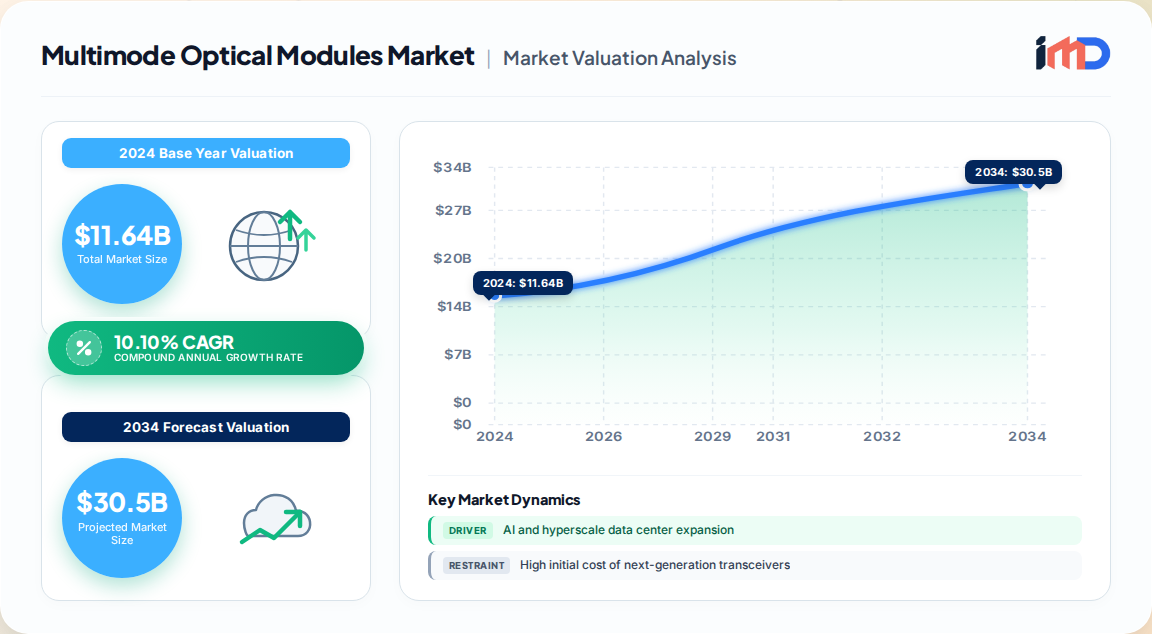
The global multimode optical modules market is experiencing a structural demand inflection, driven by the insatiable bandwidth requirements of artificial intelligence (AI) clusters, hyperscale cloud expansion, and the relentless upgrade of data center fabrics from 10G/40G to 100G, 400G, and emerging 800G architectures. Our proprietary primary research estimates the market at USD 11.64 billion in 2024, with a projected trajectory to USD 25.15 billion by 2032, representing a robust CAGR of 10.10% over the forecast period (2025–2032).
Unlike single-mode optics, multimode modules leverage vertical-cavity surface-emitting lasers (VCSELs) and parallel optics to deliver cost-efficient, low-power, short-reach connectivity—typically under 500 meters—making them the default choice for intra-rack and inter-rack data center links, enterprise campus backbones, and increasingly, high-performance computing (HPC) interconnects. The market's growth is not merely a volume story; it is a story of rapid replacement cycles and architectural shifts toward higher port densities and energy efficiency.
The expansion of the multimode optical modules market is underpinned by several secular drivers, yet it faces headwinds that could temper growth in specific segments.
The multimode optical modules value chain is highly integrated, spanning from component fabrication to system-level integration. Our primary interviews with industry stakeholders reveal a supply chain that is increasingly concentrated and strategic.
The supply chain has shown resilience but faces risks related to semiconductor shortages and geopolitical trade tensions. Companies are diversifying manufacturing footprints, with increased production in Southeast Asia and Mexico.
The market is segmented by form factor, data rate, distance, wavelength, connector, application, and end user. The following table summarizes the primary segments and their market dynamics.
| Segment | Key Sub-Segments | Market Share (2024) | Growth Outlook |
|---|---|---|---|
| By Form Factor | SFP/SFP+, QSFP/QSFP+, QSFP28/QSFP-DD, OSFP, CFP, XFP | QSFP family: ~40% | OSFP fastest CAGR (21.4% to 2035) |
| By Data Rate | ≤10G, 25G, 40G, 100G, 200G & above | 100G: volume leader; 200G+: fastest growth | 800G+ CAGR 23.1% (to 2035) |
| By Distance | <1 km, 1–10 km, 11–100 km, >100 km | <1 km dominates multimode | Steady growth in 1–10 km |
| By Wavelength | 850 nm, 1310 nm, 1550 nm, others | 850 nm band dominant | 850 nm remains primary for multimode |
| By Connector | LC, SC, MPO, RJ-45 | LC and MPO lead | MPO gains with parallel optics |
| By Application | Data center, enterprise, telecom | Data center: 55–60% | HPC fastest-growing niche |
| By End User | Cloud/Hyperscale, telecom, enterprise, government | Hyperscalers: 45–50% | Hyperscalers drive innovation |
Geographically, the market exhibits distinct maturity levels. Asia-Pacific leads in revenue share, while North America remains the innovation hub for high-speed adoption.
| Region | Market Share (2024) | Key Characteristics |
|---|---|---|
| Asia-Pacific | 38.5% | Rapid digitalization, cloud data center expansion in China, India, Japan; fastest CAGR (15.0% to 2035) |
| North America | 37.1% | Hyperscale concentration, early adoption of 400G/800G, strong AI ecosystem |
| Europe | 23% | Focus on energy efficiency, data sovereignty, steady enterprise upgrades |
| Middle East & Africa | 6% | Gradual data center investments, telecom modernization |
| South America | 5% | Emerging opportunity, cost-sensitive strategies |
The competitive landscape is moderately consolidated, with the top five players accounting for over 72% of the optical transceiver market in 2025. Competition is intensifying on the basis of speed, power efficiency, and supply chain reliability.
The market is witnessing rapid innovation, particularly in VCSEL technology and high-density form factors.
Our analysis identifies several white-space opportunities for stakeholders.
While multimode optical modules are not a raw commodity, trade flows of optical components and modules are significant. China is a major exporter of optical transceivers, while the U.S. and Europe are key importers and innovators. According to UN Comtrade data, global trade in optical transceivers (HS code 8517.70) exceeded USD 20 billion in 2023, with China accounting for over 30% of exports. Supply chain risks include export controls on advanced semiconductors and geopolitical tensions, prompting diversification of manufacturing to Southeast Asia (e.g., Vietnam, Thailand) and Mexico.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.10% from 2020-2034 |
| Segmentation |
|
By Data Rate
By Distance
By Wavelength
By Connector
By Application
By End User
| By Geography |
|
The global multimode optical modules market was valued at USD 11.64 billion in 2024 and is projected to reach USD 25.15 billion by 2032, growing at a CAGR of 10.10%.
Asia-Pacific held the largest revenue share of 38.5% in 2024, driven by rapid digitalization and cloud data center expansion in China, India, and Japan.
Key drivers include the surge in AI and hyperscale workloads, data center infrastructure upgrades from 10G/40G to 100G/400G, and the cost and power efficiency advantages of multimode solutions for short-reach connectivity.
Major players include Coherent Corp., Lumentum Holdings, Broadcom Inc., Cisco Systems, InnoLight Technology, and FS (Fiberstore).
The 800G and above segment is expected to grow at the highest CAGR of 23.1% through 2035, driven by hyperscale AI cluster deployments.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 25% |
| Procurement Director | 30% |
| Data Center Infrastructure Manager | 25% |
| Optical Network Engineer | 20% |
| Company Type | Representation (%) |
|---|---|
| Optical Module OEMs | 40% |
| VCSEL & Component Manufacturers | 25% |
| Hyperscale Data Center Operators | 20% |
| Telecom Network Operators | 10% |
| Enterprise IT & System Integrators | 5% |