1What is the size of the Middle East edible meat market?
The Middle East edible meat market is valued at USD 31.16 billion in 2026 and is projected to reach USD 34.80 billion by 2031, growing at a CAGR of 2.23%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Middle East Edible Meat Industry
 by Type (Beef, Mutton, Poultry, Other Meat), by Form (Canned, Fresh/Chilled, Frozen, Processed), by Distribution Channel (HoReCa, Retail(Supermarkets/Hypermarkets, Online/E-commerce, Specialty Stores, Other Retail)), by Saudi Arabia, by United Arab Emirates, by Oman, by Qatar, by Kuwait, by Bahrain, by Rest of Middle East Forecast 2026-2034

Research Associate

 Related Reports

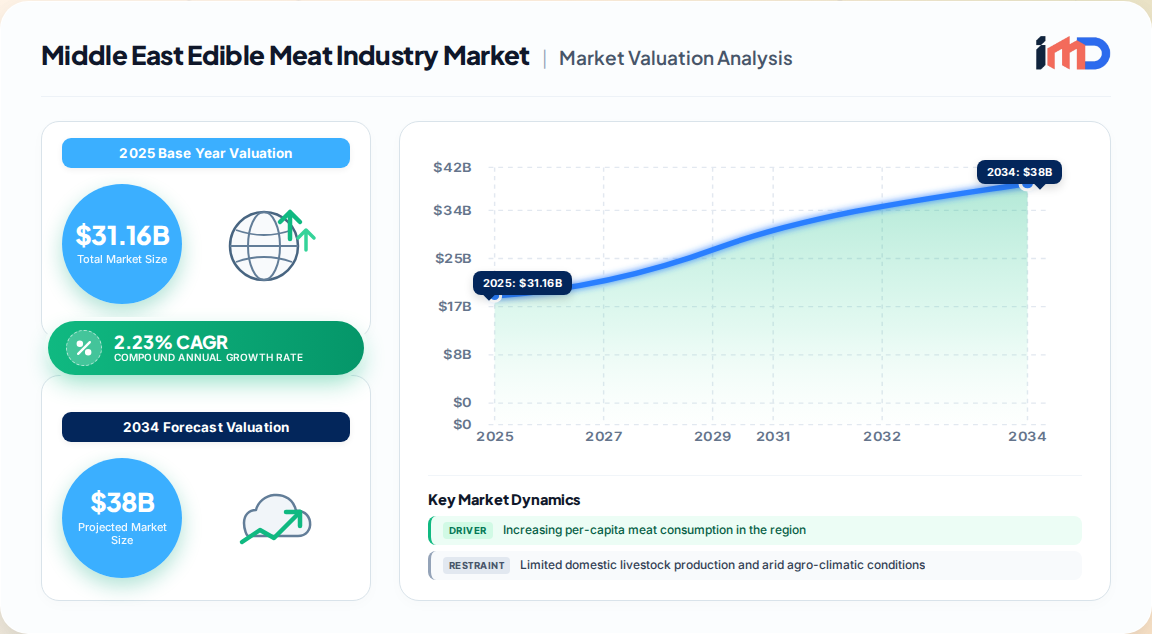
The Middle East edible meat industry represents a critical pillar of regional food security and a rapidly evolving consumer market. Our proprietary primary research, triangulated with official trade data, values the market at USD 31.16 billion in 2026, projected to reach USD 34.80 billion by 2031, expanding at a CAGR of 2.23% (2026–2031). Volume growth is underpinned by sustained population expansion—the regional population is forecast to reach 640 million by 2030, with over 70% urbanized—and rising disposable incomes across GCC households.
Poultry dominates consumption, accounting for 63.26% of market share in 2025, driven by its affordability, versatility, and cultural acceptance. Beef is the fastest-growing protein type, recording a projected 2.55% CAGR through 2031, while processed meat products are advancing at a 3.03% CAGR, reflecting shifting consumer preferences toward convenience. Fresh/chilled meat retains the largest form share at 51.27% in 2025, but frozen and processed formats are gaining ground as cold-chain infrastructure modernizes.
Geographically, Saudi Arabia commanded 21.22% of regional market share in 2025, and Oman is forecast to expand at the fastest pace, registering a 3.61% CAGR toward 2031. The competitive landscape is moderately concentrated, with vertically integrated regional producers and global food conglomerates competing on halal compliance, cold-chain logistics, and private-label strategies.
The industry's growth trajectory is shaped by a distinct set of structural drivers and persistent restraints. Our impact analysis quantifies the contribution of each factor to the forecast CAGR.
| Driver | Impact on CAGR | Geographic Relevance | Timeline |
|---|---|---|---|
| Development of local livestock production supported by import-substitution policies | +0.6% | Saudi Arabia, Qatar, Oman | Long term (≥ 4 years) |
| Government investments in food security promoting vertical integration | +0.5% | Qatar, Saudi Arabia, Oman | Long term (≥ 4 years) |
| Increasing per-capita meat consumption | +0.4% | Saudi Arabia, UAE, Qatar | Medium term (2–4 years) |
| Expansion of modern retail infrastructure and cold-chain logistics | +0.3% | UAE, Saudi Arabia | Medium term (2–4 years) |
| Advancements in value-added and processed meat products | +0.3% | UAE, Saudi Arabia | Medium term (2–4 years) |
| Implementation of precision-livestock farming tailored to arid environments | +0.2% | Saudi Arabia, UAE | Long term (≥ 4 years) |
Saudi Arabia's 2025 self-sufficiency program allocated USD 1.3 billion in concessional loans to modernize broiler houses and breeding facilities, while Qatar's National Food Security Strategy targets a 30% increase in red-meat production by 2030. These initiatives compress production cycles and reduce reliance on refrigerated imports.
However, the region possesses less than 2% of the world's renewable freshwater, severely constraining large-scale livestock farming. Over 80% of GCC red meat is imported, exposing the market to geopolitical disruptions and freight volatility. Furthermore, fragmented halal certification frameworks—with over 50 distinct certification bodies operating across the region—increase compliance costs and delay market entry for foreign suppliers. The Strait of Hormuz disruption in 2024 exposed logistical bottlenecks, prompting governments to accelerate vertical integration and long-term grain corridor agreements with Black Sea exporters.
The Middle East edible meat industry is segmented by type, form, and distribution channel, with each segment exhibiting distinct growth dynamics.
By Type:
By Form:
By Distribution Channel:
Saudi Arabia leads the regional market with 21.22% share in 2025, supported by Vision 2030 food security investments, including a USD 50 million JBS investment in a new Jeddah plant (July 2024) that quadrupled poultry production capacity. The UAE follows as a premium consumption hub, with 98% of meat distributed through refrigerated networks and the region's first approval of lab-grown meat for commercial sale in 2023. Oman is the fastest-growing market at 3.61% CAGR, driven by import-substitution policies and smart barn investments. Qatar and Kuwait maintain high per-capita consumption levels, with Qatar pushing for complete self-sufficiency in dairy and fresh chicken.
| Country | 2025 Share (%) | Key Growth Driver |
|---|---|---|
| Saudi Arabia | 21.22 | Vision 2030 self-sufficiency; vertical integration |
| UAE | 22.0 (est.) | Premium demand; cold-chain leadership; tourism |
| Oman | 9.0 (est.) | Import-substitution; smart farming |
| Qatar | 8.0 (est.) | National Food Security Strategy |
| Kuwait | 7.0 (est.) | High per-capita consumption |
| Bahrain | 5.0 (est.) | Modern retail expansion |
| Rest of Middle East | 14.0 (est.) | Emerging urban demand |
The Middle East is structurally import-dependent for red meat, with over 85% of lamb consumed in Saudi Arabia and the UAE imported from Australia, Sudan, and Ethiopia. Brazil and India are major suppliers of beef and poultry, respectively. The region's import reliance creates a complex supplier ecosystem:
Trade compliance is a critical bottleneck. The lack of harmonized halal certification across the region—with over 50 certification bodies—necessitates multi-standard auditing for suppliers. Additionally, geopolitical volatility in the Strait of Hormuz and Red Sea shipping lanes has forced alternative routing via the Cape of Good Hope, adding 10–14 days to transit times and elevating freight costs. Governments are responding with long-term grain corridor agreements and investments in domestic production, but import dependence will persist through the forecast period.
The Middle East edible meat industry is moderately concentrated, featuring vertically integrated regional champions and global conglomerates. Key players include Al Ain Farms, BRF S.A., Siniora Food Industries Company, Tanmiah Food Company, and The Savola Group, alongside Al-Watania Poultry, Herfy Food Services Co., and Kibsons International LLC. Competition centers on halal compliance, cold-chain logistics, private-label product development, and digital traceability.
Recent strategic developments underscore the industry's shift toward local production and alternative proteins:
These developments signal a market transitioning from pure import reliance toward a hybrid model of domestic production, alternative proteins, and digital retail. Companies that invest in vertical integration, cold-chain efficiency, and halal-certified premium lines are best positioned to capture growth through 2031.
The edible meat value chain in the Middle East spans feed production, livestock farming, slaughtering, processing, cold-chain logistics, and retail/foodservice distribution. Arid conditions and water scarcity constrain domestic feed and livestock production, making the region heavily dependent on imported feed grains and live animals.
Key value chain dynamics:
Procurement strategies must navigate halal certification complexity, freight volatility, and currency fluctuations. Leading players are adopting multi-sourcing strategies (Brazil, Australia, India, Sudan) and investing in long-term supply agreements to hedge against disruptions. The shift toward local production supported by import-substitution policies will gradually reduce dependence on refrigerated imports, but the region will remain a net importer of red meat through 2031.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.23% from 2020-2034 |
| Segmentation |
|
By Distribution Channel
| By Geography |
|
The Middle East edible meat market is valued at USD 31.16 billion in 2026 and is projected to reach USD 34.80 billion by 2031, growing at a CAGR of 2.23%.
Poultry leads with 63.26% market share in 2025, driven by its affordability and cultural significance in dishes like kabsa and machboos. Beef is the fastest-growing type at 2.55% CAGR.
Saudi Arabia commanded 21.22% of the regional market in 2025, supported by Vision 2030 food security investments. Oman is the fastest-growing market at 3.61% CAGR through 2031.
Key drivers include increasing per-capita meat consumption (+0.4% CAGR impact), development of local livestock production (+0.6%), government food security investments (+0.5%), and expansion of cold-chain logistics (+0.3%).
Major players include Al Ain Farms, BRF S.A., Siniora Food Industries Company, Tanmiah Food Company, and The Savola Group, alongside Al-Watania Poultry, Herfy Food Services Co., and Kibsons International LLC.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Plant Manager | 25% |
| Supply Chain Head | 25% |
| C-Level Executive | 20% |
| Company Type | Representation (%) |
|---|---|
| Livestock Farmers & Feed Suppliers | 25% |
| Meat Processors & Slaughterhouses | 30% |
| Cold-Chain Logistics Providers | 15% |
| Retailers & Foodservice Distributors | 20% |
| Regulatory & Certification Bodies | 10% |