1What is the size of the India mutual fund market?
The India mutual fund market was valued at USD 2.75 Billion in 2025 and is projected to reach USD 6.23 Billion by 2034, growing at a CAGR of 9.24% from 2026 to 2034.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Markets Driving India Mutual Fund Industry
 by Asset Class/Scheme Type (Equity-oriented Schemes, Debt Schemes, Hybrid Schemes, Money Market Funds, Solution-oriented Schemes, Passive Funds(Index Funds, ETFs, Smart-Beta Funds)), by Source of Funds (Retail Investors, Institutional Investors, High Net Worth Individuals), by Management Style (Active Funds, Passive Funds), by Distribution Channel (Online Trading Platforms, Banks, Securities Firms, Mutual Fund Distributors and RIAs, Direct Plans), by West India (Maharashtra, Gujarat), by North India (Delhi NCR, Punjab, Haryana), by South India (Karnataka, Telangana, Tamil Nadu, Kerala), by East India (West Bengal, Odisha, Bihar) Forecast 2026-2034

Research Associate


 Related Reports

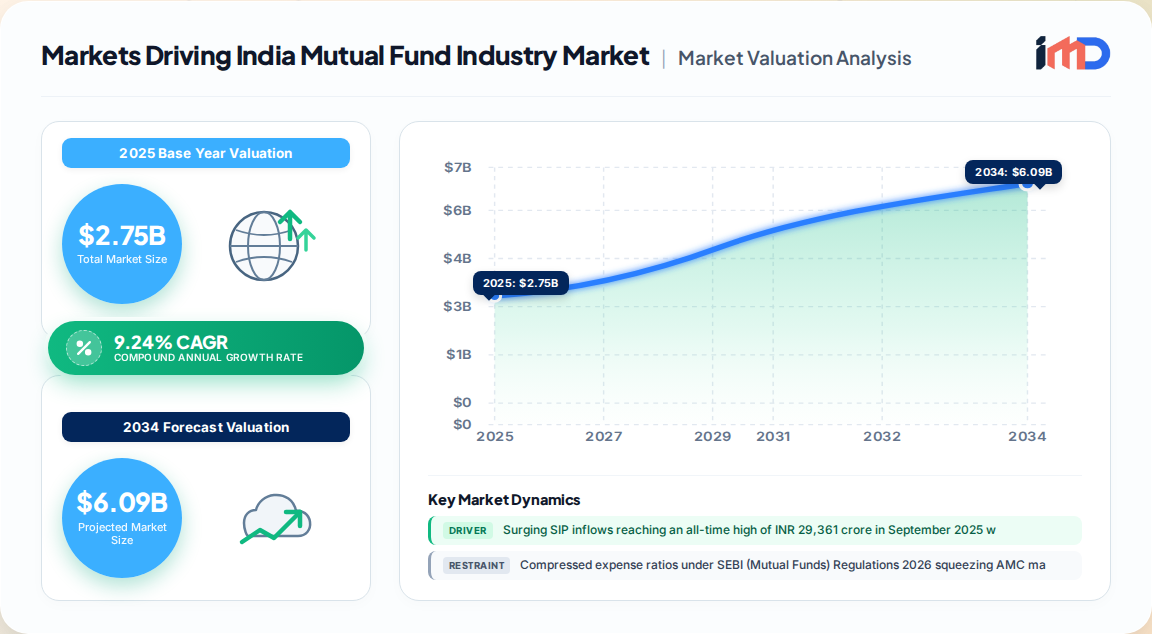
India's mutual fund industry is no longer a cyclical story of bull-market inflows; it is a structural reallocation of household savings. Our proprietary bottom-up research values the industry at USD 2.75 Billion in 2025, rising to an estimated USD 3.00 Billion in 2026 and projected to reach USD 6.23 Billion by 2034, expanding at a 9.24% CAGR over 2026–2034.
This trajectory is anchored by three hard data points: monthly SIP contributions that crossed INR 29,361 crore in September 2025, an active SIP account base of 9.25 crore, and an industry AUM-to-bank-deposit ratio that has climbed from 19.7% in March 2020 to 28.7% by March 2025. These are not sentiment indicators; they are evidence of a permanent shift in the Indian saver's balance sheet.
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 2.75 Billion |
| Forecast Market Size (2034) | USD 6.23 Billion |
| CAGR (2026–2034) | 9.24% |
| Largest Asset Class | Equity-oriented schemes (42.6% share, 2025) |
| Largest Source of Funds | Retail investors (38.5%, 2025) |
| Leading Region | West India (34.2% share, 2025) |
| Fastest Growing Region | North India (B30 SIP expansion) |
1. SIP Inflows as the Structural Backbone. Systematic Investment Plans have institutionalized retail investing. The 55-month streak of net positive equity inflows is sustained less by lump-sum conviction and more by rupee-cost-averaging discipline. Monthly SIP contributions reached an all-time high of INR 29,361 crore in September 2025 (up from INR 28,265 crore in August 2025), with SIP AUM at INR 15.52 lakh crore. This recurring flow base smooths volatility and creates a predictable revenue engine for AMCs.
2. B30 City Penetration. Beyond-the-top-30 (B30) cities now contribute 19.1% of industry assets (INR 15.35 lakh crore), reflecting genuine geographic broadening. Digital KYC, UPI autopay, and vernacular interfaces have collapsed the distribution gap that historically confined mutual funds to metros. North India is the fastest-growing region on the back of this B30 expansion.
3. Digital and Fintech Distribution. Online trading platforms captured 33.42% of distribution in 2025 and are growing at 9.22% CAGR, the fastest of any channel. Aadhaar-based KYC, DigiLocker, and UPI mandate execution have reduced SIP setup from days to minutes. AMC-led platforms such as HDFC Bank's SmartWealth complement pure-play fintechs, broadening the acquisition funnel.
4. Regulatory Rationalization. The SEBI (Mutual Funds) Regulations 2026, effective April 2026, lower base expense ratios, unbundle statutory levies, and rationalize brokerage limits. While margin-compressive for smaller AMCs, these reforms enhance transparency and investor trust—the long-run demand multiplier. AMFI's 'Chhoti SIP' and MITRA initiatives (February 2025) specifically target small-ticket and first-time investors.
| Segment | Leading Category | 2025 Share | Growth Outlook |
|---|---|---|---|
| Asset Class | Equity-oriented schemes | 42.6% | 8.14% CAGR to 2031 |
| Source of Funds | Retail investors | 38.5% | 7.36% CAGR to 2031 |
| Management Style | Active funds | 74.26% | Passive fastest at 8.61% CAGR |
| Distribution | Online trading platforms | 33.42% | 9.22% CAGR |
Equity dominance is supported by a 55-month positive inflow streak and favorable long-term capital gains treatment. However, the real structural story is passive investing: passive AUM surged sixfold from INR 1.91 lakh crore in 2019 to INR 12.2 lakh crore in 2025, and 68% of retail investors now hold at least one passive fund. Index funds, smart-beta, and thematic ETFs are the fastest-growing product frontier.
Hybrid and solution-oriented schemes provide ballast in volatile markets, while debt schemes benefit from the gradual shift of pension assets (EPFO, NPS) toward long-duration instruments.
West India commands 34.2% share (2025), anchored by Mumbai as the financial capital and headquarters of nearly all major AMCs. North India follows at 27.6%, with Delhi NCR providing a deep high-income investor base and B30 towns driving incremental SIP accounts. South India (Bengaluru, Hyderabad, Chennai) benefits from a tech-savvy investor cohort and high digital adoption. East India remains the white space—underpenetrated but improving through financial literacy campaigns and micro-SIP channels.
Industry concentration is moderate-to-high: the top five fund houses manage 56% of total industry assets, with SBI Mutual Fund holding the largest QAAUM at INR 12.77 lakh crore. Competition is shifting from pure equity performance toward distribution reach, digital experience, and passive product breadth.
Key developments shaping strategy:
Strategic white-space exists in women-centric schemes (SEBI's incentive framework), retirement-focused solutions, and passive product innovation—three areas where demand is structurally under-served relative to investor appetite.
The value chain runs from AMCs (product manufacturing) through distributors, RIAs, banks, and online platforms to the end investor. The shift toward direct plans and digital channels is compressing distributor commissions while expanding reach. Banks and securities firms remain critical for HNI and institutional flows, but online platforms dominate new retail SIP originations. AMCs that pair low-cost passive products with strong digital onboarding and vernacular education will capture disproportionate share of the next 9.25 crore SIP accounts.
As a financial services market, trade dynamics are indirect. India's insurance and financial services exports remain modest as a share of commercial service exports, but the EU-India Free Trade Agreement's services chapter commitments—covering financial services and cross-border supply—create a channel for foreign AMC expertise, fund administration, and portfolio management services. This is a watch-point for competitive intensity: global asset managers gaining privileged access could accelerate product innovation and fee competition in India's passive and thematic segments.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.24% from 2020-2034 |
| Segmentation |
|
By Source of Funds
By Management Style
By Distribution Channel
| By Geography |
|
The India mutual fund market was valued at USD 2.75 Billion in 2025 and is projected to reach USD 6.23 Billion by 2034, growing at a CAGR of 9.24% from 2026 to 2034.
Surging SIP inflows (INR 29,361 crore monthly in September 2025), rising B30 city participation (19.1% of AUM), digital and fintech onboarding, and supportive SEBI reforms are the principal market drivers.
Equity-oriented schemes lead with a 42.6% share of AUM in 2025, supported by a 55-month streak of net positive equity inflows and sustained SIP contributions.
West India holds the largest share at 34.2% in 2025, anchored by Mumbai as the financial capital and home to most major asset management companies. North India is the fastest-growing region.
Passive fund AUM surged sixfold from INR 1.91 lakh crore in 2019 to INR 12.2 lakh crore in 2025, with 68% of retail investors now holding at least one passive fund. Passive strategies are growing at 8.61% CAGR, faster than active.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Executive Officer / Chief Investment Officer | 30% |
| Head of Sales and Distribution | 35% |
| Chief Distribution Officer | 20% |
| Product and Compliance Head | 15% |
| Company Type | Representation (%) |
|---|---|
| Asset Management Companies (AMCs) | 30% |
| Mutual Fund Distributors and RIAs | 25% |
| Online Investment Platforms and Fintechs | 20% |
| Banks and Securities Firms | 15% |
| Fund Administrators and Custodians | 10% |