Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Less-than-container Load (LCL) Shipping Market | Insight Market Data
Less-than-container Load (LCL) Shipping Market by Service Type (Standard LCL, Express LCL, Temperature-Controlled LCL, Hazardous Cargo LCL, Project & Break-Bulk LCL, Door-to-Door LCL), by Destination (Domestic, International), by Nature of Business (Freight Forwarding, NVOCCs), by End User (Manufacturing & Automotive, Retail & E-Commerce, Healthcare & Pharmaceuticals, Others), by Mode (Ocean Freight, Air Freight, Intermodal Transport, Land Freight (Road/Rail)), by Shipment Size (Small (<1 CBM), Medium (1-5 CBM), Large (5-10 CBM)), by Type of Goods (General Cargo, Fragile Goods, Perishable Items, Hazardous Materials, Textiles & Apparel), by Europe (Western Europe, Eastern Europe, Southern Europe, Northern Europe), by Middle East & Africa (GCC, North Africa, Sub-Saharan Africa, Turkey) Forecast 2026-2034
The film formers in cosmetics market is valued at USD 1.1 Billion in 2023, growing at 5.7% CAGR to reach USD 1.8 Billion by 2033. Read our full analysis.
Gardening container market valued at $21.0B in 2026, growing at 4.7% CAGR to reach $29.0B by 2033. Explore product, application and regional insights.
Nov 2026|205 pages
$2900.00
Global TPX release film for FPC board market to reach $2.25B by 2032 at 11.0% CAGR from $1.09B in 2025. Strategic analysis and forecasts.
Nov 2026|205 pages
$2900.00
China paper packaging market to grow from USD 96.13B in 2026 to USD 121.31B by 2031 at 4.76% CAGR. Driven by e-commerce & plastic-reduction mandates.
Nov 2026|222 pages
$2900.00
Reefer container shipping market at USD 10.48 billion in 2026, growing at 3.81% CAGR to USD 12.64 billion by 2031. Explore drivers, segments, and regions.
Executive Overview: Europe & MEA LCL Shipping Market
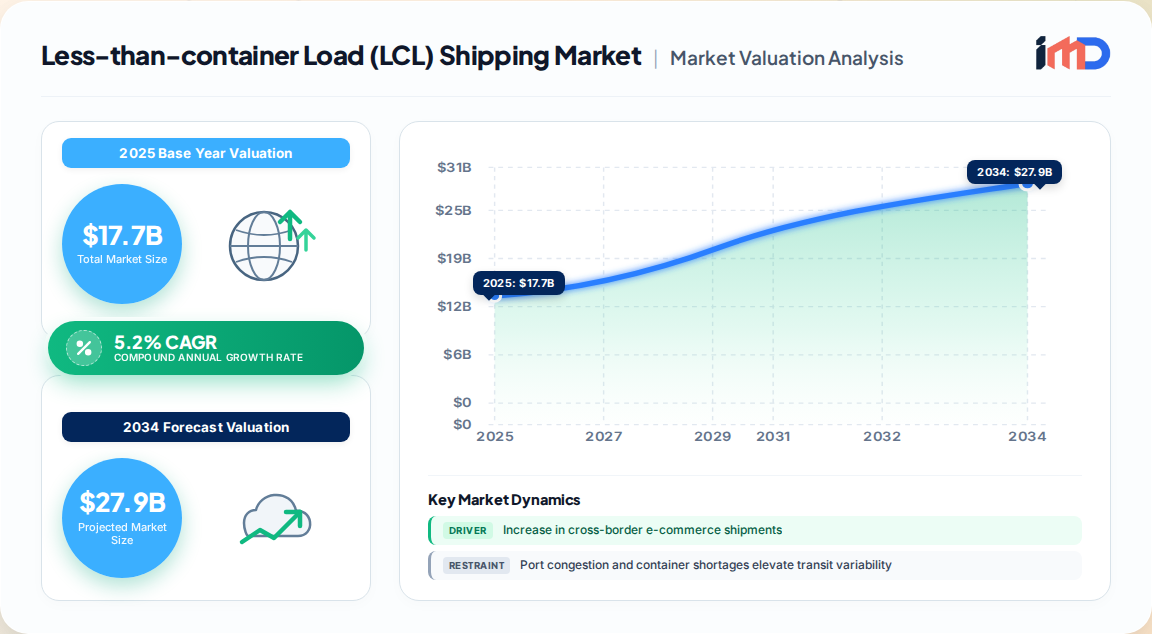
Our proprietary primary research estimates the combined Europe and Middle East & Africa (MEA) less-than-container load (LCL) shipping market at USD 17.7 billion in 2025, expanding to USD 27.9 billion by 2034 at a blended CAGR of 5.2%. Europe remains the larger and more mature theatre, while MEA is the faster-growing frontier powered by trade liberalization and digital adoption.
Less-than-container Load (LCL) Shipping Market Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
17.70 B
2025
18.62 B
2026
19.59 B
2027
20.61 B
2028
21.68 B
2029
22.81 B
2030
23.99 B
2031
Europe LCL market: USD 13.9 billion (2025) to USD 20.8 billion (2034) at 4.6% CAGR.
MEA LCL market: USD 3.8 billion (2025) to USD 7.1 billion (2034) at 7.1% CAGR.
Standard LCL services command the majority of demand in both regions, holding roughly 54% of Europe's service mix.
Top five forwarders (CEVA Logistics, DB Schenker, DHL Global Forwarding, Kuehne + Nagel, Maersk Logistics) collectively control about 32.9% of MEA and 40% of Europe LCL revenue.
Market Drivers & Restraints
The LCL value proposition is structurally reinforced by the fragmentation of global trade into smaller, more frequent orders.
Key Growth Drivers
Cross-border e-commerce surge: European parcel carriers moved 6.2 billion shipments in the 2024 holiday peak, a 9% annual jump that feeds consolidation demand.
SME export participation: Small and mid-sized firms increasingly bypass full-container commitments, using LCL to access international lanes affordably.
AfCFTA and GCC trade expansion: Intra-African trade and GCC-Asia bilateral trade (projected at USD 578 billion by 2030) create dense corridors for consolidated cargo.
Digital freight platforms: Instant booking, rate transparency and automated documentation compress quote cycles from days to minutes.
EU ETS modal shift: Carbon pricing on maritime transport narrows the cost gap between LCL consolidation and air/road alternatives.
Principal Restraints
Port congestion and container shortages raise transit variability, particularly at North European hubs.
Fragmented CFS infrastructure in Eastern Europe and parts of Africa limits consolidation density.
Carbon-compliance surcharges can erode LCL's price advantage on certain lanes.
High cost-to-value ratio for very small shipments constrains adoption among micro-enterprises.
Service Type & End-User Segmentation Analysis
Service mix and customer composition differ markedly between the two regions.
Segment
Europe Share (2025)
MEA Share (2024)
Growth Outlook
Standard LCL
~54%
Dominant
4%+ CAGR (Europe)
Express LCL
Growing
Growing
6%+ CAGR
Temperature-controlled LCL
Niche
Niche
Healthcare-led
Hazardous cargo LCL
Niche
Niche
Compliance-driven
Project & break-bulk LCL
Niche
Niche
Infrastructure-led
Door-to-door LCL
Growing
Growing
E-commerce-led
Retail & e-commerce led European LCL end-user revenue with a 31.6% share in 2025, while healthcare and pharmaceuticals post the fastest growth at 5.15% CAGR.
In MEA, standard LCL is the entry point for SMEs and regional manufacturers seeking international lane access without full-container cost structures.
Land freight (road/rail LCL) in MEA is projected to grow at 6.6% CAGR through 2034, supported by AfCFTA and corridor investment.
Regional Outlook: Europe
Western Europe is the largest sub-region, anchored by integrated port and inland corridor infrastructure; the Port of Rotterdam handled over 8.3 million containers in 2022.
Germany held 15.7% of Europe's LCL market in 2025; Spain is the fastest riser at 4.93% CAGR through 2031, and Eastern Europe (Poland, Romania) is the fastest-growing sub-region.
Infrastructure catalysts: a €90 million EIB investment in the Port of Livorno and a €1.12 billion expansion of the Port of Constanta (17 new berths) improve consolidation capacity in Southern and Eastern Europe.
Digitalization: platforms such as Cargoboard and Shypple compress quote cycles, lifting container utilization 20–30 percentage points above manual methods.
Regional Outlook: Middle East & Africa
The UAE is the largest MEA LCL market, leveraging Jebel Ali's hub status; Turkey is the fastest-growing country at 11.1% CAGR, bridging Europe and Asia.
AfCFTA implementation is the single largest structural driver, expanding intra-regional flows and customs cooperation.
FedEx LCL Priority, launched in February 2024, offers port-to-door and door-to-door customs-cleared services between Asia Pacific and Middle Eastern markets.
Green corridors: Jebel Ali and Durban are implementing sustainability initiatives that influence LCL routing and packaging.
The market is moderately concentrated, with global integrated forwarders and regional specialists contesting share.
Company
Notable Position / Development
Kuehne + Nagel
Market leader: >15% Europe share; >10.8% MEA share in 2024
CEVA Logistics
Launched low-carbon LCL ocean service (France to Ivory Coast, May 2025) with 84% CO2 reduction
DHL Global Forwarding
Top-five player in both regions
DB Schenker
Top-five player in both regions
DSV A/S
Top-five player in Europe
Maersk Logistics
Top-five player in MEA
Hellmann Worldwide Logistics
Top-five player in Europe
Dachser
Opened CFS near Rotterdam (October 2024) for European export consolidation
DP World SeaRates
Partnered with CP World (June 2024); bookings up 39%
Value Chain & Supply Chain Risk Assessment
The LCL value chain spans shippers, consolidators (CFS operators), NVOCCs and freight forwarders, ocean/land carriers, and last-mile distributors.
Consolidation economics depend on achieving high container fill rates; algorithmic matching and AI-driven capacity pooling are now standard among leading forwarders.
Red Sea rerouting has diversified entry ports and increased demand for inventory-buffering consolidation services.
Key risk: short-term port congestion at Hamburg, Antwerp and Rotterdam elevates transit variability by an estimated 1.1% drag on CAGR.
Mitigant: green shipping corridors linking Asia to Northern Europe increase sailing frequency and reduce dwell times at consolidation points.
Strategic White-Space & Investment Opportunities
Eastern European CFS build-out: fragmented consolidation infrastructure in Poland, Romania and the Balkans represents a high-return investment gap.
Temperature-controlled LCL for healthcare and perishables is under-penetrated relative to the 5.15% CAGR demand signal.
Digital-first SME platforms in MEA can capture first-time LCL shippers as e-commerce penetration rises in Nigeria, South Africa and the UAE.
Low-carbon LCL services (marine biofuel, rail-sea hybrids) offer differentiation as EU ETS costs escalate through 2026.
Turkey as a multimodal gateway warrants capacity pre-positioning given its 11.1% projected CAGR.
Methodology
This report is grounded in a 70/30 primary-to-secondary research split, multi-level data triangulation, and a guaranteed 85–90% estimated accuracy level. Full details are provided in the methodology field.
1What is the size of the Europe and MEA LCL shipping market?
Our proprietary research estimates the combined Europe and MEA LCL shipping market at USD 17.7 billion in 2025, forecast to reach USD 27.9 billion by 2034 at a blended CAGR of 5.2%. Europe accounts for USD 13.9 billion and MEA for USD 3.8 billion of the 2025 total.
2Which region is growing fastest in LCL shipping?
The Middle East & Africa is the fastest-growing region, expanding at a 7.1% CAGR from 2025 to 2034, versus 4.6% for Europe. Within MEA, Turkey is the standout country at an 11.1% projected CAGR, driven by its Europe-Asia bridge position and manufacturing exports.
3Who are the leading companies in the LCL shipping market?
Kuehne + Nagel leads with over 15% of the Europe market and over 10.8% of MEA in 2024. The top five forwarders—CEVA Logistics, DB Schenker, DHL Global Forwarding, Kuehne + Nagel and Maersk Logistics—hold 32.9% of MEA and roughly 40% of Europe LCL revenue.
4What is driving demand for LCL services in Europe?
Cross-border e-commerce is the primary driver, with European parcel carriers moving 6.2 billion shipments during the 2024 holiday peak, a 9% increase. EU ETS carbon pricing, which adds an estimated 7–8 EUR per 100 kg to base freight rates, is also accelerating modal shift from air and road to consolidated ocean LCL.
5How is digitalization changing the LCL market?
Digital freight platforms such as Cargoboard, Shypple and DP World SeaRates have compressed traditional quote cycles from several days to minutes. Algorithmic route design and machine-learning capacity pooling lift container utilization 20–30 percentage points above manual methods, widening LCL access for SMEs.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 70–80% of total research effort through primary interviews, engaging decision-makers across the LCL value chain: freight forwarders and NVOCC executives, CFS/consolidation terminal operators, e-commerce logistics managers, and ocean/land carrier network planners.
Stakeholder interviews targeted titles including Head of LCL Product, Ocean Freight Director, Supply Chain Manager, and Customs & Compliance Lead.
Structured questionnaires and in-depth interviews captured lane-level pricing, consolidation fill rates, transit-time variability, and digital adoption metrics.
Primary fieldwork was supplemented by consultations with recognized industry bodies including the International Federation of Freight Forwarders Associations (FIATA), the World Shipping Council (WSC), UNCTAD, and the European Commission's Directorate-General for Trade.
Every report is refreshed to the date of purchase, incorporating the latest lane developments and company announcements.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of LCL Product
30%
Ocean Freight Director
27%
Supply Chain Manager
25%
Customs & Compliance Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Freight Forwarders & NVOCCs
40%
CFS / Consolidation Terminal Operators
20%
Ocean & Land Carriers
18%
E-commerce & Retail Shippers
14%
Customs Brokers & Digital Platforms
8%
Secondary Research & Industry Benchmarking
The remaining 20–30% of research draws on official multilateral and governmental datasets, including UN Comtrade, World Bank LPI, WTO, OECD, Eurostat, and US ITC trade statistics.
Financial and corporate disclosures were validated through Bloomberg, Factiva, Hoovers, and PitchBook, alongside official filings and sustainability reports from carriers and forwarders.
Port throughput and infrastructure benchmarks were sourced from official port authority disclosures, including Port of Rotterdam and Port of Constanta authority publications.
No commercial market research publisher data is used; all estimates are first-party.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across trade flows, carrier capacity, and forwarder revenue.
Bottom-up market sizing relies on specific quantitative metrics: consolidated LCL tonnage and TEU-equivalent volumes by lane, average revenue per cubic meter (CBM), CFS throughput capacity, and forwarder gross yield per shipment.
Segment-level models were built for service type (standard, express, temperature-controlled, hazardous, project/break-bulk, door-to-door), end user (retail/e-commerce, healthcare, manufacturing/automotive), and business nature (freight forwarding vs. NVOCC).
Regional models disaggregate Europe into Western, Eastern, Southern and Northern Europe, and MEA into GCC, North Africa, Sub-Saharan Africa and Turkey.
Growth rates are reconciled against official trade volume growth (UN Comtrade, Eurostat) and carrier capacity deployment data.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-source triangulation and analyst review.
All data points pass a three-tier validation: source credibility screening, cross-source variance analysis, and expert panel sanity checks.
Divergences exceeding a 10% threshold trigger re-interview and model recalibration.
Final figures are audited against official trade and port statistics before publication, and reports are updated to the purchase date to reflect the latest market conditions.