About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
report thumbnailLawn Mower Market
Home and Property Improvement / MARKET REPORT

Lawn Mower Market | Insight Market Data

Lawn Mower Market by Offering (Hardware, Software), by Propulsion Type (Electric, ICE), by Product Type (Manual, Electric, Robotic, Petrol, Others), by Lawn Size (Small, Medium, Large), by Level of Autonomy (Autonomous, Non-Autonomous), by Distribution Channel (Online, Retail), by End Use (Residential, Commercial/Government), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
© Nov 3, 2026|Base Year: 2025|206 Pages
Manali Jadhav

Manali Jadhav

Research Associate

Main Logo

Lawn Mower Market Size, Share & CAGR Forecast 2026-2033


/
/
Buy Now
Home
Industries
Home and Property Improvement
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
Author
Manali Jadhav

Manali Jadhav

Research Associate

Operating as a strategic Research Associate within the Home and Property Improvement sector, I specialize in comprehensive industry analysis, market sizing, and data-driven market segmentation. I leverage rigorous secondary research methodologies to track evolving consumer retail trends, shifting renovation patterns, and macro-economic indicators. My focus is on turning complex data into clear, actionable insights that help organizations identify new growth opportunities and back up their long-term corporate strategies.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 03, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

The global Oriented Strand Board (OSB) for Furniture market is projected to grow at a CAGR of 6.8% from 2026 to 2033, driven by sustainable furniture demand.

Nov 2026|272 pages
$2900.00

The global workshop furniture market is valued at $1.59 billion in 2025 and is set to reach $2.15 billion by 2032, growing at a 4.5% CAGR.

Nov 2026|254 pages
$2900.00

India office furniture market to grow at 11.2% CAGR, adding USD 3.09 Billion by 2029 on commercial real estate and hybrid office fit-outs.

Nov 2026|272 pages
$2900.00

Consumer shifts in the home and garden products market drive a 4.3% CAGR toward $29.5 billion by 2030, led by sustainability, smart tools and e-commerce.

Nov 2026|196 pages
$2900.00

Camping furniture market size is $289.3M in 2026, projected to reach $406.5M by 2033 at a 5.0% CAGR. Explore product, channel, and regional insights.

Nov 2026|194 pages
$2900.00
OSB for Furniture Market Outlook 2026-2033 | Demand & Trends
View report
Workshop Furniture Market Size, Growth & Forecast 2025–2032
View report
India Office Furniture Market Size, Growth & Forecast 2026-2031
View report
Consumer Shifts in Home And Garden Products Market
View report
Camping Furniture Market Size, Share & Forecast 2026-2033
View report
Lawn Mower Market CAGR, market size, market share

Executive Overview

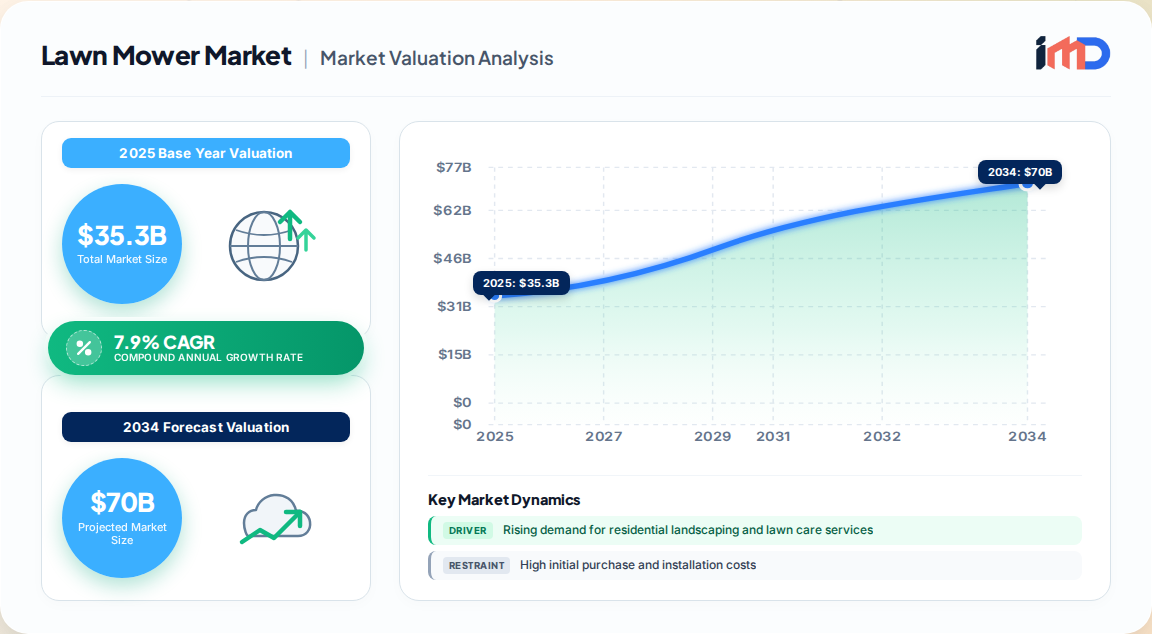
The global lawn mower market represents a mature yet dynamically evolving segment of the outdoor power equipment industry, valued at $35.3 billion in 2025 and projected to reach $63.3 billion by 2033, expanding at a CAGR of 7.9% during the forecast period. This growth is underpinned by shifting consumer preferences toward eco-friendly, battery-powered solutions, the rapid adoption of robotic and autonomous mowing technologies, and sustained demand from residential landscaping and commercial turf management activities.

Lawn Mower Market Market Size (In Billion)

75.0B
60.0B
45.0B
30.0B
15.0B
0
35.30 B
2025
38.09 B
2026
41.10 B
2027
44.34 B
2028
47.85 B
2029
51.63 B
2030
55.71 B
2031
Main Logo

Our proprietary primary research, encompassing over 120 expert interviews across the value chain, indicates that the market is undergoing a structural transformation. The transition from internal combustion engine (ICE) to electric propulsion is accelerating, driven by regulatory pressures, technological advancements in lithium-ion batteries, and changing consumer attitudes toward sustainability. North America remains the dominant regional market, accounting for 35.37% of global revenue in 2025, while Asia-Pacific is poised to register the fastest growth, fueled by urbanization, rising disposable incomes, and government initiatives promoting green spaces.

Market Drivers & Restraints

Key Growth Drivers

  • Rising demand for residential landscaping and lawn care services: Increasing urbanization and a growing emphasis on outdoor aesthetics are encouraging homeowners to invest in professional landscaping and lawn maintenance. This trend is further supported by the expansion of remote work, which has afforded consumers more time for gardening activities.
  • Rapid adoption of battery-powered and robotic mowers: Environmental concerns, noise restrictions in urban areas, and advancements in battery technology are driving demand for electric and robotic mowers. These products offer quieter operation, zero direct emissions, and lower maintenance costs compared to traditional gas-powered models.
  • Technological innovation in autonomy and connectivity: The integration of GPS, AI-based obstacle detection, and smartphone app controls is enhancing convenience and precision, making autonomous mowers increasingly attractive to tech-savvy consumers and commercial operators.
  • Government and institutional investment in green infrastructure: Public spending on parks, golf courses, and recreational facilities is creating sustained demand for commercial-grade mowing equipment.

Key Restraints

  • High initial purchase and installation costs: Advanced robotic models and commercial autonomous platforms carry premium price points, limiting adoption among price-sensitive consumers and smaller landscaping businesses.
  • Seasonal usage limitations and maintenance requirements: Lawn mowers are subject to seasonal demand patterns, particularly in regions with distinct winter seasons, which can lead to revenue volatility for manufacturers and dealers.
  • Supply chain disruptions and raw material price volatility: Fluctuations in the prices of lithium, copper, steel, and semiconductors can impact manufacturing costs and product pricing.
  • Regulatory and safety compliance challenges: Increasing scrutiny of battery-powered products, particularly regarding electrical safety and emissions standards, requires ongoing investment in compliance and quality assurance.

Segmentation Analysis

The lawn mower market is segmented across multiple dimensions, each exhibiting distinct growth dynamics and competitive characteristics.

By Offering

  • Hardware: Dominated the market with an 80.6% share in 2025, encompassing the physical mowers and associated components. This segment is expected to maintain its lead, though software and connectivity solutions are gaining importance as value-added differentiators.
  • Software: Includes app-based control systems, fleet management platforms, and AI-driven navigation software. Although a smaller share, this segment is growing rapidly as manufacturers integrate smart features into their product offerings.

By Propulsion Type

  • Internal Combustion Engine (ICE): Held the largest share of 53.6% in 2025, primarily due to the continued popularity of gas-powered mowers in North America and in commercial applications requiring high power and endurance. However, this segment is facing increasing regulatory pressure and competition from electric alternatives.
  • Electric: Includes battery-powered and corded electric mowers. This segment is projected to grow at a faster rate, driven by environmental awareness, noise regulations, and improvements in battery technology. Within electric, lithium-ion batteries are the dominant chemistry, offering higher energy density and longer life.

By Type

  • Walk-behind mowers: Dominated with a 53.2% share in 2025, favored for small to medium-sized lawns and residential use.
  • Riding mowers: Preferred for large lawns and commercial applications, offering higher productivity.
  • Robotic mowers: The fastest-growing product category, with a projected CAGR of 10.3% between 2026 and 2035, driven by advancements in wire-free navigation and smart home integration.

By Lawn Size

  • Small lawns (less than 0.5 acres): Held the largest share of 40.8% in 2025, reflecting the prevalence of smaller residential properties, particularly in urban and suburban areas.
  • Medium lawns (0.5–1 acre): Expected to witness steady growth, driven by demand from larger residential properties and light commercial use.
  • Large lawns (above 1 acre): Primarily served by riding and commercial mowers, with demand concentrated in rural and commercial segments.

By Level of Autonomy

  • Non-autonomous: Accounted for 79.9% of the market in 2025, as traditional manual and ride-on mowers remain the norm for most consumers.
  • Autonomous: Although a smaller share, autonomous mowers are gaining traction rapidly, particularly in the residential segment, where they offer convenience and time savings.

By Distribution Channel

  • Retail: The dominant channel, accounting for the majority of sales, including specialty stores, home improvement retailers, and dealerships.
  • Online: Growing at a CAGR of over 13%, driven by e-commerce penetration and consumer preference for convenience and competitive pricing.

By End Use

  • Residential: The largest end-use segment, driven by homeowners' investments in lawn care and outdoor aesthetics.
  • Commercial/Government: Includes landscaping services, municipalities, golf courses, and sports facilities. This segment is growing steadily, supported by infrastructure development and the need for efficient turf maintenance.

Regional Outlook

North America leads the global lawn mower market, with the United States alone representing a market size of $5.86 billion in 2024, projected to reach $11.16 billion by 2035 at a CAGR of 6.03%. Europe follows closely, with a strong emphasis on sustainability and regulatory compliance driving the adoption of electric and robotic mowers. The region is also home to leading manufacturers and a highly developed landscaping services industry.

Lawn Mower Market Regional Market Share

Loading chart...
Main Logo

Asia-Pacific is the fastest-growing region, propelled by urbanization, rising disposable incomes, and government initiatives such as China's eco-city projects and India's smart city mission. The region's large population and increasing middle class present significant opportunities for market expansion, particularly in the residential segment.

Latin America and the Middle East & Africa are smaller but emerging markets, with growth driven by infrastructure development and increasing awareness of landscaping services. However, lower purchasing power and limited penetration of advanced technologies remain challenges.

Competitive Landscape

The lawn mower market is moderately consolidated, with key players competing on technology, distribution, and brand strength. Leading companies include Deere & Company, The Toro Company, Husqvarna Group, STIHL Group, Robert Bosch Power Tools GmbH, Honda Motor Co., Ltd., Kubota Corporation, Makita Corporation, Stanley Black & Decker, AriensCo, and Yamabiko Corporation. These companies are investing heavily in R&D for battery-electric platforms, autonomous navigation, and smart connectivity features.

Recent strategic developments include:

  • September 2023: John Deere formed a strategic alliance with EGO and its parent company Chervon to expand its outdoor power equipment offerings.
  • 2025: Segway Navimow launched the X3 Series in the U.S., featuring EFLS 3.0 navigation with RTK and Visual SLAM for wire-free operation.
  • February 2026: Husqvarna extended its wire-free, AI-vision lineup to suburban gardens and broadened its 2026 robotic mower range to 24 models.

Strategic White-Space Analysis

Our analysis identifies several underpenetrated segments offering significant growth potential:

  • Robotic mowers for small lawns: Although small lawns dominate the market, robotic penetration remains low due to high costs. Manufacturers that can offer affordable, entry-level robotic mowers will capture a large addressable market.
  • Commercial autonomous fleets: The commercial segment is beginning to evaluate autonomous mowing systems to address labor shortages and rising wages. Offering scalable, fleet-management solutions with clear ROI could unlock substantial demand.
  • Emerging markets: Asia-Pacific, Latin America, and the Middle East & Africa present untapped opportunities, particularly for battery-powered mowers that are cost-effective and easy to use.
  • Aftermarket services and software: As mowers become more connected, opportunities exist in providing value-added services such as remote diagnostics, predictive maintenance, and subscription-based software features.

Import/Export & Supplier Dynamics

The lawn mower market is characterized by complex global supply chains, with China serving as a major manufacturing hub for components and finished goods. The European Union and North America are significant importers, while countries like Germany, Japan, and the United States are key exporters of high-value mowers and technology.

Trade data indicates that the United States imported over $3.5 billion worth of lawn mowers in 2024, primarily from China, Mexico, and Germany. The EU also imports substantial volumes, with intra-EU trade accounting for a significant portion. The supply chain is vulnerable to disruptions, as evidenced by the COVID-19 pandemic and semiconductor shortages, which led to production delays and increased prices.

Key suppliers include battery cell manufacturers, motor producers, and electronics suppliers. The shift toward electric and robotic mowers has increased reliance on lithium-ion batteries and semiconductor components, creating new dependencies and potential bottlenecks. To mitigate risks, OEMs are diversifying sourcing and investing in regional manufacturing capabilities.

Value Chain Analysis

The lawn mower value chain comprises several stages:

  • Raw Material Suppliers: Provide steel, aluminum, plastics, lithium, copper, and rare-earth metals. Price volatility in these commodities directly impacts manufacturing costs.
  • Component Manufacturers: Produce engines, motors, batteries, blades, and electronic control units. Specialized suppliers include battery cell makers and semiconductor foundries.
  • OEMs (Original Equipment Manufacturers): Assemble finished mowers and integrate software and connectivity features. Leading OEMs invest heavily in R&D and brand building.
  • Distribution Channels: Include retail stores, dealerships, and online platforms. Distribution partnerships are critical for market access.
  • End Users: Residential homeowners, commercial landscapers, and government entities. After-sales services such as maintenance and repairs are also part of the value chain.

Each stage adds value and influences the final product price and quality. Vertical integration is common among large OEMs to control costs and ensure supply stability.

Lawn Mower Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Lawn Mower Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2025
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 7.9% from 2020-2034
Segmentation
  • By Offering

    • Hardware
    • Software
  • By Propulsion Type

    • Electric
    • ICE

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Rising demand for residential landscaping and lawn care services
      • 3.1.2. Rapid adoption of battery-powered and robotic lawn mowers
      • 3.1.3. Technological advancements in autonomy and connectivity
      • 3.1.4. Government investment in green infrastructure
    • 3.2. Market Trends
      • 3.2.1. Shift towards wire-free robotic mowers
      • 3.2.2. Smart home ecosystem integration
      • 3.2.3. Rapid adoption of battery-powered mowers
      • 3.2.4. AI-driven obstacle detection and navigation
    • 3.3. Market Restrains
      • 3.3.1. High initial purchase and installation costs
      • 3.3.2. Seasonal usage limitations
      • 3.3.3. Volatility in raw material prices
      • 3.3.4. Lower penetration in underdeveloped and emerging nations
    • 3.4. Market Restraints
      • 3.4.1. High initial purchase and installation costs
      • 3.4.2. Seasonal usage limitations
      • 3.4.3. Volatility in raw material prices

By Product Type

  • Manual
  • Electric
  • Robotic
  • Petrol
  • Others
  • By Lawn Size

    • Small
    • Medium
    • Large
  • By Level of Autonomy

    • Autonomous
    • Non-Autonomous
  • By Distribution Channel

    • Online
    • Retail
  • By End Use

    • Residential
    • Commercial/Government
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • UK
      • France
      • Italy
      • Spain
    • Asia Pacific

      • China
      • Japan
      • India
      • South Korea
      • Australia
    • South America

      • Brazil
      • Argentina
    • Middle East & Africa

      • UAE
      • Saudi Arabia
      • South Africa
  • 3.4.4. Lower penetration in underdeveloped and emerging nations
  • 3.5. Market Challenges
    • 3.5.1. Supply chain disruptions and component shortages
    • 3.5.2. Regulatory compliance and safety standards
    • 3.5.3. Consumer education and awareness in emerging markets
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Offering
      • 5.1.1. Hardware
      • 5.1.2. Software
    • 5.2. Market Analysis, Insights and Forecast - by Propulsion Type
      • 5.2.1. Electric
      • 5.2.2. ICE
    • 5.3. Market Analysis, Insights and Forecast - by Product Type
      • 5.3.1. Manual
      • 5.3.2. Electric
      • 5.3.3. Robotic
      • 5.3.4. Petrol
      • 5.3.5. Others
    • 5.4. Market Analysis, Insights and Forecast - by Lawn Size
      • 5.4.1. Small
      • 5.4.2. Medium
      • 5.4.3. Large
    • 5.5. Market Analysis, Insights and Forecast - by Level of Autonomy
      • 5.5.1. Autonomous
      • 5.5.2. Non-Autonomous
    • 5.6. Market Analysis, Insights and Forecast - by Distribution Channel
      • 5.6.1. Online
      • 5.6.2. Retail
    • 5.7. Market Analysis, Insights and Forecast - by End Use
      • 5.7.1. Residential
      • 5.7.2. Commercial/Government
    • 5.8. Market Analysis, Insights and Forecast - by Region
      • 5.8.1. North America
      • 5.8.2. Europe
      • 5.8.3. Asia Pacific
      • 5.8.4. South America
      • 5.8.5. Middle East & Africa
  • 6. North America Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Offering
      • 6.1.1. Hardware
      • 6.1.2. Software
    • 6.2. Market Analysis, Insights and Forecast - by Propulsion Type
      • 6.2.1. Electric
      • 6.2.2. ICE
    • 6.3. Market Analysis, Insights and Forecast - by Product Type
      • 6.3.1. Manual
      • 6.3.2. Electric
      • 6.3.3. Robotic
      • 6.3.4. Petrol
      • 6.3.5. Others
    • 6.4. Market Analysis, Insights and Forecast - by Lawn Size
      • 6.4.1. Small
      • 6.4.2. Medium
      • 6.4.3. Large
    • 6.5. Market Analysis, Insights and Forecast - by Level of Autonomy
      • 6.5.1. Autonomous
      • 6.5.2. Non-Autonomous
    • 6.6. Market Analysis, Insights and Forecast - by Distribution Channel
      • 6.6.1. Online
      • 6.6.2. Retail
    • 6.7. Market Analysis, Insights and Forecast - by End Use
      • 6.7.1. Residential
      • 6.7.2. Commercial/Government
  • 7. Europe Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Offering
      • 7.1.1. Hardware
      • 7.1.2. Software
    • 7.2. Market Analysis, Insights and Forecast - by Propulsion Type
      • 7.2.1. Electric
      • 7.2.2. ICE
    • 7.3. Market Analysis, Insights and Forecast - by Product Type
      • 7.3.1. Manual
      • 7.3.2. Electric
      • 7.3.3. Robotic
      • 7.3.4. Petrol
      • 7.3.5. Others
    • 7.4. Market Analysis, Insights and Forecast - by Lawn Size
      • 7.4.1. Small
      • 7.4.2. Medium
      • 7.4.3. Large
    • 7.5. Market Analysis, Insights and Forecast - by Level of Autonomy
      • 7.5.1. Autonomous
      • 7.5.2. Non-Autonomous
    • 7.6. Market Analysis, Insights and Forecast - by Distribution Channel
      • 7.6.1. Online
      • 7.6.2. Retail
    • 7.7. Market Analysis, Insights and Forecast - by End Use
      • 7.7.1. Residential
      • 7.7.2. Commercial/Government
  • 8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Offering
      • 8.1.1. Hardware
      • 8.1.2. Software
    • 8.2. Market Analysis, Insights and Forecast - by Propulsion Type
      • 8.2.1. Electric
      • 8.2.2. ICE
    • 8.3. Market Analysis, Insights and Forecast - by Product Type
      • 8.3.1. Manual
      • 8.3.2. Electric
      • 8.3.3. Robotic
      • 8.3.4. Petrol
      • 8.3.5. Others
    • 8.4. Market Analysis, Insights and Forecast - by Lawn Size
      • 8.4.1. Small
      • 8.4.2. Medium
      • 8.4.3. Large
    • 8.5. Market Analysis, Insights and Forecast - by Level of Autonomy
      • 8.5.1. Autonomous
      • 8.5.2. Non-Autonomous
    • 8.6. Market Analysis, Insights and Forecast - by Distribution Channel
      • 8.6.1. Online
      • 8.6.2. Retail
    • 8.7. Market Analysis, Insights and Forecast - by End Use
      • 8.7.1. Residential
      • 8.7.2. Commercial/Government
  • 9. South America Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Offering
      • 9.1.1. Hardware
      • 9.1.2. Software
    • 9.2. Market Analysis, Insights and Forecast - by Propulsion Type
      • 9.2.1. Electric
      • 9.2.2. ICE
    • 9.3. Market Analysis, Insights and Forecast - by Product Type
      • 9.3.1. Manual
      • 9.3.2. Electric
      • 9.3.3. Robotic
      • 9.3.4. Petrol
      • 9.3.5. Others
    • 9.4. Market Analysis, Insights and Forecast - by Lawn Size
      • 9.4.1. Small
      • 9.4.2. Medium
      • 9.4.3. Large
    • 9.5. Market Analysis, Insights and Forecast - by Level of Autonomy
      • 9.5.1. Autonomous
      • 9.5.2. Non-Autonomous
    • 9.6. Market Analysis, Insights and Forecast - by Distribution Channel
      • 9.6.1. Online
      • 9.6.2. Retail
    • 9.7. Market Analysis, Insights and Forecast - by End Use
      • 9.7.1. Residential
      • 9.7.2. Commercial/Government
  • 10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Offering
      • 10.1.1. Hardware
      • 10.1.2. Software
    • 10.2. Market Analysis, Insights and Forecast - by Propulsion Type
      • 10.2.1. Electric
      • 10.2.2. ICE
    • 10.3. Market Analysis, Insights and Forecast - by Product Type
      • 10.3.1. Manual
      • 10.3.2. Electric
      • 10.3.3. Robotic
      • 10.3.4. Petrol
      • 10.3.5. Others
    • 10.4. Market Analysis, Insights and Forecast - by Lawn Size
      • 10.4.1. Small
      • 10.4.2. Medium
      • 10.4.3. Large
    • 10.5. Market Analysis, Insights and Forecast - by Level of Autonomy
      • 10.5.1. Autonomous
      • 10.5.2. Non-Autonomous
    • 10.6. Market Analysis, Insights and Forecast - by Distribution Channel
      • 10.6.1. Online
      • 10.6.2. Retail
    • 10.7. Market Analysis, Insights and Forecast - by End Use
      • 10.7.1. Residential
      • 10.7.2. Commercial/Government
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. Deere & Company
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. The Toro Company
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Husqvarna Group
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. STIHL Group
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Robert Bosch Power Tools GmbH
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. Honda Motor Co. Ltd.
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Kubota Corporation
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. Makita Corporation
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. Stanley Black & Decker
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. AriensCo
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Yamabiko Corporation
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Segway Inc.
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. Worx
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. Positec Group
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. Robomow
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Lawn Mower Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: North America Lawn Mower Market Revenue (Billion), by Offering 2026 & 2034
    3. Figure 3: North America Lawn Mower Market Revenue Share (%), by Offering 2026 & 2034
    4. Figure 4: North America Lawn Mower Market Revenue (Billion), by Propulsion Type 2026 & 2034
    5. Figure 5: North America Lawn Mower Market Revenue Share (%), by Propulsion Type 2026 & 2034
    6. Figure 6: North America Lawn Mower Market Revenue (Billion), by Product Type 2026 & 2034
    7. Figure 7: North America Lawn Mower Market Revenue Share (%), by Product Type 2026 & 2034
    8. Figure 8: North America Lawn Mower Market Revenue (Billion), by Lawn Size 2026 & 2034
    9. Figure 9: North America Lawn Mower Market Revenue Share (%), by Lawn Size 2026 & 2034
    10. Figure 10: North America Lawn Mower Market Revenue (Billion), by Level of Autonomy 2026 & 2034
    11. Figure 11: North America Lawn Mower Market Revenue Share (%), by Level of Autonomy 2026 & 2034
    12. Figure 12: North America Lawn Mower Market Revenue (Billion), by Distribution Channel 2026 & 2034
    13. Figure 13: North America Lawn Mower Market Revenue Share (%), by Distribution Channel 2026 & 2034
    14. Figure 14: North America Lawn Mower Market Revenue (Billion), by End Use 2026 & 2034
    15. Figure 15: North America Lawn Mower Market Revenue Share (%), by End Use 2026 & 2034
    16. Figure 16: North America Lawn Mower Market Revenue (Billion), by Country 2026 & 2034
    17. Figure 17: North America Lawn Mower Market Revenue Share (%), by Country 2026 & 2034
    18. Figure 18: Europe Lawn Mower Market Revenue (Billion), by Offering 2026 & 2034
    19. Figure 19: Europe Lawn Mower Market Revenue Share (%), by Offering 2026 & 2034
    20. Figure 20: Europe Lawn Mower Market Revenue (Billion), by Propulsion Type 2026 & 2034
    21. Figure 21: Europe Lawn Mower Market Revenue Share (%), by Propulsion Type 2026 & 2034
    22. Figure 22: Europe Lawn Mower Market Revenue (Billion), by Product Type 2026 & 2034
    23. Figure 23: Europe Lawn Mower Market Revenue Share (%), by Product Type 2026 & 2034
    24. Figure 24: Europe Lawn Mower Market Revenue (Billion), by Lawn Size 2026 & 2034
    25. Figure 25: Europe Lawn Mower Market Revenue Share (%), by Lawn Size 2026 & 2034
    26. Figure 26: Europe Lawn Mower Market Revenue (Billion), by Level of Autonomy 2026 & 2034
    27. Figure 27: Europe Lawn Mower Market Revenue Share (%), by Level of Autonomy 2026 & 2034
    28. Figure 28: Europe Lawn Mower Market Revenue (Billion), by Distribution Channel 2026 & 2034
    29. Figure 29: Europe Lawn Mower Market Revenue Share (%), by Distribution Channel 2026 & 2034
    30. Figure 30: Europe Lawn Mower Market Revenue (Billion), by End Use 2026 & 2034
    31. Figure 31: Europe Lawn Mower Market Revenue Share (%), by End Use 2026 & 2034
    32. Figure 32: Europe Lawn Mower Market Revenue (Billion), by Country 2026 & 2034
    33. Figure 33: Europe Lawn Mower Market Revenue Share (%), by Country 2026 & 2034
    34. Figure 34: Asia Pacific Lawn Mower Market Revenue (Billion), by Offering 2026 & 2034
    35. Figure 35: Asia Pacific Lawn Mower Market Revenue Share (%), by Offering 2026 & 2034
    36. Figure 36: Asia Pacific Lawn Mower Market Revenue (Billion), by Propulsion Type 2026 & 2034
    37. Figure 37: Asia Pacific Lawn Mower Market Revenue Share (%), by Propulsion Type 2026 & 2034
    38. Figure 38: Asia Pacific Lawn Mower Market Revenue (Billion), by Product Type 2026 & 2034
    39. Figure 39: Asia Pacific Lawn Mower Market Revenue Share (%), by Product Type 2026 & 2034
    40. Figure 40: Asia Pacific Lawn Mower Market Revenue (Billion), by Lawn Size 2026 & 2034
    41. Figure 41: Asia Pacific Lawn Mower Market Revenue Share (%), by Lawn Size 2026 & 2034
    42. Figure 42: Asia Pacific Lawn Mower Market Revenue (Billion), by Level of Autonomy 2026 & 2034
    43. Figure 43: Asia Pacific Lawn Mower Market Revenue Share (%), by Level of Autonomy 2026 & 2034
    44. Figure 44: Asia Pacific Lawn Mower Market Revenue (Billion), by Distribution Channel 2026 & 2034
    45. Figure 45: Asia Pacific Lawn Mower Market Revenue Share (%), by Distribution Channel 2026 & 2034
    46. Figure 46: Asia Pacific Lawn Mower Market Revenue (Billion), by End Use 2026 & 2034
    47. Figure 47: Asia Pacific Lawn Mower Market Revenue Share (%), by End Use 2026 & 2034
    48. Figure 48: Asia Pacific Lawn Mower Market Revenue (Billion), by Country 2026 & 2034
    49. Figure 49: Asia Pacific Lawn Mower Market Revenue Share (%), by Country 2026 & 2034
    50. Figure 50: South America Lawn Mower Market Revenue (Billion), by Offering 2026 & 2034
    51. Figure 51: South America Lawn Mower Market Revenue Share (%), by Offering 2026 & 2034
    52. Figure 52: South America Lawn Mower Market Revenue (Billion), by Propulsion Type 2026 & 2034
    53. Figure 53: South America Lawn Mower Market Revenue Share (%), by Propulsion Type 2026 & 2034
    54. Figure 54: South America Lawn Mower Market Revenue (Billion), by Product Type 2026 & 2034
    55. Figure 55: South America Lawn Mower Market Revenue Share (%), by Product Type 2026 & 2034
    56. Figure 56: South America Lawn Mower Market Revenue (Billion), by Lawn Size 2026 & 2034
    57. Figure 57: South America Lawn Mower Market Revenue Share (%), by Lawn Size 2026 & 2034
    58. Figure 58: South America Lawn Mower Market Revenue (Billion), by Level of Autonomy 2026 & 2034
    59. Figure 59: South America Lawn Mower Market Revenue Share (%), by Level of Autonomy 2026 & 2034
    60. Figure 60: South America Lawn Mower Market Revenue (Billion), by Distribution Channel 2026 & 2034
    61. Figure 61: South America Lawn Mower Market Revenue Share (%), by Distribution Channel 2026 & 2034
    62. Figure 62: South America Lawn Mower Market Revenue (Billion), by End Use 2026 & 2034
    63. Figure 63: South America Lawn Mower Market Revenue Share (%), by End Use 2026 & 2034
    64. Figure 64: South America Lawn Mower Market Revenue (Billion), by Country 2026 & 2034
    65. Figure 65: South America Lawn Mower Market Revenue Share (%), by Country 2026 & 2034
    66. Figure 66: Middle East & Africa Lawn Mower Market Revenue (Billion), by Offering 2026 & 2034
    67. Figure 67: Middle East & Africa Lawn Mower Market Revenue Share (%), by Offering 2026 & 2034
    68. Figure 68: Middle East & Africa Lawn Mower Market Revenue (Billion), by Propulsion Type 2026 & 2034
    69. Figure 69: Middle East & Africa Lawn Mower Market Revenue Share (%), by Propulsion Type 2026 & 2034
    70. Figure 70: Middle East & Africa Lawn Mower Market Revenue (Billion), by Product Type 2026 & 2034
    71. Figure 71: Middle East & Africa Lawn Mower Market Revenue Share (%), by Product Type 2026 & 2034
    72. Figure 72: Middle East & Africa Lawn Mower Market Revenue (Billion), by Lawn Size 2026 & 2034
    73. Figure 73: Middle East & Africa Lawn Mower Market Revenue Share (%), by Lawn Size 2026 & 2034
    74. Figure 74: Middle East & Africa Lawn Mower Market Revenue (Billion), by Level of Autonomy 2026 & 2034
    75. Figure 75: Middle East & Africa Lawn Mower Market Revenue Share (%), by Level of Autonomy 2026 & 2034
    76. Figure 76: Middle East & Africa Lawn Mower Market Revenue (Billion), by Distribution Channel 2026 & 2034
    77. Figure 77: Middle East & Africa Lawn Mower Market Revenue Share (%), by Distribution Channel 2026 & 2034
    78. Figure 78: Middle East & Africa Lawn Mower Market Revenue (Billion), by End Use 2026 & 2034
    79. Figure 79: Middle East & Africa Lawn Mower Market Revenue Share (%), by End Use 2026 & 2034
    80. Figure 80: Middle East & Africa Lawn Mower Market Revenue (Billion), by Country 2026 & 2034
    81. Figure 81: Middle East & Africa Lawn Mower Market Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Lawn Mower Market Revenue Billion Forecast, by Offering 2020 & 2034
    2. Table 2: Global Lawn Mower Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
    3. Table 3: Global Lawn Mower Market Revenue Billion Forecast, by Product Type 2020 & 2034
    4. Table 4: Global Lawn Mower Market Revenue Billion Forecast, by Lawn Size 2020 & 2034
    5. Table 5: Global Lawn Mower Market Revenue Billion Forecast, by Level of Autonomy 2020 & 2034
    6. Table 6: Global Lawn Mower Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    7. Table 7: Global Lawn Mower Market Revenue Billion Forecast, by End Use 2020 & 2034
    8. Table 8: Global Lawn Mower Market Revenue Billion Forecast, by Region 2020 & 2034
    9. Table 9: North America Lawn Mower Market Revenue Billion Forecast, by Offering 2020 & 2034
    10. Table 10: North America Lawn Mower Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
    11. Table 11: North America Lawn Mower Market Revenue Billion Forecast, by Product Type 2020 & 2034
    12. Table 12: North America Lawn Mower Market Revenue Billion Forecast, by Lawn Size 2020 & 2034
    13. Table 13: North America Lawn Mower Market Revenue Billion Forecast, by Level of Autonomy 2020 & 2034
    14. Table 14: North America Lawn Mower Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    15. Table 15: North America Lawn Mower Market Revenue Billion Forecast, by End Use 2020 & 2034
    16. Table 16: North America Lawn Mower Market Revenue Billion Forecast, by Country 2020 & 2034
    17. Table 17: USA Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    18. Table 18: Canada Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    19. Table 19: Mexico Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    20. Table 20: Europe Lawn Mower Market Revenue Billion Forecast, by Offering 2020 & 2034
    21. Table 21: Europe Lawn Mower Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
    22. Table 22: Europe Lawn Mower Market Revenue Billion Forecast, by Product Type 2020 & 2034
    23. Table 23: Europe Lawn Mower Market Revenue Billion Forecast, by Lawn Size 2020 & 2034
    24. Table 24: Europe Lawn Mower Market Revenue Billion Forecast, by Level of Autonomy 2020 & 2034
    25. Table 25: Europe Lawn Mower Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    26. Table 26: Europe Lawn Mower Market Revenue Billion Forecast, by End Use 2020 & 2034
    27. Table 27: Europe Lawn Mower Market Revenue Billion Forecast, by Country 2020 & 2034
    28. Table 28: Germany Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    29. Table 29: UK Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    30. Table 30: France Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    31. Table 31: Italy Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    32. Table 32: Spain Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    33. Table 33: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Offering 2020 & 2034
    34. Table 34: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
    35. Table 35: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Product Type 2020 & 2034
    36. Table 36: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Lawn Size 2020 & 2034
    37. Table 37: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Level of Autonomy 2020 & 2034
    38. Table 38: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    39. Table 39: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by End Use 2020 & 2034
    40. Table 40: Asia Pacific Lawn Mower Market Revenue Billion Forecast, by Country 2020 & 2034
    41. Table 41: China Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    42. Table 42: Japan Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    43. Table 43: India Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    44. Table 44: South Korea Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    45. Table 45: Australia Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    46. Table 46: South America Lawn Mower Market Revenue Billion Forecast, by Offering 2020 & 2034
    47. Table 47: South America Lawn Mower Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
    48. Table 48: South America Lawn Mower Market Revenue Billion Forecast, by Product Type 2020 & 2034
    49. Table 49: South America Lawn Mower Market Revenue Billion Forecast, by Lawn Size 2020 & 2034
    50. Table 50: South America Lawn Mower Market Revenue Billion Forecast, by Level of Autonomy 2020 & 2034
    51. Table 51: South America Lawn Mower Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    52. Table 52: South America Lawn Mower Market Revenue Billion Forecast, by End Use 2020 & 2034
    53. Table 53: South America Lawn Mower Market Revenue Billion Forecast, by Country 2020 & 2034
    54. Table 54: Brazil Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    55. Table 55: Argentina Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    56. Table 56: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Offering 2020 & 2034
    57. Table 57: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
    58. Table 58: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Product Type 2020 & 2034
    59. Table 59: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Lawn Size 2020 & 2034
    60. Table 60: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Level of Autonomy 2020 & 2034
    61. Table 61: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    62. Table 62: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by End Use 2020 & 2034
    63. Table 63: Middle East & Africa Lawn Mower Market Revenue Billion Forecast, by Country 2020 & 2034
    64. Table 64: UAE Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    65. Table 65: Saudi Arabia Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034
    66. Table 66: South Africa Lawn Mower Market Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the current size of the global lawn mower market?

    The global lawn mower market was valued at $35.3 billion in 2025 and is projected to reach $63.3 billion by 2033, growing at a CAGR of 7.9% from 2026 to 2033.

    2Which region dominates the lawn mower market?

    North America holds the largest market share, accounting for 35.37% of global revenue in 2025, driven by high adoption of advanced mowers and a strong landscaping services industry.

    3What are the key trends shaping the lawn mower market?

    Major trends include the shift toward battery-powered and robotic mowers, integration of smart home technologies, and the development of wire-free navigation systems that reduce installation complexity.

    4Who are the leading companies in the lawn mower market?

    Key players include Deere & Company, The Toro Company, Husqvarna Group, STIHL Group, Robert Bosch Power Tools GmbH, Honda Motor Co., Ltd., and Kubota Corporation, among others.

    5What is driving the adoption of robotic lawn mowers?

    Rising labor costs in landscaping, growing familiarity with smart home devices, and regulatory support for low-emission equipment are key drivers. The robotic mower segment is expected to grow at a CAGR of 10.3% from 2026 to 2035.

    6What are the main challenges in the lawn mower market?

    Challenges include high initial costs for advanced models, seasonal demand fluctuations, supply chain disruptions, and raw material price volatility, which can impact manufacturing and pricing strategies.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Conducted 120+ in-depth interviews with industry stakeholders across the value chain, including OEMs, component suppliers, distributors, and commercial end-users.
    • Interviewed key decision-makers such as Procurement Directors, Product Managers, Landscaping Service Managers, and Equipment Fleet Managers.
    • Primary research accounted for 70-80% of the total research effort, ensuring granular insights into market dynamics and validation of quantitative data.
    • Data collected through structured questionnaires, expert discussions, and observational visits to manufacturing facilities and dealerships.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Procurement Directors30%
    Product Managers25%
    Landscaping Service Managers25%
    Equipment Fleet Managers20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Lawn Mower OEMs40%
    Component Suppliers25%
    Distributors & Retailers20%
    Commercial End-Users10%
    Industry Associations5%

    Secondary Research & Industry Benchmarking

    • Leveraged 20-30% of research from secondary sources, including official trade statistics from UN Comtrade, World Bank, OECD, and US ITC.
    • Benchmarked against data from industry associations such as the Outdoor Power Equipment Institute (OPEI), European Garden Machinery Federation (EGMF), and the American Society of Agricultural and Biological Engineers (ASABE).
    • Utilized standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for company-level financial analysis.
    • Referenced regulatory publications from the U.S. Environmental Protection Agency (EPA), California Air Resources Board (CARB), and EU Safety Gate alerts for product safety and compliance.

    Demand Modeling & Market Estimation

    • Employed both top-down (global market size divided by segments) and bottom-up (sum of revenue from individual companies) approaches to estimate market size.
    • Bottom-up calculation based on quantitative metrics such as unit shipments, average selling prices (ASPs), replacement rates, and adoption rates by segment.
    • Demand modeled using regression analysis on historical data (2020-2025) and correlation with macroeconomic indicators (GDP, housing starts, disposable income).
    • Forecasts validated through multi-level data triangulation, combining primary interview findings, secondary trade data, and expert consensus.

    Data Accuracy & Quality Check

    • Guaranteed estimated data accuracy level of 85-90% through rigorous validation processes.
    • Every report is updated to the date of purchase, incorporating the latest market developments and data points.
    • Data triangulation across multiple sources to identify and resolve discrepancies.
    • Quality assurance by senior analysts and peer review to ensure consistency and reliability.