Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Japan Online Accommodation Booking Market Report 2026
Japan Online Accommodation Booking Market
Hospitality and Tourism / MARKET REPORT
Japan Online Accommodation Booking Market | Insight Market Data
Japan Online Accommodation Booking Market by Platform (Mobile Application, Website), by Mode of Booking (Third-Party Online Portals, Direct/Captive Portals), by Property Type (Hotels & Resorts, Vacation Rentals, Hostels & Budget Accommodations, Alternate Lodgings(Glamping, Farm-Stays)), by Kanto, by Kansai, by Chubu, by Hokkaido & Tohoku, by Chugoku & Shikoku, by Kyushu & Okinawa Forecast 2026-2034
Luxury hotel industry market valued at USD 118.4 billion in 2026, projected to reach USD 196.7 billion by 2033 at a 7.5% CAGR. Explore trends and insights.
Hotel self check-in and check-out kiosk market to reach $4.98 Billion by 2032 at 11% CAGR. Explore growth pathways, pricing, ROI and deployment strategies.
Nov 2026|244 pages
$2900.00
Airport retailing market to reach USD 187.67 Billion by 2035, growing at 15% CAGR. Explore duty-free, fashion, and digital retail trends.
Nov 2026|208 pages
$2900.00
The global airline IT solutions market is valued at $22.5 billion, growing at an 8.8% CAGR through 2033. Explore key trends, segmentation, and regional insights.
Nov 2026|222 pages
$2900.00
Airport sleeping pods market valued at USD 87.9M in 2025, growing at 7.1% CAGR to reach USD 175.6M by 2035. Get in-depth analysis, trends, and regional outlook.
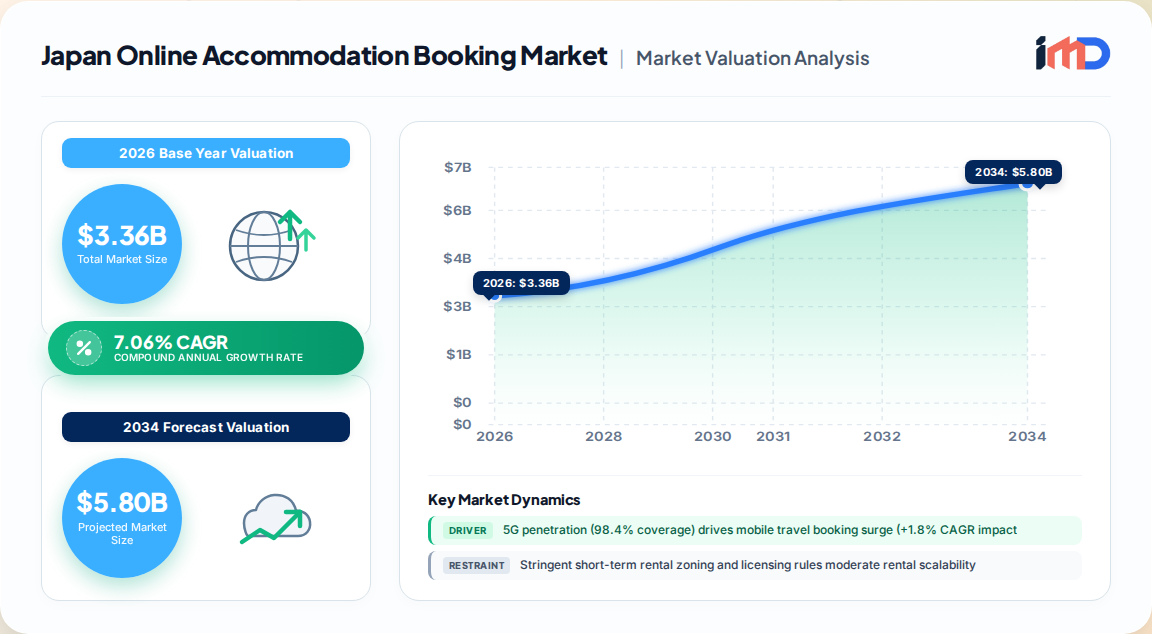
The Japan online accommodation booking market represents one of Asia-Pacific's most sophisticated and resilient digital travel ecosystems. Our proprietary market model values the sector at USD 3.36 billion in 2026, on an accelerated trajectory from USD 3.14 billion in 2025, with a forecast CAGR of 7.06% driving total market value to USD 4.73 billion by 2031. This expansion is anchored on a record 42.7 million international visitors recorded in 2025 and a domestic traveler base that has structurally digitized post-pandemic.
Japan Online Accommodation Booking Market Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.138 B
2025
3.360 B
2026
3.597 B
2027
3.851 B
2028
4.123 B
2029
4.414 B
2030
4.726 B
2031
The market is characterized by medium concentration, where domestic incumbents (Rakuten Travel, Jalan/Recruit, JTB, Ikyu) coexist alongside global OTAs (Booking.com, Expedia Group, Agoda, Airbnb, Trip.com Group) and specialist platforms (Relux, Travelko, Yahoo! Travel). Crucially, the channel mix is decisively mobile-first: mobile applications accounted for 67.16% of bookings in 2025 and are forecast to expand at an 11.55% CAGR through 2031, materially outpacing the overall market. Third-party online portals commanded 61.10% share of booking-mode volume in 2025, while direct/captive portals retain relevance for loyalty members and corporate accounts.
Property-type segmentation underscores the changing face of Japanese lodging demand. Hotels & resorts represented 46.75% of 2025 share, but vacation rentals are projected to grow at a 15.11% CAGR — the fastest of any property class — as regulatory modernization (the April 2026 centralized verification system) unlocks professionally managed inventory. Geographically, Kanto holds 36.44% of national value, though Kyushu & Okinawa is forecast to be the fastest-growing region at 9.23% CAGR through 2031, powered by regional dispersion subsidies and improved air connectivity.
Market Drivers: Demand-Side and Policy Catalysts
Our primary research identifies six structural drivers, each quantified below by its estimated percentage-point impact on the forecast CAGR.
Driver
Estimated CAGR Impact
Geographic Focus
5G penetration & mobile booking surge
+1.8%
National (98.4% population coverage)
Regulatory easing expands vacation rental supply
+1.3%
National (centralized verification from April 2026)
Travel subsidies boost domestic tourism
+1.2%
Fukushima, Tohoku, Kyushu
AI pricing strategies target Osaka Expo demand
+1.1%
Osaka, Tokyo, regional events
Rural incentives extend digital nomad stays
+0.9%
Nagasaki, Tohoku, coastal prefectures
SME-focused corporate travel bundles
+0.7%
Nagoya, Sapporo, Fukuoka
Japan's 98.4% 5G population coverage (as of March 2025) and high median download speeds have removed friction from visually rich booking journeys — virtual tours, video walkthroughs, and real-time inventory now load instantly on handsets, converting browse-to-book at rates that were previously unattainable on desktop. Prefectural campaigns, typified by Fukushima's multi-night traveler subsidies running through February 2026, are deliberately extending average stay length and shifting demand into under-visited regions. This policy architecture directly benefits regional inventory holders and the OTAs that maintain deep supplier relationships outside the three largest metros.
Restraints and Challenges
Stringent short-term rental regulation: Japan's private lodging regime layers national rules atop municipal overlays; heritage districts in Kyoto enforce tight residential-area caps. This moderates vacation rental scalability and tilts advantage toward professionally managed, compliance-ready operators.
Low digital literacy among the aging population: A meaningful slice of domestic demand, particularly for ryokan and onsen stays, still flows through phone and in-person channels, capping online conversion in rural segments.
Super-app margin compression: Platform economics are strained as super-apps bundle accommodation with payments, transport, and loyalty, forcing OTAs to defend share through discounting.
Hotel capacity constraints during peak events: Concerted demand spikes — Expo 2025 in Osaka, major sporting calendars — expose supply ceilings, pushing rate inflation but limiting volume conversion.
Value Chain and Distribution Dynamics
The Japanese online accommodation value chain is a three-tier structure. Tier one comprises accommodation suppliers: hotel groups, ryokan associations, professionally managed vacation-rental operators, and budget hostel chains. Tier two encompasses distribution intermediaries — domestic OTAs, global OTAs, bed banks, and channel managers — that aggregate and merchandize inventory. Tier three is the demand interface: mobile apps, websites, metasearch engines, and increasingly super-app ecosystems.
Notably, local OTAs are building SME-focused corporate travel bundles that integrate lodging, transport, and meeting solutions. Rakuten Travel's late-2025 global property coverage expansion allows SMEs to consolidate domestic and outbound hotel purchases into a single loyalty stack. Airline partners (ANA X, JAL) extend these bundles by exposing inventory inside their apps and loyalty programs, generating ancillary revenue without proprietary supply. This B2B2C layer raises average booking values and stabilizes seasonality for platforms serving regional business corridors.
Competitive Landscape and Strategic Positioning
The market's medium concentration masks vigorous strategic differentiation. Domestic incumbents compete on regional supplier depth, loyalty integration, and Japanese-language UX excellence; global OTAs leverage cross-border demand, review density, and dynamic packaging; specialists (Relux, Travelko, Ikyu) target high-end and experiential segments.
Player Archetype
Representative Platforms
Core Strategic Lever
Domestic mega-OTA
Rakuten Travel, Jalan (Recruit)
Loyalty stack, regional supplier depth, SME bundles
Segmentation Outlook: Platform, Property Type, and Geography
The platform split is decisive. Mobile applications hold 67.16% of 2025 bookings, expanding at 11.55% CAGR through 2031. Website bookings remain material for multi-room group reservations and policy-heavy corporate itineraries, where larger screens enable side-by-side comparison; the market maintains a pragmatic dual-channel equilibrium, though the balance continues to tilt mobile-first as 5G coverage deepens.
By property type, hotels & resorts lead at 46.75% share in 2025, while vacation rentals post the fastest growth at 15.11% CAGR, followed by hostels & budget accommodations and alternate lodgings (glamping, farm-stays). By mode of booking, third-party online portals hold 61.10% of 2025 share, with vacation rentals booked via third-party portals growing at a striking 13.72% CAGR.
Geographically, Kanto's 36.44% share reflects Tokyo's gravitational pull, but Kyushu & Okinawa's 9.23% CAGR signals the fastest regional expansion, supported by dispersion policy and inbound connectivity. Kansai holds elevated occupancy through the six-month Expo 2025 legacy, reinforcing algorithmic revenue tool adoption among smaller operators.
Kanto: Largest base, steadiest demand; investment case centers on loyalty and corporate travel depth rather than volume growth.
Kansai: Elevated post-Expo occupancy and strong cultural tourism; attractive for dynamic-pricing tooling and boutique supply.
Kyushu & Okinawa: Highest growth velocity (9.23% CAGR); white space in professionally managed vacation rentals and digital nomad-oriented extended stays.
Hokkaido & Tohoku: Seasonal ski and nature demand; subsidy-supported longer stays create cross-sell opportunities for domestic OTAs.
Chubu & Chugoku/Shikoku: Underpenetrated digitally; regional OTA partnerships and packaged API revenue tools offer scalable entry.
Japan Online Accommodation Booking Market Regional Market Share
Loading chart...
Strategic White-Space Analysis
Three under-served opportunity zones emerge from our primary interviews. First, SME corporate travel bundling remains fragmented despite early mover activity; integrated lodging-transport-meeting procurement tools can lift average booking values and repeat frequency. Second, AI-enabled dynamic pricing for independent and midscale properties is still nascent outside urban centers; cloud API accessibility allows smaller operators to capture RevPAR uplift previously reserved for enterprise chains. Third, rural digital nomad and long-stay products — supported by Nagasaki pilots and Tohoku revitalization zones — represent a nascent but policy-tailwinded segment where platforms can build defensible inventory moats ahead of demand maturity.
Import/Export & Supplier Dynamics
The Japan online accommodation market's cross-border dimension is significant. Inbound demand from Europe is facilitated by the EU-Japan Economic Partnership Agreement, in force since February 2019, which guarantees open services markets and non-discriminatory treatment for EU businesses operating in Japan — including travel distribution and hospitality services. EU firms already export over €28 billion in services to Japan annually. For accommodation platforms, this treaty environment smooths cross-border supplier contracting and data flows.
Domestic supply-side dynamics are shaped by licensed hotel and ryokan inventory constraints during peak events, offset by vacation rental supply unlocked through the April 2026 centralized verification system. The layered municipal regime means platform curation strategies must be compliance-native, favoring professional managers over casual hosts — a structural tailwind for established OTAs with legal and operational infrastructure.
Japan Online Accommodation Booking Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Japan Online Accommodation Booking Market REPORT HIGHLIGHTS
3.4.2. Low digital literacy among the aging population limits online conversion in rural segments
3.4.3. Profit margins compressed by super-app bundling and discount competition
3.4.4. Hotel capacity constraints during peak events limit volume conversion
3.5. Market Challenges
3.5.1. Balancing compliance complexity across municipal short-term rental overlays
3.5.2. Mitigating seasonality and capacity ceilings during major events
3.5.3. Defending OTA margins against super-app ecosystem competition
3.5.4. Bridging the digital divide for aging domestic travelers and rural suppliers
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Platform
5.1.1. Mobile Application
5.1.2. Website
5.2. Market Analysis, Insights and Forecast - by Mode of Booking
5.2.1. Third-Party Online Portals
5.2.2. Direct/Captive Portals
5.3. Market Analysis, Insights and Forecast - by Property Type
5.3.1. Hotels & Resorts
5.3.2. Vacation Rentals
5.3.3. Hostels & Budget Accommodations
5.3.4. Alternate Lodgings
5.3.4.1. Glamping
5.3.4.2. Farm-Stays
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Kanto
5.4.2. Kansai
5.4.3. Chubu
5.4.4. Hokkaido & Tohoku
5.4.5. Chugoku & Shikoku
5.4.6. Kyushu & Okinawa
6. Kanto Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Platform
6.1.1. Mobile Application
6.1.2. Website
6.2. Market Analysis, Insights and Forecast - by Mode of Booking
6.2.1. Third-Party Online Portals
6.2.2. Direct/Captive Portals
6.3. Market Analysis, Insights and Forecast - by Property Type
6.3.1. Hotels & Resorts
6.3.2. Vacation Rentals
6.3.3. Hostels & Budget Accommodations
6.3.4. Alternate Lodgings
6.3.4.1. Glamping
6.3.4.2. Farm-Stays
7. Kansai Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Platform
7.1.1. Mobile Application
7.1.2. Website
7.2. Market Analysis, Insights and Forecast - by Mode of Booking
7.2.1. Third-Party Online Portals
7.2.2. Direct/Captive Portals
7.3. Market Analysis, Insights and Forecast - by Property Type
7.3.1. Hotels & Resorts
7.3.2. Vacation Rentals
7.3.3. Hostels & Budget Accommodations
7.3.4. Alternate Lodgings
7.3.4.1. Glamping
7.3.4.2. Farm-Stays
8. Chubu Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Platform
8.1.1. Mobile Application
8.1.2. Website
8.2. Market Analysis, Insights and Forecast - by Mode of Booking
8.2.1. Third-Party Online Portals
8.2.2. Direct/Captive Portals
8.3. Market Analysis, Insights and Forecast - by Property Type
8.3.1. Hotels & Resorts
8.3.2. Vacation Rentals
8.3.3. Hostels & Budget Accommodations
8.3.4. Alternate Lodgings
8.3.4.1. Glamping
8.3.4.2. Farm-Stays
9. Hokkaido & Tohoku Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Platform
9.1.1. Mobile Application
9.1.2. Website
9.2. Market Analysis, Insights and Forecast - by Mode of Booking
9.2.1. Third-Party Online Portals
9.2.2. Direct/Captive Portals
9.3. Market Analysis, Insights and Forecast - by Property Type
9.3.1. Hotels & Resorts
9.3.2. Vacation Rentals
9.3.3. Hostels & Budget Accommodations
9.3.4. Alternate Lodgings
9.3.4.1. Glamping
9.3.4.2. Farm-Stays
10. Chugoku & Shikoku Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Platform
10.1.1. Mobile Application
10.1.2. Website
10.2. Market Analysis, Insights and Forecast - by Mode of Booking
10.2.1. Third-Party Online Portals
10.2.2. Direct/Captive Portals
10.3. Market Analysis, Insights and Forecast - by Property Type
10.3.1. Hotels & Resorts
10.3.2. Vacation Rentals
10.3.3. Hostels & Budget Accommodations
10.3.4. Alternate Lodgings
10.3.4.1. Glamping
10.3.4.2. Farm-Stays
11. Kyushu & Okinawa Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Platform
11.1.1. Mobile Application
11.1.2. Website
11.2. Market Analysis, Insights and Forecast - by Mode of Booking
11.2.1. Third-Party Online Portals
11.2.2. Direct/Captive Portals
11.3. Market Analysis, Insights and Forecast - by Property Type
11.3.1. Hotels & Resorts
11.3.2. Vacation Rentals
11.3.3. Hostels & Budget Accommodations
11.3.4. Alternate Lodgings
11.3.4.1. Glamping
11.3.4.2. Farm-Stays
12. Competitive Analysis
12.1. Company Profiles
12.1.1. Rakuten Travel
12.1.1.1. Company Overview
12.1.1.2. Products
12.1.1.3. Company Financials
12.1.1.4. SWOT Analysis
12.1.2. Jalan (Recruit Co.)
12.1.2.1. Company Overview
12.1.2.2. Products
12.1.2.3. Company Financials
12.1.2.4. SWOT Analysis
12.1.3. Booking.com B.V.
12.1.3.1. Company Overview
12.1.3.2. Products
12.1.3.3. Company Financials
12.1.3.4. SWOT Analysis
12.1.4. Expedia Group Inc.
12.1.4.1. Company Overview
12.1.4.2. Products
12.1.4.3. Company Financials
12.1.4.4. SWOT Analysis
12.1.5. Agoda Company Pte. Ltd.
12.1.5.1. Company Overview
12.1.5.2. Products
12.1.5.3. Company Financials
12.1.5.4. SWOT Analysis
12.1.6. Airbnb Inc.
12.1.6.1. Company Overview
12.1.6.2. Products
12.1.6.3. Company Financials
12.1.6.4. SWOT Analysis
12.1.7. Trip.com Group Ltd.
12.1.7.1. Company Overview
12.1.7.2. Products
12.1.7.3. Company Financials
12.1.7.4. SWOT Analysis
12.1.8. Ikyu Corporation
12.1.8.1. Company Overview
12.1.8.2. Products
12.1.8.3. Company Financials
12.1.8.4. SWOT Analysis
12.1.9. Hotels.com
12.1.9.1. Company Overview
12.1.9.2. Products
12.1.9.3. Company Financials
12.1.9.4. SWOT Analysis
12.1.10. Travelko
12.1.10.1. Company Overview
12.1.10.2. Products
12.1.10.3. Company Financials
12.1.10.4. SWOT Analysis
12.1.11. JTB Corp.
12.1.11.1. Company Overview
12.1.11.2. Products
12.1.11.3. Company Financials
12.1.11.4. SWOT Analysis
12.1.12. H.I.S. Co. Ltd.
12.1.12.1. Company Overview
12.1.12.2. Products
12.1.12.3. Company Financials
12.1.12.4. SWOT Analysis
12.1.13. ANA X Inc. (ANA Traveler)
12.1.13.1. Company Overview
12.1.13.2. Products
12.1.13.3. Company Financials
12.1.13.4. SWOT Analysis
12.1.14. Nippon Travel Agency (Tabimado)
12.1.14.1. Company Overview
12.1.14.2. Products
12.1.14.3. Company Financials
12.1.14.4. SWOT Analysis
12.1.15. Loco Partners (Relux)
12.1.15.1. Company Overview
12.1.15.2. Products
12.1.15.3. Company Financials
12.1.15.4. SWOT Analysis
12.1.16. Yahoo! Travel (Yahoo Japan)
12.1.16.1. Company Overview
12.1.16.2. Products
12.1.16.3. Company Financials
12.1.16.4. SWOT Analysis
12.1.17. Rurubu Travel
12.1.17.1. Company Overview
12.1.17.2. Products
12.1.17.3. Company Financials
12.1.17.4. SWOT Analysis
12.1.18. KNT-CT Holdings Co. Ltd.
12.1.18.1. Company Overview
12.1.18.2. Products
12.1.18.3. Company Financials
12.1.18.4. SWOT Analysis
12.1.19. Voyagin (Rakuten Group)
12.1.19.1. Company Overview
12.1.19.2. Products
12.1.19.3. Company Financials
12.1.19.4. SWOT Analysis
12.1.20. Traveloka Japan
12.1.20.1. Company Overview
12.1.20.2. Products
12.1.20.3. Company Financials
12.1.20.4. SWOT Analysis
12.1.21. Japan Online Traveler
12.1.21.1. Company Overview
12.1.21.2. Products
12.1.21.3. Company Financials
12.1.21.4. SWOT Analysis
12.1.22. JAPANiCAN
12.1.22.1. Company Overview
12.1.22.2. Products
12.1.22.3. Company Financials
12.1.22.4. SWOT Analysis
12.1.23. Bear Luxe
12.1.23.1. Company Overview
12.1.23.2. Products
12.1.23.3. Company Financials
12.1.23.4. SWOT Analysis
12.2. Market Entropy
12.2.1. Company's Key Areas Served
12.2.2. Recent Developments
12.3. Company Market Share Analysis, 2026
12.3.1. Top 5 Companies Market Share Analysis
12.3.2. Top 3 Companies Market Share Analysis
12.4. List of Potential Customers
List of Figures
Figure 1: Global Japan Online Accommodation Booking Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Kanto Japan Online Accommodation Booking Market Revenue (Billion), by Platform 2026 & 2034
Figure 3: Kanto Japan Online Accommodation Booking Market Revenue Share (%), by Platform 2026 & 2034
Figure 4: Kanto Japan Online Accommodation Booking Market Revenue (Billion), by Mode of Booking 2026 & 2034
Figure 5: Kanto Japan Online Accommodation Booking Market Revenue Share (%), by Mode of Booking 2026 & 2034
Figure 6: Kanto Japan Online Accommodation Booking Market Revenue (Billion), by Property Type 2026 & 2034
Figure 7: Kanto Japan Online Accommodation Booking Market Revenue Share (%), by Property Type 2026 & 2034
Figure 8: Kanto Japan Online Accommodation Booking Market Revenue (Billion), by Country 2026 & 2034
Figure 9: Kanto Japan Online Accommodation Booking Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Kansai Japan Online Accommodation Booking Market Revenue (Billion), by Platform 2026 & 2034
Figure 11: Kansai Japan Online Accommodation Booking Market Revenue Share (%), by Platform 2026 & 2034
Figure 12: Kansai Japan Online Accommodation Booking Market Revenue (Billion), by Mode of Booking 2026 & 2034
Figure 13: Kansai Japan Online Accommodation Booking Market Revenue Share (%), by Mode of Booking 2026 & 2034
Figure 14: Kansai Japan Online Accommodation Booking Market Revenue (Billion), by Property Type 2026 & 2034
Figure 15: Kansai Japan Online Accommodation Booking Market Revenue Share (%), by Property Type 2026 & 2034
Figure 16: Kansai Japan Online Accommodation Booking Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Kansai Japan Online Accommodation Booking Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Chubu Japan Online Accommodation Booking Market Revenue (Billion), by Platform 2026 & 2034
Figure 19: Chubu Japan Online Accommodation Booking Market Revenue Share (%), by Platform 2026 & 2034
Figure 20: Chubu Japan Online Accommodation Booking Market Revenue (Billion), by Mode of Booking 2026 & 2034
Figure 21: Chubu Japan Online Accommodation Booking Market Revenue Share (%), by Mode of Booking 2026 & 2034
Figure 22: Chubu Japan Online Accommodation Booking Market Revenue (Billion), by Property Type 2026 & 2034
Figure 23: Chubu Japan Online Accommodation Booking Market Revenue Share (%), by Property Type 2026 & 2034
Figure 24: Chubu Japan Online Accommodation Booking Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Chubu Japan Online Accommodation Booking Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue (Billion), by Platform 2026 & 2034
Figure 27: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Share (%), by Platform 2026 & 2034
Figure 28: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue (Billion), by Mode of Booking 2026 & 2034
Figure 29: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Share (%), by Mode of Booking 2026 & 2034
Figure 30: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue (Billion), by Property Type 2026 & 2034
Figure 31: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Share (%), by Property Type 2026 & 2034
Figure 32: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue (Billion), by Platform 2026 & 2034
Figure 35: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Share (%), by Platform 2026 & 2034
Figure 36: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue (Billion), by Mode of Booking 2026 & 2034
Figure 37: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Share (%), by Mode of Booking 2026 & 2034
Figure 38: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue (Billion), by Property Type 2026 & 2034
Figure 39: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Share (%), by Property Type 2026 & 2034
Figure 40: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue (Billion), by Platform 2026 & 2034
Figure 43: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Share (%), by Platform 2026 & 2034
Figure 44: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue (Billion), by Mode of Booking 2026 & 2034
Figure 45: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Share (%), by Mode of Booking 2026 & 2034
Figure 46: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue (Billion), by Property Type 2026 & 2034
Figure 47: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Share (%), by Property Type 2026 & 2034
Figure 48: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 2: Global Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 3: Global Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 4: Global Japan Online Accommodation Booking Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Kanto Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 6: Kanto Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 7: Kanto Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 8: Kanto Japan Online Accommodation Booking Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Kansai Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 10: Kansai Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 11: Kansai Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 12: Kansai Japan Online Accommodation Booking Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Chubu Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 14: Chubu Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 15: Chubu Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 16: Chubu Japan Online Accommodation Booking Market Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 18: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 19: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 20: Hokkaido & Tohoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 22: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 23: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 24: Chugoku & Shikoku Japan Online Accommodation Booking Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 26: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Billion Forecast, by Mode of Booking 2020 & 2034
Table 27: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Billion Forecast, by Property Type 2020 & 2034
Table 28: Kyushu & Okinawa Japan Online Accommodation Booking Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the size of the Japan online accommodation booking market?
Our proprietary research values the Japan online accommodation booking market at USD 3.36 billion in 2026, growing from USD 3.14 billion in 2025. The market is forecast to reach USD 4.73 billion by 2031 at a 7.06% CAGR.
2Which platform segment leads the Japan online accommodation booking market?
Mobile applications commanded 67.16% of bookings by platform in 2025 and are projected to expand at an 11.55% CAGR through 2031, significantly outpacing website-based bookings.
3Who are the major players in the Japan online accommodation booking market?
Key operators include Rakuten Travel, Jalan (Recruit Co.), Booking.com, Expedia Group (including Hotels.com), Agoda, Airbnb, Trip.com Group, Ikyu Corporation, JTB Corp., and H.I.S. Co., Ltd., among others.
4Which region in Japan is the fastest-growing for online accommodation bookings?
Kyushu & Okinawa is forecast to be the fastest-growing region at a 9.23% CAGR through 2031, supported by regional dispersion policies and improved inbound connectivity, while Kanto holds the largest share at 36.44%.
5What is driving growth in the Japan online accommodation booking market?
Key drivers include 5G penetration (98.4% population coverage) boosting mobile bookings (+1.8% CAGR impact), regulatory easing expanding vacation rental supply (+1.3%), prefectural travel subsidies (+1.2%), and AI pricing strategies targeting event-driven demand (+1.1%).
6What is the fastest-growing property type in the Japan online accommodation booking market?
Vacation rentals are projected to grow at a 15.11% CAGR through 2031, the fastest of any property type, though hotels & resorts retain the largest share at 46.75% in 2025.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We execute a primary-first research program constituting 70–80% of total effort, drawing on structured interviews with 4–5 company types across the Japan online accommodation value chain: domestic and global online travel agencies (OTAs), accommodation suppliers (hotel groups, ryokan associations, professionally managed vacation rental operators), travel management companies (TMCs), channel managers and distribution technology vendors, and payment/loyalty platform providers.
Interviews target 3–4 stakeholder job titles including Chief Revenue Officer, Head of Distribution & Connectivity, Director of Revenue Management, and Travel Procurement Manager, ensuring coverage of both supply-side and demand-side perspectives.
We triangulate interview findings with proprietary panel data on booking conversion, average daily rate (ADR), and loyalty program engagement, ensuring that every CAGR and market-size estimate is grounded in verified primary inputs.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Revenue Officer
30%
Head of Distribution & Connectivity
28%
Director of Revenue Management
24%
Travel Procurement Manager
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Domestic & Global OTAs
40%
Accommodation Suppliers
25%
Channel Managers & Tech Vendors
15%
Travel Management Companies
12%
Payment & Loyalty Platforms
8%
Secondary Research & Industry Benchmarking
20–30% of research effort is allocated to secondary validation using official multilateral sources: UN Comtrade for cross-border travel services flows, World Bank and OECD tourism statistics, Japan's Statistics Bureau and Japan National Tourism Organization (JNTO) visitor arrivals data, and the EU-Japan Economic Partnership Agreement framework for services trade benchmarking.
Standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used for corporate financial analysis, deal tracking, and competitive intelligence on OTAs, hotel groups, and travel technology vendors.
Industry association sources — including the Japan Association of Travel Agents (JATA), the Japan Hotel Association, and the Japan Ryokan & Hotel Association — provide regulatory and operational benchmarking, supplementing official .gov and .org publications.
Demand Modeling & Market Estimation
We run top-down and bottom-up methodologies simultaneously. The top-down model sizes the market from national tourism receipts and digital penetration rates; the bottom-up model aggregates platform-level booking volumes, take rates, and property-level occupancy data.
Bottom-up estimation employs 3–4 specific quantitative metrics: online booking penetration rate by property type, average daily rate (ADR) by region, mobile conversion share by platform, and inventory-listing growth rates for licensed vacation rentals.
Multi-level data triangulation reconciles top-down and bottom-up outputs against JNTO arrival statistics, prefectural accommodation surveys, and platform-reported GMV where available, producing a single consolidated market size and forecast.
Data Accuracy & Quality Check
Every report guarantees an estimated data accuracy level of 85–90%, validated through cross-referencing of primary interview data against official statistical benchmarks.
We apply a structured quality-assurance protocol: outlier detection across regional and segment estimates, sensitivity analysis on CAGR assumptions, and scenario modeling for regulatory and demand shocks (e.g., short-term rental zoning changes, event-driven demand spikes).
All datasets are updated to the date of purchase, ensuring forecasts reflect the latest inbound arrival figures, regulatory developments, and platform announcements.