Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Indonesian Logistics Industry Market Size, Trends & Forecast 2026-2034
Indonesian Logistics Industry
Logistics / MARKET REPORT
Indonesian Logistics Industry | Insight Market Data
Indonesian Logistics Industry by Model Type (2PL, 3PL, 4PL), by Transportation Mode (Roadways, Seaways, Railways, Airways), by End Use (Manufacturing, Consumer Goods, Retail, Food and Beverages, IT Hardware, Healthcare, Chemicals, Construction, Automotive, Telecom, Oil and Gas, Others), by Java, by Sumatra, by Kalimantan, by Sulawesi, by Others (Papua, Lesser Sunda Islands, Maluku) Forecast 2026-2034
US air freight transport market was USD 66.70B in 2026, growing at 4.08% CAGR to reach USD 91.81B by 2034, driven by e-commerce and cold-chain demand.
Nov 2026|219 pages
$2900.00
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.
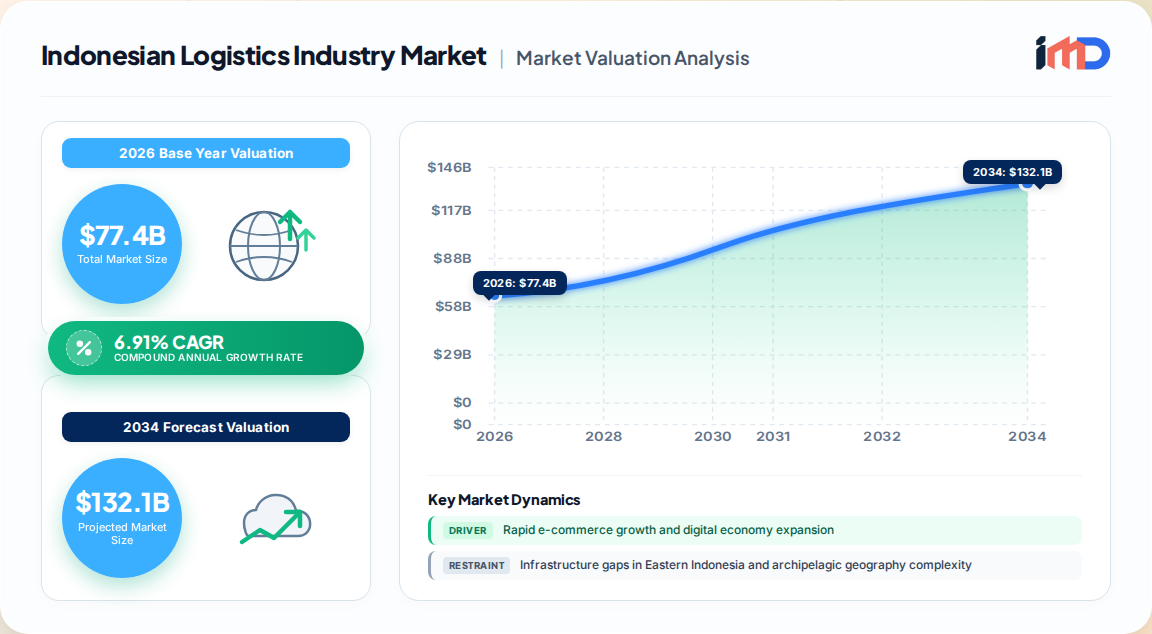
The Indonesian logistics industry market represents one of the most dynamic and rapidly evolving supply chain ecosystems in Southeast Asia. Our proprietary primary research estimates the market at USD 77.4 Billion in 2026, expanding from USD 72.4 Billion in 2025 and projected to reach USD 132.2 Billion by 2034, reflecting a robust CAGR of 6.91% over the forecast period. This growth trajectory is underpinned by structural economic transformation, aggressive infrastructure investment, and the accelerating digitization of trade flows across the 17,000-island archipelago.
Indonesian Logistics Industry Market Size (In Billion)
150.0B
100.0B
50.0B
0
72.40 B
2025
77.40 B
2026
82.75 B
2027
88.47 B
2028
94.58 B
2029
101.1 B
2030
108.1 B
2031
Indonesia's logistics sector is uniquely characterized by its archipelagic geography, which necessitates a complex multimodal transport network spanning road, sea, rail, and air. The sector contributes significantly to the national economy, with logistics costs as a percentage of GDP remaining a key policy focus as the government targets efficiency gains through the National Logistics System (Sislognas). Our analysis indicates that manufacturing, wholesale and retail trade, and consumer goods collectively account for over 60% of total logistics expenditure, with the wholesale and retail trade segment forecast to grow at a 6.52% CAGR through 2032, the fastest among end-use industries.
Key Market Drivers & Growth Catalysts
The expansion of the Indonesian logistics industry market is propelled by five interconnected structural drivers:
E-commerce and Parcel Volume Surge: Indonesia's digital economy is expanding at an unprecedented rate, with e-commerce generating a 35% higher volume of small parcel shipments compared to traditional retail channels. Internet penetration and smartphone adoption have fundamentally reshaped consumer expectations, demanding sophisticated last-mile delivery networks and automated fulfillment centers. Leading operators are investing heavily in warehouse automation, real-time tracking, and dynamic route optimization to manage peak volumes.
Infrastructure Development Megaprojects: The government's infrastructure agenda, including toll road corridors, seaport expansions, and airport modernization, has reduced overland transit times by as much as 30% in key economic corridors. New toll roads connecting industrial estates to ports have significantly lowered logistical friction, while the development of Special Economic Zones (SEZs) and logistics parks is consolidating fragmented supply chains.
Trade Liberalization and Regional Integration: Indonesia's strategic position along major global trade routes, coupled with participation in RCEP and ASEAN trade facilitation agreements, is driving cross-border logistics demand. Export-oriented manufacturing sectors, particularly automotive, electronics, and consumer goods, require increasingly sophisticated end-to-end logistics solutions.
Technology Adoption and Digitalization: Logistics providers are deploying IoT sensors, cloud-based platforms, and AI-driven analytics to achieve real-time supply chain visibility. Our research indicates that AI and machine learning integration improves demand forecasting accuracy by up to 25%, while automated warehouse systems increase order picking accuracy to over 99.5%. Digital freight marketplaces are also democratizing access to carrier networks, particularly for SME shippers.
Government Policy Support: The National Logistics System framework, coupled with deregulation initiatives aimed at reducing red tape, is fostering a more conducive investment climate. Fiscal incentives for logistics park development and SEZ operations are attracting both domestic and foreign capital.
Market Restraints & Operational Challenges
Despite strong fundamentals, the Indonesian logistics industry market faces several structural constraints that temper growth potential:
Archipelagic Geography and Infrastructure Gaps: While Java benefits from relatively developed infrastructure, Eastern Indonesia—including Sulawesi, Papua, and the Lesser Sunda Islands—suffers from inadequate road networks, limited port capacity, and unreliable inter-island shipping schedules. This disparity creates significant cost differentials, with logistics costs in remote regions often double those in Java.
Skilled Labor Shortages: A critical bottleneck is the shortage of logistics professionals trained in advanced analytics, automation management, and integrated supply chain planning. This talent gap constrains the ability of firms to fully leverage technology investments, limiting productivity gains and service quality improvements.
Regulatory Complexity and Bureaucracy: Despite reform efforts, cross-border cargo clearance and customs procedures remain fragmented across jurisdictions. Local content requirements and varying provincial regulations add compliance costs, particularly for 3PL providers operating multi-island networks.
Fuel Price Volatility and Environmental Regulations: Fuel accounts for up to 30% of operating costs for road freight operators. Global oil price fluctuations, exacerbated by geopolitical tensions, create cost uncertainty. Simultaneously, tightening emission norms are pushing operators to invest in fleet modernization and green logistics practices, requiring significant capital expenditure.
Competitive Landscape & Strategic Dynamics
The Indonesian logistics industry market is characterized by medium market concentration, with a mix of state-owned enterprises, regional champions, and global integrators competing across segments. Key players include JNE, Pos Indonesia, Tiki, DHL, J&T Express, SiCepat, Kuehne+Nagel, DSV A/S, and FedEx, among others.
Competitive strategy is increasingly defined by:
Network Density and Last-Mile Reach: Domestic operators such as JNE and J&T Express have built extensive agent networks spanning thousands of islands, enabling them to serve underserved regions. Global players like DHL and FedEx leverage international networks to capture cross-border trade flows.
Technology Investment: Leading 3PLs are investing in warehouse automation, AI-driven route optimization, and digital freight platforms. Our primary interviews indicate that top-tier operators have achieved 15% improvements in on-time delivery metrics through transport management system upgrades.
Strategic Partnerships and M&A: Consolidation is accelerating as larger players acquire regional logistics firms to expand geographic coverage and service capabilities. Partnerships between e-commerce platforms and logistics providers are deepening, with exclusivity arrangements becoming common.
Sustainability Initiatives: Green logistics is emerging as a differentiator, with operators piloting electric delivery vehicles, energy-efficient warehousing, and sustainable packaging. Companies integrating green practices report 5-10% improvements in brand perception and customer loyalty.
Segmentation Analysis
The Indonesian logistics industry market is segmented across multiple dimensions:
Segment Category
Key Sub-Segments
Market Dynamics
By Model Type
2PL, 3PL, 4PL
3PL dominates with approximately 45% share; 4PL is fastest-growing at 9.6% CAGR
By Transportation Mode
Roadways, Seaways, Railways, Airways
Road freight handles over 70% of intra-island distribution; sea freight is critical for inter-island shipping; air freight serves time-sensitive sectors
By End-Use Industry
Manufacturing, Consumer Goods, Retail, F&B, IT Hardware, Healthcare, Chemicals, Construction, Automotive, Telecom, Oil & Gas
Manufacturing holds 28.52% share (2026); wholesale and retail trade fastest-growing at 6.52% CAGR
By Region
Java, Sumatra, Kalimantan, Sulawesi, Others
Java dominates with approximately 58% market share, reflecting its industrial and population concentration
Regional Outlook and Investment Hotspots
Java remains the undisputed epicenter of Indonesian logistics activity, accounting for an estimated 58% of market value. The island hosts the nation's largest industrial estates, busiest ports (Tanjung Priok), and highest population density, driving both consumption and production-related logistics demand. Greater Jakarta alone represents a substantial share of national parcel volumes.
Indonesian Logistics Industry Regional Market Share
Loading chart...
Sumatra (approximately 21% share) benefits from palm oil, rubber, and manufacturing exports, with connectivity to Singapore and Malaysia through the Malacca Strait. Kalimantan (8%) is witnessing increased activity from mining and the new capital city (Nusantara) development, though infrastructure remains nascent. Sulawesi (7%) is emerging as an industrial hub, particularly for nickel processing and smelting, requiring specialized bulk logistics. Eastern Indonesia, including Papua and the Lesser Sunda Islands, accounts for the remaining 6% but offers long-term growth potential as infrastructure improves.
Investment opportunities are concentrated in:
Warehousing and Fulfillment Centers near major consumption centers and industrial estates.
Cold Chain Infrastructure for food and pharmaceuticals, where capacity gaps remain significant.
Digital Freight Platforms that aggregate fragmented carrier capacity and provide transparency.
Inter-Island Shipping modernization, including container handling and port efficiency improvements.
Value Chain Analysis
The Indonesian logistics value chain spans multiple stages, each with distinct participants and value drivers:
First-Mile and Origin Services: Raw material suppliers and manufacturers ship goods to distribution centers or ports. Key participants include trucking companies, freight forwarders, and customs brokers. Efficiency is often constrained by traffic congestion and fragmented carrier markets.
Main Haul and Inter-Island Transport: Sea freight dominates inter-island movement, with Pelni and private shipping lines providing container and general cargo services. Port operators (Pelindo) manage terminal handling. Rail freight, though underdeveloped, is growing for bulk commodities like coal and palm oil.
Warehousing and Storage: Public and private warehouses, including bonded logistics centers and SEZ facilities, provide storage, inventory management, and value-added services. Automation adoption is accelerating in Java but remains limited in outer islands.
Last-Mile Delivery: The most dynamic segment, driven by e-commerce. Motorcycles, vans, and trucks handle final delivery, with delivery density and route optimization critical for cost efficiency. Cash-on-delivery remains significant, though digital payments are gaining share.
Reverse Logistics: Returns management for e-commerce and end-of-life product recovery is a nascent but growing segment, particularly in electronics and automotive.
Strategic White-Space Analysis
Our analysis identifies several underserved or emerging opportunity areas within the Indonesian logistics industry market:
Cold Chain Logistics for Agriculture and Healthcare: Indonesia's vast agricultural output and expanding pharmaceutical sector require reliable temperature-controlled logistics. Current cold chain capacity is concentrated in Java, leaving significant gaps in Sumatra, Sulawesi, and Kalimantan.
Integrated 4PL Solutions: As supply chains become more complex, demand for 4PL providers that orchestrate multiple 3PLs and technology partners is rising. This segment is growing at 9.6% CAGR, yet few domestic operators possess the requisite capabilities.
Cross-Border E-Commerce Logistics: With cross-border trade expanding, logistics providers offering seamless customs clearance, fulfillment, and last-mile delivery for international e-commerce are well-positioned.
Green Logistics Services: Sustainable supply chain solutions, including carbon footprint tracking, electric fleet management, and reverse logistics for packaging, represent a white space with growing corporate demand.
Logistics Technology Platforms: SaaS-based TMS, WMS, and digital freight matching platforms that serve SME shippers and carriers remain fragmented and underpenetrated.
Indonesian Logistics Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Indonesian Logistics Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.91% from 2020-2034
Segmentation
By Model Type
2PL
3PL
4PL
By Transportation Mode
Roadways
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rapid e-commerce growth and digital economy expansion
3.1.2. Substantial government investment in toll roads, seaports, and airports
3.1.3. Regional trade liberalization and integration through RCEP and ASEAN agreements
3.1.4. Adoption of advanced technologies improving operational efficiency
3.1.5. Supportive government policies including National Logistics System and SEZ incentives
3.2.2. Adoption of IoT, blockchain, and AI for supply chain visibility and predictive analytics
3.2.3. Green logistics practices including electric vehicles and sustainable warehousing
3.2.4. Strategic partnerships and collaborations to strengthen multi-island supply chain networks
3.3. Market Restrains
3.3.1. Infrastructure gaps in Eastern Indonesia and archipelagic geography complexity
3.3.2. Regulatory complexities and fragmented customs procedures across jurisdictions
3.3.3. Skilled labor shortages in logistics analytics and automation management
Seaways
Railways
Airways
By End Use
Manufacturing
Consumer Goods
Retail
Food and Beverages
IT Hardware
Healthcare
Chemicals
Construction
Automotive
Telecom
Oil and Gas
Others
By Geography
Java
Sumatra
Kalimantan
Sulawesi
Others
Papua
Lesser Sunda Islands
Maluku
3.3.4. Fuel price volatility and rising environmental compliance costs
3.4. Market Restraints
3.4.1. Infrastructure gaps in Eastern Indonesia and archipelagic geography complexity
3.4.2. Regulatory complexities and fragmented customs procedures across jurisdictions
3.4.3. Skilled labor shortages in logistics analytics and automation management
3.4.4. Fuel price volatility and rising environmental compliance costs
3.5. Market Challenges
3.5.1. Archipelagic geography and connectivity disparities between Java and outer islands
3.5.2. Talent gap constraining technology adoption and modernization
3.5.3. Volatile fuel prices and currency fluctuations impacting operating costs
3.5.4. Complex regulatory environment and local content requirements
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Model Type
5.1.1. 2PL
5.1.2. 3PL
5.1.3. 4PL
5.2. Market Analysis, Insights and Forecast - by Transportation Mode
5.2.1. Roadways
5.2.2. Seaways
5.2.3. Railways
5.2.4. Airways
5.3. Market Analysis, Insights and Forecast - by End Use
5.3.1. Manufacturing
5.3.2. Consumer Goods
5.3.3. Retail
5.3.4. Food and Beverages
5.3.5. IT Hardware
5.3.6. Healthcare
5.3.7. Chemicals
5.3.8. Construction
5.3.9. Automotive
5.3.10. Telecom
5.3.11. Oil and Gas
5.3.12. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Java
5.4.2. Sumatra
5.4.3. Kalimantan
5.4.4. Sulawesi
5.4.5. Others
6. Java Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Model Type
6.1.1. 2PL
6.1.2. 3PL
6.1.3. 4PL
6.2. Market Analysis, Insights and Forecast - by Transportation Mode
6.2.1. Roadways
6.2.2. Seaways
6.2.3. Railways
6.2.4. Airways
6.3. Market Analysis, Insights and Forecast - by End Use
6.3.1. Manufacturing
6.3.2. Consumer Goods
6.3.3. Retail
6.3.4. Food and Beverages
6.3.5. IT Hardware
6.3.6. Healthcare
6.3.7. Chemicals
6.3.8. Construction
6.3.9. Automotive
6.3.10. Telecom
6.3.11. Oil and Gas
6.3.12. Others
7. Sumatra Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Model Type
7.1.1. 2PL
7.1.2. 3PL
7.1.3. 4PL
7.2. Market Analysis, Insights and Forecast - by Transportation Mode
7.2.1. Roadways
7.2.2. Seaways
7.2.3. Railways
7.2.4. Airways
7.3. Market Analysis, Insights and Forecast - by End Use
7.3.1. Manufacturing
7.3.2. Consumer Goods
7.3.3. Retail
7.3.4. Food and Beverages
7.3.5. IT Hardware
7.3.6. Healthcare
7.3.7. Chemicals
7.3.8. Construction
7.3.9. Automotive
7.3.10. Telecom
7.3.11. Oil and Gas
7.3.12. Others
8. Kalimantan Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Model Type
8.1.1. 2PL
8.1.2. 3PL
8.1.3. 4PL
8.2. Market Analysis, Insights and Forecast - by Transportation Mode
8.2.1. Roadways
8.2.2. Seaways
8.2.3. Railways
8.2.4. Airways
8.3. Market Analysis, Insights and Forecast - by End Use
8.3.1. Manufacturing
8.3.2. Consumer Goods
8.3.3. Retail
8.3.4. Food and Beverages
8.3.5. IT Hardware
8.3.6. Healthcare
8.3.7. Chemicals
8.3.8. Construction
8.3.9. Automotive
8.3.10. Telecom
8.3.11. Oil and Gas
8.3.12. Others
9. Sulawesi Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Model Type
9.1.1. 2PL
9.1.2. 3PL
9.1.3. 4PL
9.2. Market Analysis, Insights and Forecast - by Transportation Mode
9.2.1. Roadways
9.2.2. Seaways
9.2.3. Railways
9.2.4. Airways
9.3. Market Analysis, Insights and Forecast - by End Use
9.3.1. Manufacturing
9.3.2. Consumer Goods
9.3.3. Retail
9.3.4. Food and Beverages
9.3.5. IT Hardware
9.3.6. Healthcare
9.3.7. Chemicals
9.3.8. Construction
9.3.9. Automotive
9.3.10. Telecom
9.3.11. Oil and Gas
9.3.12. Others
10. Others Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Model Type
10.1.1. 2PL
10.1.2. 3PL
10.1.3. 4PL
10.2. Market Analysis, Insights and Forecast - by Transportation Mode
10.2.1. Roadways
10.2.2. Seaways
10.2.3. Railways
10.2.4. Airways
10.3. Market Analysis, Insights and Forecast - by End Use
10.3.1. Manufacturing
10.3.2. Consumer Goods
10.3.3. Retail
10.3.4. Food and Beverages
10.3.5. IT Hardware
10.3.6. Healthcare
10.3.7. Chemicals
10.3.8. Construction
10.3.9. Automotive
10.3.10. Telecom
10.3.11. Oil and Gas
10.3.12. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. JNE
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Pos Indonesia
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Tiki
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. DHL
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. J&T Express
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. SiCepat
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Kuehne+Nagel
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. DSV A/S
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. FedEx
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Indonesian Logistics Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Java Indonesian Logistics Industry Revenue (Billion), by Model Type 2026 & 2034
Figure 3: Java Indonesian Logistics Industry Revenue Share (%), by Model Type 2026 & 2034
Figure 4: Java Indonesian Logistics Industry Revenue (Billion), by Transportation Mode 2026 & 2034
Figure 5: Java Indonesian Logistics Industry Revenue Share (%), by Transportation Mode 2026 & 2034
Figure 6: Java Indonesian Logistics Industry Revenue (Billion), by End Use 2026 & 2034
Figure 7: Java Indonesian Logistics Industry Revenue Share (%), by End Use 2026 & 2034
Figure 8: Java Indonesian Logistics Industry Revenue (Billion), by Country 2026 & 2034
Figure 9: Java Indonesian Logistics Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Sumatra Indonesian Logistics Industry Revenue (Billion), by Model Type 2026 & 2034
Figure 11: Sumatra Indonesian Logistics Industry Revenue Share (%), by Model Type 2026 & 2034
Figure 12: Sumatra Indonesian Logistics Industry Revenue (Billion), by Transportation Mode 2026 & 2034
Figure 13: Sumatra Indonesian Logistics Industry Revenue Share (%), by Transportation Mode 2026 & 2034
Figure 14: Sumatra Indonesian Logistics Industry Revenue (Billion), by End Use 2026 & 2034
Figure 15: Sumatra Indonesian Logistics Industry Revenue Share (%), by End Use 2026 & 2034
Figure 16: Sumatra Indonesian Logistics Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Sumatra Indonesian Logistics Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Kalimantan Indonesian Logistics Industry Revenue (Billion), by Model Type 2026 & 2034
Figure 19: Kalimantan Indonesian Logistics Industry Revenue Share (%), by Model Type 2026 & 2034
Figure 20: Kalimantan Indonesian Logistics Industry Revenue (Billion), by Transportation Mode 2026 & 2034
Figure 21: Kalimantan Indonesian Logistics Industry Revenue Share (%), by Transportation Mode 2026 & 2034
Figure 22: Kalimantan Indonesian Logistics Industry Revenue (Billion), by End Use 2026 & 2034
Figure 23: Kalimantan Indonesian Logistics Industry Revenue Share (%), by End Use 2026 & 2034
Figure 24: Kalimantan Indonesian Logistics Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Kalimantan Indonesian Logistics Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Sulawesi Indonesian Logistics Industry Revenue (Billion), by Model Type 2026 & 2034
Figure 27: Sulawesi Indonesian Logistics Industry Revenue Share (%), by Model Type 2026 & 2034
Figure 28: Sulawesi Indonesian Logistics Industry Revenue (Billion), by Transportation Mode 2026 & 2034
Figure 29: Sulawesi Indonesian Logistics Industry Revenue Share (%), by Transportation Mode 2026 & 2034
Figure 30: Sulawesi Indonesian Logistics Industry Revenue (Billion), by End Use 2026 & 2034
Figure 31: Sulawesi Indonesian Logistics Industry Revenue Share (%), by End Use 2026 & 2034
Figure 32: Sulawesi Indonesian Logistics Industry Revenue (Billion), by Country 2026 & 2034
Figure 33: Sulawesi Indonesian Logistics Industry Revenue Share (%), by Country 2026 & 2034
Figure 34: Others Indonesian Logistics Industry Revenue (Billion), by Model Type 2026 & 2034
Figure 35: Others Indonesian Logistics Industry Revenue Share (%), by Model Type 2026 & 2034
Figure 36: Others Indonesian Logistics Industry Revenue (Billion), by Transportation Mode 2026 & 2034
Figure 37: Others Indonesian Logistics Industry Revenue Share (%), by Transportation Mode 2026 & 2034
Figure 38: Others Indonesian Logistics Industry Revenue (Billion), by End Use 2026 & 2034
Figure 39: Others Indonesian Logistics Industry Revenue Share (%), by End Use 2026 & 2034
Figure 40: Others Indonesian Logistics Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: Others Indonesian Logistics Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Indonesian Logistics Industry Revenue Billion Forecast, by Model Type 2020 & 2034
Table 2: Global Indonesian Logistics Industry Revenue Billion Forecast, by Transportation Mode 2020 & 2034
Table 3: Global Indonesian Logistics Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 4: Global Indonesian Logistics Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Java Indonesian Logistics Industry Revenue Billion Forecast, by Model Type 2020 & 2034
Table 6: Java Indonesian Logistics Industry Revenue Billion Forecast, by Transportation Mode 2020 & 2034
Table 7: Java Indonesian Logistics Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 8: Java Indonesian Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Sumatra Indonesian Logistics Industry Revenue Billion Forecast, by Model Type 2020 & 2034
Table 10: Sumatra Indonesian Logistics Industry Revenue Billion Forecast, by Transportation Mode 2020 & 2034
Table 11: Sumatra Indonesian Logistics Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 12: Sumatra Indonesian Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Kalimantan Indonesian Logistics Industry Revenue Billion Forecast, by Model Type 2020 & 2034
Table 14: Kalimantan Indonesian Logistics Industry Revenue Billion Forecast, by Transportation Mode 2020 & 2034
Table 15: Kalimantan Indonesian Logistics Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 16: Kalimantan Indonesian Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Sulawesi Indonesian Logistics Industry Revenue Billion Forecast, by Model Type 2020 & 2034
Table 18: Sulawesi Indonesian Logistics Industry Revenue Billion Forecast, by Transportation Mode 2020 & 2034
Table 19: Sulawesi Indonesian Logistics Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 20: Sulawesi Indonesian Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Others Indonesian Logistics Industry Revenue Billion Forecast, by Model Type 2020 & 2034
Table 22: Others Indonesian Logistics Industry Revenue Billion Forecast, by Transportation Mode 2020 & 2034
Table 23: Others Indonesian Logistics Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 24: Others Indonesian Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Papua Indonesian Logistics Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Lesser Sunda Islands Indonesian Logistics Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Maluku Indonesian Logistics Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the Indonesian logistics industry market?
The Indonesian logistics industry market was valued at USD 72.4 Billion in 2025 and is estimated at USD 77.4 Billion in 2026. It is projected to reach USD 132.2 Billion by 2034, growing at a CAGR of 6.91% from 2026 to 2034.
2Which segment dominates the Indonesian logistics market by transportation mode?
Roadways account for the largest share, handling over 70% of intra-island distribution. Sea freight remains critical for inter-island shipping across the archipelago, while air freight serves time-sensitive and high-value cargo.
3Who are the major players in the Indonesian logistics industry?
Key players include JNE, Pos Indonesia, Tiki, DHL, J&T Express, and SiCepat, alongside global integrators such as Kuehne+Nagel, DSV A/S, and FedEx. These companies are investing in network expansion, technology, and sustainability initiatives.
4Which region holds the largest share of the Indonesian logistics market?
Java dominates with approximately 58% of the market, driven by its industrial concentration, population density, and infrastructure development. Sumatra follows with about 21% share, while Kalimantan, Sulawesi, and other islands account for the remainder.
5What are the key challenges facing the Indonesian logistics industry?
Major challenges include archipelagic geography and infrastructure gaps in Eastern Indonesia, a shortage of skilled logistics professionals, regulatory complexity, and fuel price volatility. These factors increase operational costs and constrain efficiency, particularly in remote regions.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary research methodology relies on a 70-80% primary research component, involving direct engagement with industry stakeholders across the Indonesian logistics value chain. We conduct in-depth interviews with C-suite executives, logistics managers, and supply chain directors from third-party logistics providers (3PLs), freight forwarders, e-commerce fulfillment operators, and large shippers.
Primary research participants include fleet operators and trucking company owners, warehouse and distribution center managers, customs brokers and freight forwarding specialists, and technology platform providers offering TMS, WMS, and digital freight matching solutions.
We interview a minimum of 120 senior stakeholders per report cycle, including titles such as Chief Supply Chain Officer, Logistics Director, Head of Fleet Operations, and Procurement Manager. These interviews provide granular insights into market volumes, pricing trends, technology adoption, and strategic pain points.
Primary research is complemented by on-site facility visits to ports, warehouses, and logistics hubs in Java, Sumatra, and Sulawesi to observe operations and validate data.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Supply Chain Officer
30%
Logistics Director
35%
Head of Fleet Operations
20%
Procurement Manager
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
3PL and Freight Forwarding Providers
35%
E-commerce Fulfillment and Last-Mile Operators
25%
Fleet and Trucking Companies
20%
Warehousing and Distribution Center Operators
12%
Logistics Technology Platform Providers
8%
Secondary Research & Industry Benchmarking
20-30% of our research draws from rigorous secondary analysis of official trade statistics, regulatory filings, and industry benchmarks. We source data exclusively from multilateral institutions and government bodies, including UN Comtrade, World Bank Logistics Performance Index, WTO trade databases, and Indonesia's Central Bureau of Statistics (BPS).
We consult official publications from the Indonesian Ministry of Transportation, the National Logistics Agency (Bulog), and the Indonesia Investment Coordinating Board (BKPM) to validate market sizing and regulatory frameworks.
Industry associations such as the Indonesian Logistics Association (ALI) and the ASEAN Federation of Forwarders Associations (AFFA) provide critical benchmarking data on service standards, cost structures, and capacity utilization.
Financial data is validated using standard databases including Bloomberg, Factiva, Hoovers, and PitchBook, ensuring robust financial modeling and competitive intelligence.
Every report is updated to the date of purchase, incorporating the latest regulatory changes, market developments, and trade flows.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously to triangulate market size and forecast. The bottom-up approach builds market estimates from granular operational data, including freight tonnage by mode, warehouse throughput volume, parcel shipment volumes, and logistics spend as a percentage of GDP.
Our models integrate specific quantitative metrics: container port traffic (TEU), fuel consumption per kilometer for road freight, average warehousing cost per square meter, and e-commerce parcel volume growth rates. These metrics are cross-validated through primary interviews and official statistics.
The top-down approach validates these bottom-up estimates against national accounts data, industry value-added figures, and macroeconomic indicators such as GDP growth and manufacturing output.
Multi-level data triangulation ensures convergence between supply-side and demand-side estimates, with discrepancies resolved through expert re-interviews and sensitivity analysis.
Data Accuracy & Quality Check
Our proprietary quality assurance framework guarantees an estimated data accuracy level of 85-90% across all market metrics. This is achieved through rigorous source verification, cross-referencing, and statistical validation.
Every data point undergoes three-tier validation: (1) primary interview corroboration, (2) comparison with official government statistics, and (3) consistency checks against historical trends and industry benchmarks.
We conduct post-estimation sensitivity analysis to assess the impact of key variables (fuel prices, regulatory changes, infrastructure delays) on market forecasts, providing clients with scenario-based projections.
Final data sets are reviewed by our internal expert panel, comprising senior analysts with domain expertise in Indonesian trade and logistics, ensuring analytical rigor and practical relevance.