1What is the size of the India vegetable seeds market?
The India vegetable seeds market was valued at USD 740.70 million in 2025 and is projected to reach USD 970.00 million by 2030, growing at a CAGR of 5.54%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 India Vegetable Seeds Market
 by Breeding Technology (Hybrids, Open-Pollinated Varieties and Hybrid Derivatives), by Cultivation Mechanism (Open-Field, Protected Cultivation), by Crop Family (Brassicas, Cucurbits, Solanaceae, Roots & Bulbs, Unclassified Vegetables), by State (Bihar, Chhattisgarh, Tamil Nadu, Maharashtra, Uttar Pradesh, Punjab, Haryana, Gujarat, Karnataka, West Bengal), by North (Punjab, Haryana, Uttar Pradesh), by South (Tamil Nadu, Karnataka, Telangana), by East (Bihar, West Bengal, Odisha), by West (Maharashtra, Gujarat, Rajasthan), by Central (Madhya Pradesh, Chhattisgarh) Forecast 2026-2034

Research Associate

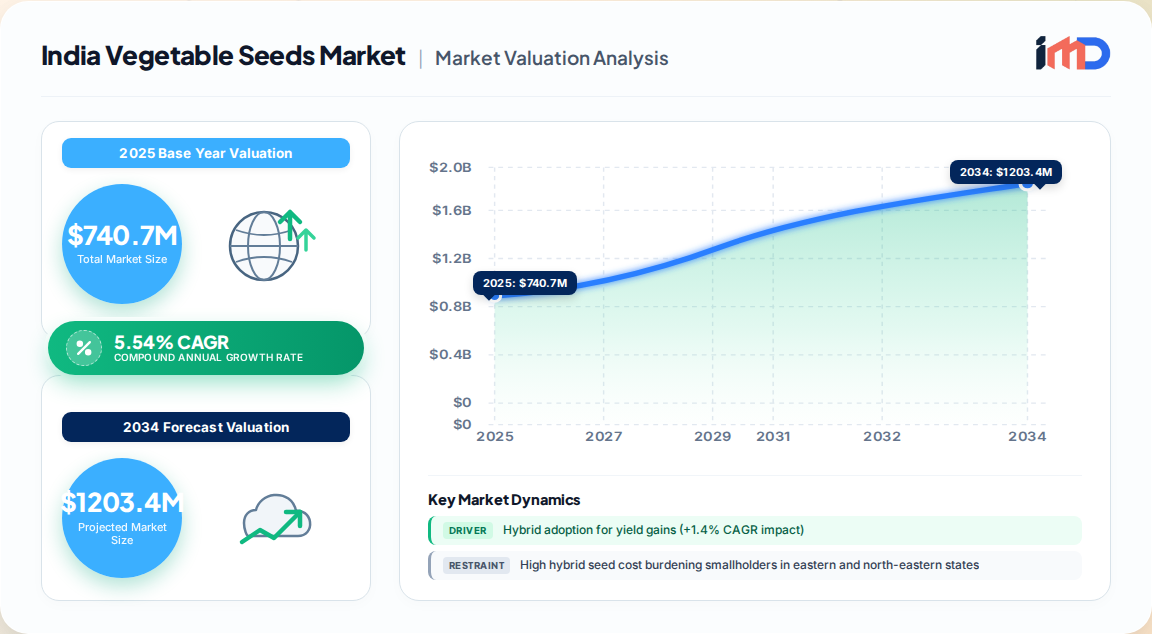
The India vegetable seeds market stands at USD 740.70 million in 2025 and is projected to reach USD 970.00 million by 2030, expanding at a 5.54% CAGR over the forecast window. This trajectory reflects a structural shift in Indian horticulture: farmers are transitioning decisively from farm-saved germplasm toward commercially bred cultivars engineered for yield, disease tolerance, and uniformity.
Unlike the grain seed sector, vegetable seed demand is highly fragmented and crop-specific, driven by over 60 commercially cultivated vegetable species across more than 28 states. Market concentration is low; the top five participants account for only a modest share of recorded revenue, creating ample headroom for regional specialists, biotechnology start-ups, and public-private breeding consortia.
Key market metrics (2025 baseline):
| Metric | Value |
|---|---|
| Market value (2025) | USD 740.70 million |
| Forecast value (2030) | USD 970.00 million |
| CAGR (2025–2030) | 5.54% |
| Hybrid seed revenue share (2024) | 79.4% |
| Open-field cultivation share (2024) | 99.5% |
| Leading state (revenue share, 2024) | Bihar (13.5%) |
| Fastest-growing state | Tamil Nadu (7.3% CAGR) |
Our proprietary demand modelling indicates that value growth will outpace volume growth, as hybrid penetration shifts the crop mix toward higher-priced, trait-differentiated products.
| Restraint | Estimated CAGR Impact | Geographic Hotspot |
|---|---|---|
| High hybrid seed cost for smallholders | −1.1% | Eastern and north-eastern states |
| Counterfeit and low-quality seed prevalence | −0.8% | Unorganised retail channels nationwide |
| Pollinator decline in seed-production hubs | −0.5% | Karnataka and neighbouring belts |
Counterfeit seed remains the most corrosive integrity risk. Growers purchasing spurious lots absorb losses beyond the original input price, eroding trust in commercial genetics. Investments in digital traceability, QR-coded packaging, and stricter enforcement are progressively restoring confidence. Additionally, the high upfront cost of hybrid seed creates a persistent affordability gap for marginal holdings below one hectare, which dominate the eastern states.
By breeding technology, hybrids commanded 79.4% of revenue in 2024. Open-pollinated varieties and hybrid derivatives are forecast to expand at 5.7% CAGR to 2030, sustained by open-pollinated demand among subsistence-oriented growers and public-sector breeding releases.
By cultivation mechanism, open-field systems accounted for 99.5% of the market in 2024, yet protected cultivation is the fastest-growing channel at 11.1% CAGR. The commercial significance of protected cultivation far exceeds its volume share, as per-hectare seed expenditure in controlled environments runs several multiples higher than open-field norms.
By crop family, unclassified vegetables led with 34.2% of 2024 revenue, reflecting the enormous diversity of indigenous and minor crops. Solanaceae — tomato, chilli, capsicum, and brinjal — is forecast to post the fastest 6.7% CAGR through 2030, supported by high commercial value, protected-cultivation suitability, and strong processing demand.
| Segment Dimension | Leading Segment (2024) | Share | Fastest Growth Segment | CAGR |
|---|---|---|---|---|
| Breeding technology | Hybrids | 79.4% | OPVs & hybrid derivatives | 5.7% |
| Cultivation mechanism | Open field | 99.5% | Protected cultivation | 11.1% |
| Crop family | Unclassified vegetables | 34.2% | Solanaceae | 6.7% |
| State | Bihar | 13.5% | Tamil Nadu | 7.3% |
India's vegetable seed demand is profoundly state-disaggregated, shaped by agro-climatic suitability and cropping intensity.
Our investment attractiveness assessment ranks Tamil Nadu, Maharashtra, and Karnataka as priority deployment markets for protected-cultivation seed portfolios, while Bihar, Uttar Pradesh, and West Bengal offer the largest open-field volume opportunities.
India remains a net exporter of vegetable seed, with a small but growing trade in hybrid vegetable seed to South Asia, Africa, and the Middle East. Domestic breeding is largely self-sufficient across major crops; however, a structural import dependence persists for breeder and foundation seed of advanced proprietary hybrids, particularly elite parental lines in tomato, capsicum, and cucumber.
Supply dynamics are shaped by three realities:
Pollinator availability in Karnataka's seed-production hubs has emerged as a quiet supply risk requiring active colony management by multiplication contractors.
With low market concentration, the competitive field spans multinational genetics houses, large domestic seed enterprises, and a long tail of regional specialists. Leading participants include Syngenta Group, Mahyco Private Limited, UPL Limited (Advanta Seeds Limited), VNR Seeds Private Limited, and BASF SE.
Strategic activity centres on three vectors:
Recent industry developments:
The India vegetable seed value chain comprises six identifiable stages, each with distinct economics and risk profiles:
Margins concentrate at the breeding and processing ends; distribution remains fragmented and price-competitive. Digital traceability is the highest-leverage current intervention, directly addressing the counterfeit seed restraint that suppresses CAGR by an estimated 0.8 percentage points.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.54% from 2020-2034 |
| Segmentation |
|
By Crop Family
By State
| By Geography |
|
The India vegetable seeds market was valued at USD 740.70 million in 2025 and is projected to reach USD 970.00 million by 2030, growing at a CAGR of 5.54%.
Hybrids dominated by breeding technology with a 79.4% revenue share in 2024. Among crop families, unclassified vegetables led with 34.2%, while Solanaceae is forecast to grow fastest at a 6.7% CAGR.
Bihar led with a 13.5% revenue share in 2024, while Tamil Nadu is projected to grow fastest at a 7.3% CAGR through 2030, supported by protected cultivation clusters.
Leading participants include Syngenta Group, Mahyco Private Limited, UPL Limited (Advanta Seeds Limited), VNR Seeds Private Limited, and BASF SE, within a low-concentration competitive field.
Key drivers include rapid hybrid adoption for 25–40% yield gains, protected cultivation expansion at an 11.1% CAGR, e-commerce distribution, and government programmes such as the Clean Plant Programme.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CEO / Managing Director | 25% |
| Head of Breeding & Product Development | 30% |
| Sales & Channel Director | 27% |
| Procurement / Supply Chain Manager | 18% |
| Company Type | Representation (%) |
|---|---|
| Hybrid Vegetable Seed Breeders & Genetics Companies | 34% |
| Seed Multiplication Contractors | 18% |
| Seed Processing & Treatment Facilities | 14% |
| Distributors & Retail Dealer Networks | 22% |
| Protected-Cultivation Input Integrators | 12% |


Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
 Related Reports
