1What is the current size of the India packaging market?
The India packaging market is valued at USD 101.12 billion in 2025 and is expected to reach USD 169.73 billion by 2030, growing at a 10.73% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 India Packaging Market
 by Packaging Type (Plastic, Paper & Paperboard, Container Glass, Metal Cans), by Packaging Format (Flexible, Rigid), by End-Use Industry (Food, Beverage, Pharmaceuticals, Personal Care, Industrial, E-Commerce), by West (Maharashtra, Gujarat), by South (Tamil Nadu, Telangana, Andhra Pradesh), by North (Delhi-NCR, Punjab, Haryana), by East (West Bengal, Odisha, Bihar) Forecast 2026-2034
Research Associate

 Related Reports

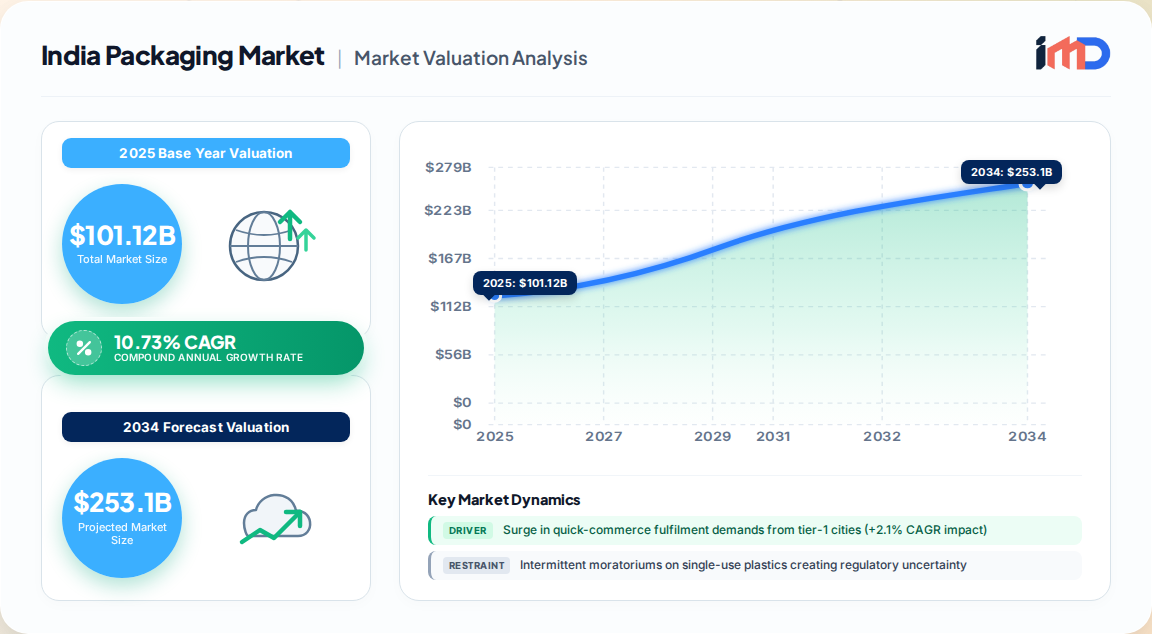
The India packaging market is valued at USD 101.12 billion in 2025 and is projected to reach USD 169.73 billion by 2030, expanding at a 10.73% CAGR. This growth is underpinned by a structural shift from commodity containers to technology-enabled, sustainable packaging solutions driven by regulatory mandates, e-commerce proliferation, and evolving consumer preferences.
| Driver | Impact on CAGR | Geographic Relevance | Timeline |
|---|---|---|---|
| Surge in quick-commerce fulfilment from tier-1 cities | +2.1% | Tier-1 cities, spillover to tier-2 | Short term (≤2 years) |
| Government EPR mandate for recycled content | +1.8% | National; early compliance in Maharashtra, Gujarat, Tamil Nadu | Medium term (2–4 years) |
| Rapid capacity addition in PET bottle-to-bottle recycling | +1.4% | Western and Southern manufacturing hubs | Medium term (2–4 years) |
| Record pharma export growth requiring sterile vials and ampoules | +1.5% | Hyderabad, Ahmedabad export clusters | Long term (≥4 years) |
| Ready-to-eat food penetration in rural markets | +1.2% | Rural North and Central India | Long term (≥4 years) |
| Rise of 100% compostable agro-residue mailers among D2C brands | +0.9% | Urban D2C concentration centers | Short term (≤2 years) |
The India packaging market is segmented by packaging type, format, end-use industry, and geography. Below is a detailed breakdown of key segments.
| Material | 2024 Share | Growth Outlook | Key Dynamics |
|---|---|---|---|
| Plastic | 42.12% | Moderate; shift to recycled content | EPR mandates require 30% recycled content in rigid plastics by 2025, rising to 60% by 2029. |
| Paper & Paperboard | ~20% | Fastest growing at 12.21% CAGR | Driven by sustainability preferences and e-commerce demand. |
| Container Glass | ~10% | Steady growth | Dominated by pharmaceutical and beverage applications. |
| Metal Cans | ~8% | Stable | Used in food, beverages, and aerosol packaging. |
India's packaging market exhibits distinct regional dynamics:
The India packaging market is highly fragmented, with a low market concentration. Key players include:
The market is witnessing consolidation, exemplified by PAG's USD 1.2 billion series of acquisitions in the paper sector. Private equity investments are accelerating automation, closed-loop recycling, and advanced analytics.
India's packaging trade is shaped by both imports and exports. Official trade data from the World Bank's WITS indicates that packaging requirements (A330) affect 10.12% of all products, with coverage ratios of 88.26% for food products and 99.48% for vegetable products, highlighting the regulatory intensity of packaging in agricultural and food supply chains.
Several high-potential opportunities emerge from our analysis:
Our research methodology for the India packaging market report is detailed below.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.73% from 2020-2034 |
| Segmentation |
|
By End-Use Industry
| By Geography |
|
The India packaging market is valued at USD 101.12 billion in 2025 and is expected to reach USD 169.73 billion by 2030, growing at a 10.73% CAGR.
Plastic is the dominant material, holding 42.12% of market share in 2024, followed by paper and paperboard. However, paperboard is the fastest-growing segment at 12.21% CAGR.
Key drivers include the surge in quick-commerce fulfilment (+2.1% CAGR impact), government EPR mandates (+1.8%), rapid capacity addition in PET bottle-to-bottle recycling (+1.4%), and record pharma export growth (+1.5%).
The food industry accounts for 48.54% of packaging market size (2024), driven by processed foods and ready-to-eat meals. E-commerce is the fastest-growing end-use segment at 15.1% CAGR.
Key players include Schott Poonawalla, Gerresheimer AG, AGI Glaspac (HSIL), PGP Glass (Piramal Glass), Hindustan National Glass & Industries (HNGIL), Amcor, Ball Corporation, Crown Holdings, Tetra Pak, and UFlex.
Western India leads due to pharma and recycling clusters, while Southern India shows strong growth from pharma exports and rPET investments. Northern India benefits from e-commerce, and Eastern India is an emerging market with rural consumption growth.
Sustainability is a major trend, with EPR mandates requiring 30% recycled content in rigid plastics by 2025 and 60% by 2029. This is driving investments in recycling infrastructure and compostable materials like agro-residue films.
Challenges include intermittent single-use plastic bans, volatile kraft paper prices (-0.8% CAGR impact), limited cold-chain infrastructure (-0.6%), and a fragmented converter base that limits scale and automation.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Directors | 30% |
| Plant Managers / Operations Heads | 25% |
| Sustainability Heads | 25% |
| Regulatory Affairs Specialists | 20% |
| Company Type | Representation (%) |
|---|---|
| Packaging Converters | 35% |
| Brand Owners / FMCG Companies | 30% |
| Raw Material Suppliers | 20% |
| Recycling & Waste Management Firms | 10% |
| Regulatory Bodies & Trade Associations | 5% |