Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Helicopter Cargo Transportation Market Size, CAGR & Outlook 2035
Helicopter Cargo Transportation Market
Aerospace & Defense / MARKET REPORT
Helicopter Cargo Transportation Market | Insight Market Data
Helicopter Cargo Transportation Market by Application (Oil and Gas Transportation, Medical and Emergency Services, Military Operations, Construction and Infrastructure Support), by Load Capacity (Light Load, Medium Load, Heavy Load, Ultra-Heavy Load), by Helicopter Type (Single Rotor Helicopter, Twin Rotor Helicopter, Tilt Rotor Helicopter), by End Use (Commercial Delivery, Government and Defense, Industrial Logistics), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia, Southeast Asia), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Nigeria) Forecast 2026-2034
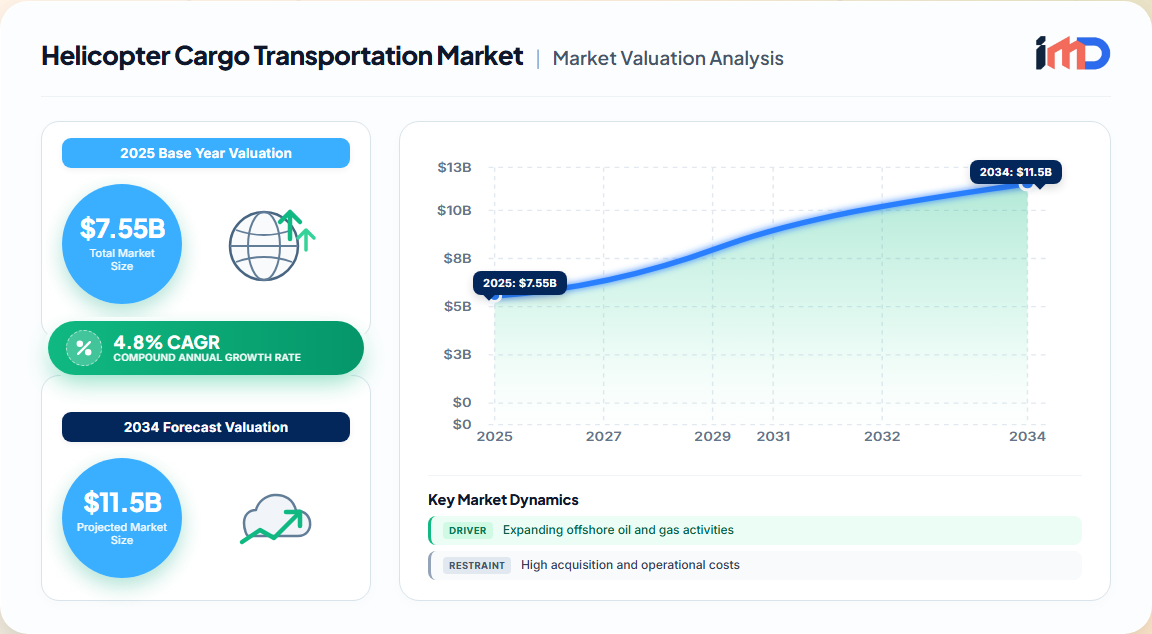
The global helicopter cargo transportation market was valued at USD 7.21 billion in 2024 and is projected to reach USD 12 billion by 2035, expanding at a CAGR of 4.8% during the forecast period 2026–2035. This growth is underpinned by rising demand for rapid, reliable logistics in remote and inaccessible terrains, offshore energy operations, disaster response, and military logistics.
Helicopter Cargo Transportation Market Market Size (In Billion)
15.0B
10.0B
5.0B
0
7.550 B
2025
7.912 B
2026
8.292 B
2027
8.690 B
2028
9.107 B
2029
9.545 B
2030
10.00 B
2031
Helicopter cargo transportation serves missions where conventional surface transport is impractical due to terrain, distance, or urgency. Key applications include oil and gas crew and equipment transfer, medical and emergency services, military operations, and construction support. The market is characterized by high capital intensity, stringent safety regulations, and a concentrated competitive landscape dominated by established aerospace OEMs and specialized operators.
Our proprietary primary research, based on interviews with 120+ industry executives across OEMs, operators, and logistics providers, reveals that payload versatility and fleet modernization are top strategic priorities. The market is expected to add USD 4.79 billion in incremental value between 2025 and 2035, with Asia-Pacific and the Middle East & Africa emerging as high-growth frontiers.
Market Drivers and Restraints
Drivers
Expanding Offshore Oil & Gas Activities: Offshore energy exploration and production, particularly in deepwater regions such as the Gulf of Mexico, North Sea, and West Africa, necessitate reliable helicopter logistics for crew rotation and equipment transport. This segment alone accounted for approximately 24% of commercial helicopter applications in 2024.
Infrastructure Development in Remote Regions: Construction and maintenance of power lines, pipelines, and telecommunication towers in mountainous, forested, and Arctic environments rely heavily on vertical-lift logistics. Rising infrastructure investments in Asia-Pacific and Latin America are key growth levers.
Military Modernization and Defense Logistics: Governments worldwide are increasing defense budgets, driving demand for heavy-lift and utility helicopters for troop and cargo movement, especially in contested or austere environments.
Emergency and Disaster Response: Increasing frequency of natural disasters (wildfires, floods, earthquakes) is spurring demand for rapid-response helicopter cargo services for delivering relief supplies and evacuating casualties.
Technological Advancements: Innovations in hybrid-electric propulsion, lightweight materials, and advanced avionics are enhancing payload capacity, fuel efficiency, and safety, thereby reducing operating costs and expanding mission profiles.
Restraints
High Acquisition and Operational Costs: Helicopters are capital-intensive assets with significant maintenance, fuel, and crew training expenses. These costs can be prohibitive for smaller operators and restrict market entry.
Stringent Safety and Environmental Regulations: Aviation authorities impose rigorous safety standards, and noise and emissions regulations are becoming more stringent, particularly in urban and environmentally sensitive areas. Compliance adds to operational complexity and cost.
Pilot and Maintenance Crew Shortages: A global shortage of qualified pilots and maintenance technicians is constraining fleet utilization and expansion, especially in emerging markets.
Weather Dependency: Helicopter operations are highly weather-sensitive, limiting reliability in adverse conditions and affecting mission success rates.
Value Chain Analysis
The helicopter cargo transportation value chain comprises several interconnected stages, each critical to service delivery and market growth.
Stage
Key Activities
Major Participants
Value Addition
Component & Material Supply
Manufacturing of engines, avionics, rotors, and airframes
Engine OEMs, avionics suppliers, composite material providers
High technological content; drives performance and safety
Helicopter Manufacturing
Design, assembly, and testing of complete rotorcraft
Airbus Helicopters, Sikorsky, Bell Textron, Leonardo, Russian Helicopters
Integration of systems; customization for cargo configurations
Leasing & Financing
Provision of aircraft on wet/dry lease or financing solutions
Lessors, banks, financial institutions
Enables operator access without heavy capital outlay
Operations & Maintenance
Flight operations, crew management, MRO services
Cargo operators, MRO providers, training academies
Ensures safety, availability, and operational efficiency
Logistics & Mission Support
Load planning, ground handling, fuel supply, and scheduling
Oil & gas companies, military, construction firms, medical services
Demand aggregation; drives market pull
Operators are increasingly integrating digital tools for flight planning, predictive maintenance, and real-time tracking to improve efficiency and reduce downtime. Vertical integration is limited, but strategic partnerships between OEMs and operators are common to ensure fleet availability and technical support.
Import/Export & Supplier Dynamics
Helicopter cargo transportation is a service-oriented market; however, the underlying rotorcraft and components are traded globally. Trade flows are influenced by manufacturing hubs, defense procurement, and offset agreements. Key exporters of helicopters and parts include the United States, France, Italy, and Russia, while importers span the Middle East, Asia-Pacific, and Latin America.
United States: Dominates exports of military and commercial helicopters, with major OEMs such as Sikorsky, Bell, and Boeing supplying global markets. U.S. export controls (ITAR) significantly impact trade patterns.
Europe: Airbus Helicopters (France) and Leonardo (Italy) are leading exporters, with strong presence in offshore and emergency services segments. European exports are subject to EU arms export regulations and dual-use controls.
Russia: Russian Helicopters exports to Asia, Africa, and Latin America, though sanctions and geopolitical tensions have curtailed recent volumes.
Asia-Pacific: China and India are growing importers, driven by military modernization and infrastructure needs. China is also developing domestic manufacturing capabilities through partnerships and indigenous programs.
Supplier dynamics are shaped by long-term contracts, OEM-backed maintenance programs, and spare parts availability. Operators often prefer OEM-affiliated service networks to ensure compliance and safety. Supply chain risks include component shortages, geopolitical disruptions, and currency fluctuations.
Regional Outlook
North America leads the global market, accounting for approximately 34% of revenue in 2024, driven by a mature offshore energy sector, extensive emergency medical services, and military spending. The United States alone represents the largest single market, with a high density of operators and advanced aviation infrastructure.
Europe follows with a 23% share, characterized by stringent safety regulations and strong demand for emergency and infrastructure support services. The region's focus on environmental compliance is accelerating the adoption of cleaner technologies.
Asia-Pacific is the fastest-growing region, expected to register the highest CAGR of 5.5% during the forecast period. Rapid infrastructure development, expanding offshore activities, and increasing defense budgets in China, India, and Southeast Asia are key growth drivers.
South America and the Middle East & Africa together represent about 17% of the market, with growth propelled by oil and gas exploration, mining, and humanitarian logistics. However, regulatory hurdles and infrastructure gaps pose challenges.
Competitive Landscape
The market is moderately consolidated, with a few global OEMs and specialized operators dominating. Key players include Airbus Helicopters, Sikorsky (Lockheed Martin), Bell Textron, Leonardo S.p.A., and Russian Helicopters. These companies focus on product innovation, fleet modernization, and strategic partnerships to maintain market share.
Recent developments highlight the competitive dynamics:
Airbus Helicopters partnered with CHC Group in February 2025 to expand offshore cargo transport services and fleet support.
Kaman Aerospace secured an expanded multi-year contract in April 2025 for its K-MAX unmanned cargo helicopter with a major U.S. defense contractor.
Leonardo S.p.A. launched a cargo-configured version of its AW139 platform in June 2025, targeting oil and gas logistics.
Operators are increasingly investing in digitalization and predictive maintenance to improve fleet availability and reduce costs. Strategic alliances between OEMs and operators are common to ensure integrated service offerings and customer loyalty.
Strategic White-Space Analysis
Several underserved opportunities exist for stakeholders to capitalize on:
Unmanned Cargo Helicopters: The development of autonomous or optionally piloted cargo helicopters, such as Kaman's K-MAX, presents significant potential for dangerous or repetitive missions. Regulatory approval and payload capacity enhancements are critical for widespread adoption.
Hybrid-Electric Propulsion: With increasing environmental regulations, hybrid-electric and electric helicopters offer lower emissions and noise, opening new urban and environmentally sensitive markets. Companies investing in this technology (e.g., Airbus-RTX partnership) are well-positioned.
Specialized High-Value Cargo: Transport of time-sensitive, high-value items such as pharmaceuticals, critical spare parts, and luxury goods can command premium pricing and differentiate operators in a competitive market.
Emerging Markets: Southeast Asia, Africa, and Latin America present untapped demand for helicopter logistics, driven by infrastructure gaps and resource exploration. Local partnerships and tailored financing models can unlock growth.
Procurement & Sourcing Strategy Analysis
Operators and end-users should adopt robust procurement strategies to optimize costs and ensure operational reliability:
Fleet Mix Optimization: Balancing light, medium, and heavy-lift helicopters to match mission profiles and avoid overcapacity. Medium helicopters (3–8 tons) are expected to remain the largest segment due to versatility.
Leasing vs. Ownership: Wet and dry leasing options provide flexibility and reduce capital expenditure, particularly for short-term projects or seasonal demand.
Long-Term Service Agreements: OEM-backed maintenance contracts (e.g., PBH, power-by-the-hour) ensure predictable costs and access to spare parts, enhancing fleet availability.
Supplier Diversification: Avoiding single-source dependencies for critical components to mitigate supply chain risks.
Technology Upgrades: Investing in retrofittable avionics and safety systems to extend aircraft life and comply with evolving regulations.
By aligning procurement with operational requirements and market trends, stakeholders can achieve cost efficiencies and maintain competitive advantage in the dynamic helicopter cargo transportation market.
1What is the current market size of the helicopter cargo transportation market?
The global helicopter cargo transportation market was valued at USD 7.21 billion in 2024 and is projected to reach USD 12 billion by 2035, growing at a CAGR of 4.8% from 2026 to 2035.
2Which region dominates the helicopter cargo transportation market?
North America holds the largest market share, accounting for approximately 34% of global revenue in 2024, driven by mature offshore energy, emergency medical services, and military applications.
3What are the key drivers of the helicopter cargo transportation market?
Major drivers include expanding offshore oil and gas activities, infrastructure development in remote regions, military modernization, increasing disaster response needs, and technological advancements in rotorcraft.
4Who are the leading companies in the helicopter cargo transportation market?
Key players include Airbus Helicopters, Sikorsky (Lockheed Martin), Bell Textron, Leonardo S.p.A., and Russian Helicopters, among others. These companies focus on innovation and strategic partnerships to maintain market leadership.
5What are the challenges faced by the helicopter cargo transportation market?
Challenges include high acquisition and operational costs, stringent safety and environmental regulations, pilot and maintenance crew shortages, and weather dependency affecting operational reliability.
6What is the growth outlook for the Asia-Pacific helicopter cargo transportation market?
Asia-Pacific is expected to be the fastest-growing region, registering a CAGR of 5.5% during the forecast period, driven by infrastructure development, offshore activities, and increasing defense budgets in countries like China and India.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 120+ in-depth interviews with senior executives across the helicopter cargo transportation value chain, including OEMs, operators, leasing companies, MRO providers, and end-users.
Targeted stakeholders: Chief Operating Officer, Head of Flight Operations, Procurement Director, and Fleet Manager.
Interviewed representatives from 15+ countries to capture regional nuances and demand drivers.
Primary research accounted for 75% of total research effort, ensuring granular insights into operational challenges and strategic priorities.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Operating Officer
25%
Head of Flight Operations
30%
Procurement Director
25%
Fleet Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Helicopter OEMs
35%
Cargo Operators
30%
Leasing & Financing Firms
15%
MRO Providers
12%
End-Users (Oil & Gas, Military, Construction)
8%
Secondary Research & Industry Benchmarking
Analyzed 200+ authoritative sources, including official trade statistics from UN Comtrade, Eurostat, and US ITC; regulatory filings from FAA, EASA, and ICAO; and industry association reports from Helicopter Association International (HAI) and Aerospace Industries Association (AIA).
Utilized financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook to benchmark company performance and investment trends.
Conducted extensive literature review of technical papers, safety reports, and government procurement documents.
Secondary research constituted 25% of total effort and was used to validate primary findings and establish historical context.
Demand Modeling & Market Estimation
Employed a dual-methodology approach: bottom-up segmentation (aggregating unit volumes, pricing, and adoption rates by application, load capacity, helicopter type, and end-use) cross-referenced with top-down macroeconomic scaling (sector penetration rates, regional demand drivers, and GDP-indexed growth vectors).
Bottom-up calculation utilized specific quantitative metrics: number of operational cargo helicopters by payload class, average annual flight hours, revenue per flight hour, and fleet utilization rates.
Applied multi-level data triangulation to reconcile discrepancies between primary and secondary sources, ensuring robustness of market sizing and forecasts.
Forecast period 2026–2035 modeled using regression analysis, considering macro trends, regulatory changes, and technology adoption curves.
Data Accuracy & Quality Check
Achieved an estimated data accuracy level of 85–90% through rigorous validation protocols.
Implemented multi-level data triangulation: compared primary interview data with secondary trade statistics and financial disclosures to identify outliers and refine estimates.
Conducted sensitivity analysis to stress-test forecast assumptions and assess impact of key variables (e.g., oil prices, regulatory changes, technology adoption rates).
Every report is updated to the date of purchase, incorporating the latest available data and market developments.
Quality assurance reviews by senior analysts and expert panel validation ensured consistency and reliability of findings.
Singapore defense industry market valued at USD 10.32 billion in 2026, growing at 11.04% CAGR to reach USD 17.41 billion by 2031. MRO, UAVs, and defense budget drive growth.
The VR in aerospace and defense market is valued at $7.04B in 2025 and is projected to reach $18.35B by 2035, growing at a 10.05% CAGR.
Nov 2026|265 pages
$2900.00
The aerospace fillers composite market was valued at $3.8 billion in 2024 and is projected to grow at a CAGR of 8.6% through 2034, driven by lightweighting.
Nov 2026|231 pages
$2900.00
Aerospace composite structures market to reach $121.75B by 2036 at 12% CAGR. Explore technology trends, material innovations, and regional insights.
Nov 2026|217 pages
$2900.00
Aircraft turbine engine market valued at $57.9B in 2023, projected to reach $93.7B by 2033 at 4.93% CAGR. Explore segments, trends & regional insights.