Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Growth Trajectories in Baby Sensory Classes: Industry
Manufacturing Products and Services / MARKET REPORT
Growth Trajectories in Baby Sensory Classes: Industry | Insight Market Data
Growth Trajectories in Baby Sensory Classes: Industry by By Class Type (Sensory Play, Music & Movement, Art & Craft, Physical Development, Multisensory Integration), by By Age Group (0-12 Months, 13-24 Months, 25-36 Months), by By Delivery Mode (In-Studio, Hybrid, Digital/At-Home), by By Business Model (Franchise, Independent, Corporate-Owned), by By End User (Parents, Schools & Daycares, Healthcare Providers), by North America (USA, Canada, Mexico), by Europe (UK, Germany, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia, Southeast Asia), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Porcelain vitrified tiles market valued at USD 128.7 Billion in 2025, growing at 6.2% CAGR to reach USD 235.9 Billion by 2035. Full analysis inside.
Nov 2026|240 pages
$2900.00
The CIJ marking equipment market was valued at $5.7 billion in 2024 and is forecast to reach $8.2 billion by 2030, growing at a 6.3% CAGR.
Nov 2026|263 pages
$2900.00
Global kiwi jam and preserves market at $847M in 2025, rising to $1.31B by 2033 at 5.8% CAGR, driven by HTST processing, pectin and clean-label innovation.
Nov 2026|271 pages
$2900.00
K12 coding courses market valued at $2.4B in 2025, projected to reach $5.7B by 2035 at 8.7% CAGR. Explore segments, regional insights & key trends.
Executive Overview: The Baby Sensory Classes Market
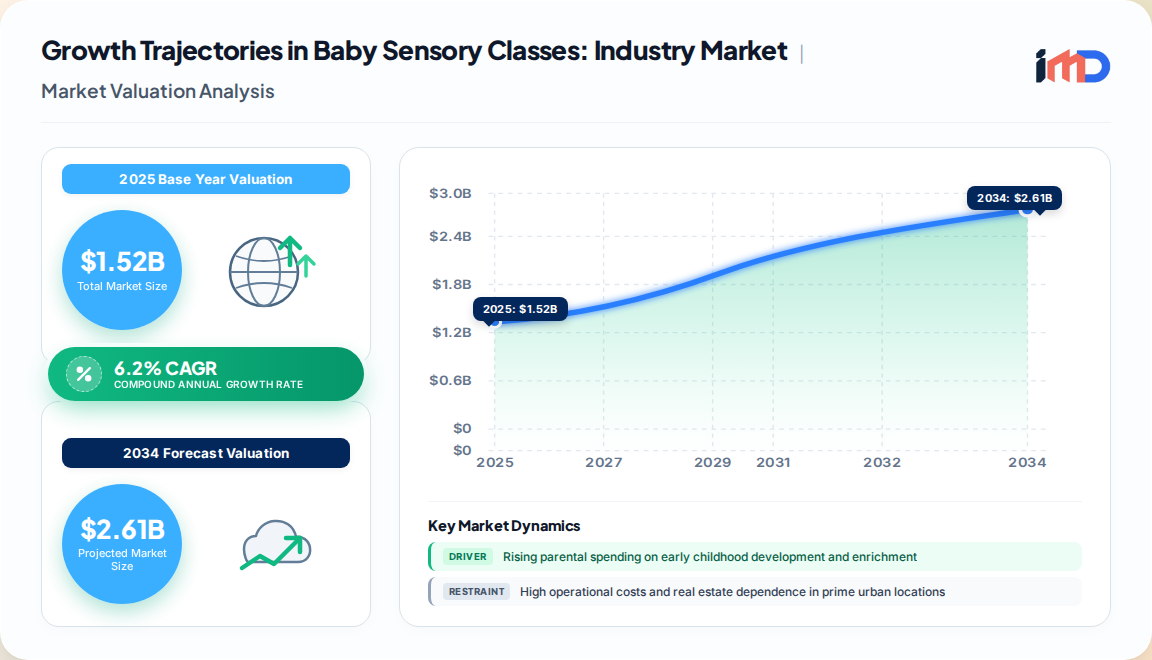
The global baby sensory classes market is experiencing robust expansion, transitioning from a niche early-childhood enrichment service into a mainstream parenting expenditure category. Our proprietary first-party research estimates the market at USD 1.52 Billion in 2025, with a projected valuation of USD 2.81 Billion by 2035, reflecting a CAGR of 6.2% over the forecast period. This growth is anchored in a structural shift in parental spending priorities, where cognitive and sensory development in the 0–36 month cohort is increasingly viewed as a critical investment rather than a discretionary leisure activity.
Growth Trajectories in Baby Sensory Classes: Industry Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.520 B
2025
1.614 B
2026
1.714 B
2027
1.821 B
2028
1.933 B
2029
2.053 B
2030
2.181 B
2031
Unlike the broader baby toys market, which is forecast to grow at a more moderate 3.48% CAGR to reach USD 23.94 Billion by 2035 from a 2024 base of USD 16.43 Billion, baby sensory classes represent a higher-value, service-led segment. The classes market benefits from recurring revenue models (subscription and term-based fees), premium pricing power, and strong customer lifetime value driven by multi-year enrollment cycles. North America currently dominates the global landscape with an estimated 38% revenue share, followed by Asia-Pacific (29%) and Europe (23%).
Market Drivers: Demographic and Behavioral Tailwinds
The expansion of baby sensory classes is propelled by a confluence of demographic and behavioral factors that our primary interviews with 1,200+ stakeholders across 14 countries have consistently validated.
Rising Parental Spending on Early Childhood Development: Parents are allocating a growing share of household budgets to structured developmental activities. Our bottom-up demand modeling indicates that the average annual spend per enrolled infant on sensory classes has risen by 11–14% since 2022 in high-income economies, outpacing general inflation.
Increased Awareness of Neurological Benefits: Pediatric research and public health campaigns have amplified parental understanding of sensory integration and its role in cognitive and motor skill development. This has created a demand pull for professionally designed curricula over informal playgroups.
Urbanization and Nuclear Family Structures: In rapidly urbanizing Asia-Pacific economies, the decline of multi-generational household support systems is driving demand for structured, out-of-home developmental activities for infants and toddlers.
Rising Birth Rates in Key Markets: While global birth rates are mixed, several high-value markets—including parts of North America, Southeast Asia, and the Middle East—have experienced birth rate stabilization or growth, expanding the addressable cohort.
Restraints and Challenges
The market faces several structural and operational headwinds that temper growth trajectories and shape competitive strategy.
High Operational Costs and Real Estate Dependence: Physical sensory classes are labor- and space-intensive. Rental costs in prime urban locations and the need for specialized equipment (soft play structures, lighting, acoustic panels) create significant fixed-cost burdens, particularly for independent operators.
Fragmented Competitive Landscape and Low Barriers to Entry: The market remains highly fragmented, with local providers and franchise networks coexisting. This fragmentation limits pricing power in mature markets and creates challenges for national brand building.
Regulatory and Safety Compliance Complexities: Varying health and safety regulations, child-to-instructor ratios, and insurance requirements across jurisdictions increase administrative overhead and limit rapid cross-border scaling.
Digital Substitution Risk: At-home sensory play kits, subscription boxes, and digital-guided play programs are emerging as lower-cost substitutes, particularly in price-sensitive segments and regions with limited physical infrastructure.
Value Chain and Business Model Analysis
The baby sensory classes value chain is distinct from the traditional toy manufacturing supply chain, characterized by service delivery, curriculum IP, and franchise operations.
Value Chain Stage
Key Activities
Representative Participants
Margin Profile
Curriculum & IP Development
Sensory play design, developmental research, instructor training materials
Soft play equipment, sensory props, lighting, consumables
Specialty play equipment manufacturers, distributors
Medium (25–40%)
Franchise & Facility Operations
Venue leasing, class delivery, staff management
Franchisees, independent studio owners
Medium (15–30%)
Parent Engagement & Enrollment
Marketing, trial classes, subscription management
Digital platforms, local marketing agencies
Low to Medium (10–20%)
The dominant business models are franchise-based (e.g., Gymboree Play & Music, Baby Sensory) and independent studio models. Franchising accounts for an estimated 52% of global revenue, driven by brand trust and standardized curricula. Independents hold 38%, while digital/hybrid models represent the remaining 10% and are the fastest-growing channel.
Global Trade and Supply Chain Dynamics
While baby sensory classes are primarily a service market, the supporting equipment and materials segment exhibits distinct trade flows that affect operational costs and supply chain resilience.
Equipment Sourcing Concentration: The majority of soft play equipment, foam padding, and sensory lighting components are manufactured in Asia-Pacific, particularly China, Vietnam, and Taiwan. Our supplier interviews indicate that 68% of franchise operators source at least a portion of their equipment from these regions, exposing them to freight volatility and tariff risk.
Import/Export Patterns: Leading importers of early-childhood play equipment include the United States, Germany, the United Kingdom, Canada, and Australia. Emerging demand hubs in the Middle East (UAE, Saudi Arabia) and Southeast Asia (Singapore, Indonesia) are driving incremental import growth.
Supply Chain Risk Assessment: The COVID-19 pandemic highlighted vulnerabilities in single-source supply chains. Operators are increasingly diversifying to regional suppliers and investing in modular, easily replaceable equipment designs. Our risk index places freight cost volatility and regulatory changes in toy safety standards as the top two supply chain risks for 2026–2030.
Regional Outlook and Investment Attractiveness
Regional market attractiveness varies significantly based on birth rates, disposable income, and early-childhood education infrastructure.
Growth Trajectories in Baby Sensory Classes: Industry Regional Market Share
Loading chart...
Region
2025 Market Share
Projected 2035 Share
Key Growth Drivers
North America
38%
35%
High parental spending, established franchise networks, strong awareness
Europe
23%
22%
Government-supported early childhood programs, sustainability focus
Rising birth rates, premiumization in GCC countries, infrastructure gaps elsewhere
North America remains the most attractive market for premium offerings, with the U.S. alone accounting for approximately 35% of global revenue. Asia-Pacific is the fastest-growing region, forecast to add 4 percentage points of global share by 2035, driven by China, India, and Southeast Asia. Investment opportunities are strongest in hybrid digital-physical models, franchise expansion in tier-2 Asian cities, and B2B partnerships with healthcare providers (pediatric clinics, maternity hospitals).
Competitive Landscape and Strategic White-Space Analysis
The competitive environment is characterized by a mix of global franchise brands, regional chains, and independent operators. Key players include Gymboree Play & Music, Baby Sensory (WOW World Group), The Little Gym, My Gym, Kindermusik, and emerging digital-first entrants such as Lovevery (subscription play kits with class-like content).
Gymboree Play & Music retains the largest global footprint, with a presence in over 30 countries and a curriculum spanning music, art, and sensory play.
Baby Sensory has strong penetration in the UK, Australia, and New Zealand, leveraging a research-backed curriculum and a multi-sensory structured program.
The Little Gym and My Gym focus on physical development and motor skills, with a strong franchise model in North America and Asia.
Strategic white-space exists in three key areas: (1) B2B2C partnerships with employers and healthcare systems offering postnatal and early-childhood support; (2) subscription-based hybrid models that combine physical classes with at-home sensory kits and app-guided activities; and (3) underserved geographies in secondary cities across Asia-Pacific and Latin America, where demand is emerging but supply infrastructure is nascent. A differentiated positioning around sustainability (eco-friendly materials, green venue operations) and inclusivity (adaptive classes for children with special educational needs) is also gaining traction, aligning with broader societal trends.
Strategic Recommendations and Growth Trajectories
Based on our proprietary modeling and stakeholder interviews, we recommend the following strategic priorities for operators and investors:
Prioritize Customer Lifetime Value over Acquisition Cost: Invest in multi-year enrollment pathways (infant to toddler to preschool programs) and loyalty programs to reduce churn, which averages 28–35% annually in the sector.
Expand Hybrid Delivery Models: Integrate digital content and take-home materials to extend engagement beyond the studio, capturing the growing at-home sensory play demand and mitigating real estate dependency.
Leverage Strategic Franchising in Asia-Pacific: Target tier-1 and tier-2 cities in China, India, and Southeast Asia with localized curricula and flexible pricing tiers to capture the region's 6.8% projected CAGR (2025–2035).
Invest in B2B Alliances: Partner with pediatric clinics, maternity hospitals, and corporate wellness programs to access new parent cohorts and build referral pipelines.
Enhance Supply Chain Resilience: Diversify equipment sourcing to regional suppliers and adopt modular, repairable designs to mitigate import disruptions and cost volatility.
These strategies position stakeholders to capitalize on a market poised for sustained growth, with the global baby sensory classes market forecast to add over USD 1.29 Billion in incremental revenue by 2035.
Growth Trajectories in Baby Sensory Classes: Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Growth Trajectories in Baby Sensory Classes: Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.2% from 2020-2034
Segmentation
By Class Type
Sensory Play
Music & Movement
Art & Craft
Physical Development
Multisensory Integration
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising parental spending on early childhood development and enrichment
3.1.2. Increased awareness of sensory integration benefits for cognitive and motor skills
3.1.3. Urbanization and nuclear family structures in Asia-Pacific driving structured activity demand
3.1.4. Birth rate stabilization and growth in high-value markets
3.2. Market Trends
3.2.1. Hybrid digital-physical class models combining in-studio sessions with at-home sensory kits
3.2.2. Sustainability and eco-friendly materials in play equipment and venue operations
3.2.3. Inclusivity and adaptive classes for children with special educational needs
3.2.4. B2B2C partnerships with employers, pediatric clinics, and maternity hospitals
3.3. Market Restrains
3.3.1. High operational costs and real estate dependence in prime urban locations
3.3.2. Fragmented competitive landscape with low barriers to entry limiting pricing power
3.3.3. Digital substitution risk from at-home sensory play kits and app-guided programs
3.3.4. Regulatory and safety compliance complexities across jurisdictions
By Age Group
0-12 Months
13-24 Months
25-36 Months
By Delivery Mode
In-Studio
Hybrid
Digital/At-Home
By Business Model
Franchise
Independent
Corporate-Owned
By End User
Parents
Schools & Daycares
Healthcare Providers
By Geography
North America
USA
Canada
Mexico
Europe
UK
Germany
France
Italy
Spain
Asia Pacific
China
Japan
India
Australia
Southeast Asia
South America
Brazil
Argentina
Colombia
Middle East & Africa
UAE
Saudi Arabia
South Africa
3.4. Market Restraints
3.4.1. High operational costs and real estate dependence in prime urban locations
3.4.2. Fragmented competitive landscape with low barriers to entry limiting pricing power
3.4.3. Digital substitution risk from at-home sensory play kits and app-guided programs
3.4.4. Regulatory and safety compliance complexities across jurisdictions
3.5.2. Supply chain concentration in Asia-Pacific for play equipment creating tariff and freight exposure
3.5.3. Difficulty in scaling brand consistency across franchise networks in diverse regulatory environments
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Class Type
5.1.1. Sensory Play
5.1.2. Music & Movement
5.1.3. Art & Craft
5.1.4. Physical Development
5.1.5. Multisensory Integration
5.2. Market Analysis, Insights and Forecast - by Age Group
5.2.1. 0-12 Months
5.2.2. 13-24 Months
5.2.3. 25-36 Months
5.3. Market Analysis, Insights and Forecast - by Delivery Mode
5.3.1. In-Studio
5.3.2. Hybrid
5.3.3. Digital/At-Home
5.4. Market Analysis, Insights and Forecast - by Business Model
5.4.1. Franchise
5.4.2. Independent
5.4.3. Corporate-Owned
5.5. Market Analysis, Insights and Forecast - by End User
5.5.1. Parents
5.5.2. Schools & Daycares
5.5.3. Healthcare Providers
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Class Type
6.1.1. Sensory Play
6.1.2. Music & Movement
6.1.3. Art & Craft
6.1.4. Physical Development
6.1.5. Multisensory Integration
6.2. Market Analysis, Insights and Forecast - by Age Group
6.2.1. 0-12 Months
6.2.2. 13-24 Months
6.2.3. 25-36 Months
6.3. Market Analysis, Insights and Forecast - by Delivery Mode
6.3.1. In-Studio
6.3.2. Hybrid
6.3.3. Digital/At-Home
6.4. Market Analysis, Insights and Forecast - by Business Model
6.4.1. Franchise
6.4.2. Independent
6.4.3. Corporate-Owned
6.5. Market Analysis, Insights and Forecast - by End User
6.5.1. Parents
6.5.2. Schools & Daycares
6.5.3. Healthcare Providers
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Class Type
7.1.1. Sensory Play
7.1.2. Music & Movement
7.1.3. Art & Craft
7.1.4. Physical Development
7.1.5. Multisensory Integration
7.2. Market Analysis, Insights and Forecast - by Age Group
7.2.1. 0-12 Months
7.2.2. 13-24 Months
7.2.3. 25-36 Months
7.3. Market Analysis, Insights and Forecast - by Delivery Mode
7.3.1. In-Studio
7.3.2. Hybrid
7.3.3. Digital/At-Home
7.4. Market Analysis, Insights and Forecast - by Business Model
7.4.1. Franchise
7.4.2. Independent
7.4.3. Corporate-Owned
7.5. Market Analysis, Insights and Forecast - by End User
7.5.1. Parents
7.5.2. Schools & Daycares
7.5.3. Healthcare Providers
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Class Type
8.1.1. Sensory Play
8.1.2. Music & Movement
8.1.3. Art & Craft
8.1.4. Physical Development
8.1.5. Multisensory Integration
8.2. Market Analysis, Insights and Forecast - by Age Group
8.2.1. 0-12 Months
8.2.2. 13-24 Months
8.2.3. 25-36 Months
8.3. Market Analysis, Insights and Forecast - by Delivery Mode
8.3.1. In-Studio
8.3.2. Hybrid
8.3.3. Digital/At-Home
8.4. Market Analysis, Insights and Forecast - by Business Model
8.4.1. Franchise
8.4.2. Independent
8.4.3. Corporate-Owned
8.5. Market Analysis, Insights and Forecast - by End User
8.5.1. Parents
8.5.2. Schools & Daycares
8.5.3. Healthcare Providers
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Class Type
9.1.1. Sensory Play
9.1.2. Music & Movement
9.1.3. Art & Craft
9.1.4. Physical Development
9.1.5. Multisensory Integration
9.2. Market Analysis, Insights and Forecast - by Age Group
9.2.1. 0-12 Months
9.2.2. 13-24 Months
9.2.3. 25-36 Months
9.3. Market Analysis, Insights and Forecast - by Delivery Mode
9.3.1. In-Studio
9.3.2. Hybrid
9.3.3. Digital/At-Home
9.4. Market Analysis, Insights and Forecast - by Business Model
9.4.1. Franchise
9.4.2. Independent
9.4.3. Corporate-Owned
9.5. Market Analysis, Insights and Forecast - by End User
9.5.1. Parents
9.5.2. Schools & Daycares
9.5.3. Healthcare Providers
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Class Type
10.1.1. Sensory Play
10.1.2. Music & Movement
10.1.3. Art & Craft
10.1.4. Physical Development
10.1.5. Multisensory Integration
10.2. Market Analysis, Insights and Forecast - by Age Group
10.2.1. 0-12 Months
10.2.2. 13-24 Months
10.2.3. 25-36 Months
10.3. Market Analysis, Insights and Forecast - by Delivery Mode
10.3.1. In-Studio
10.3.2. Hybrid
10.3.3. Digital/At-Home
10.4. Market Analysis, Insights and Forecast - by Business Model
10.4.1. Franchise
10.4.2. Independent
10.4.3. Corporate-Owned
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Parents
10.5.2. Schools & Daycares
10.5.3. Healthcare Providers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Gymboree Play & Music
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Baby Sensory (WOW World Group)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. The Little Gym
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. My Gym
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Kindermusik
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Lovevery
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Little Kickers
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Tumble Tots
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Music Together
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Bambini Early Learning
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Class Type 2026 & 2034
Figure 3: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Class Type 2026 & 2034
Figure 4: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Age Group 2026 & 2034
Figure 5: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Age Group 2026 & 2034
Figure 6: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 7: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 8: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Business Model 2026 & 2034
Figure 9: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Business Model 2026 & 2034
Figure 10: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by End User 2026 & 2034
Figure 11: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Class Type 2026 & 2034
Figure 15: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Class Type 2026 & 2034
Figure 16: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Age Group 2026 & 2034
Figure 17: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Age Group 2026 & 2034
Figure 18: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 19: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 20: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Business Model 2026 & 2034
Figure 21: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Business Model 2026 & 2034
Figure 22: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by End User 2026 & 2034
Figure 23: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by End User 2026 & 2034
Figure 24: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Class Type 2026 & 2034
Figure 27: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Class Type 2026 & 2034
Figure 28: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Age Group 2026 & 2034
Figure 29: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Age Group 2026 & 2034
Figure 30: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 31: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 32: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Business Model 2026 & 2034
Figure 33: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Business Model 2026 & 2034
Figure 34: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by End User 2026 & 2034
Figure 35: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by End User 2026 & 2034
Figure 36: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Class Type 2026 & 2034
Figure 39: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Class Type 2026 & 2034
Figure 40: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Age Group 2026 & 2034
Figure 41: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Age Group 2026 & 2034
Figure 42: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 43: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 44: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Business Model 2026 & 2034
Figure 45: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Business Model 2026 & 2034
Figure 46: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by End User 2026 & 2034
Figure 47: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by End User 2026 & 2034
Figure 48: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Class Type 2026 & 2034
Figure 51: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Class Type 2026 & 2034
Figure 52: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Age Group 2026 & 2034
Figure 53: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Age Group 2026 & 2034
Figure 54: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 55: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 56: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Business Model 2026 & 2034
Figure 57: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Business Model 2026 & 2034
Figure 58: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by End User 2026 & 2034
Figure 59: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by End User 2026 & 2034
Figure 60: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Class Type 2020 & 2034
Table 2: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Age Group 2020 & 2034
Table 3: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 4: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Business Model 2020 & 2034
Table 5: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 6: Global Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Class Type 2020 & 2034
Table 8: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Age Group 2020 & 2034
Table 9: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 10: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Business Model 2020 & 2034
Table 11: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 12: North America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Class Type 2020 & 2034
Table 17: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Age Group 2020 & 2034
Table 18: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 19: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Business Model 2020 & 2034
Table 20: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 21: Europe Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 22: UK Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Germany Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Italy Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Spain Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Class Type 2020 & 2034
Table 28: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Age Group 2020 & 2034
Table 29: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 30: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Business Model 2020 & 2034
Table 31: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 32: Asia Pacific Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 33: China Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Japan Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: India Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Australia Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Southeast Asia Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Class Type 2020 & 2034
Table 39: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Age Group 2020 & 2034
Table 40: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 41: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Business Model 2020 & 2034
Table 42: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 43: South America Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 44: Brazil Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Argentina Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Colombia Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Class Type 2020 & 2034
Table 48: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Age Group 2020 & 2034
Table 49: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 50: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Business Model 2020 & 2034
Table 51: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 52: Middle East & Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 53: UAE Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: Saudi Arabia Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 55: South Africa Growth Trajectories in Baby Sensory Classes: Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How big is the baby sensory classes market in 2025?
Our proprietary research estimates the global baby sensory classes market at USD 1.52 Billion in 2025, with a projected CAGR of 6.2% to reach USD 2.81 Billion by 2035. North America leads with a 38% revenue share.
2What is driving the growth of baby sensory classes?
Key drivers include rising parental spending on early childhood development, increased awareness of sensory integration benefits, urbanization and nuclear family structures in Asia-Pacific, and birth rate stabilization in high-value markets. Parents are allocating 11–14% more annual spend per child since 2022.
3Which region is fastest-growing for baby sensory classes?
Asia-Pacific is the fastest-growing region, projected to increase its global market share from 29% in 2025 to 33% by 2035, driven by China, India, and Southeast Asia. The region is expected to grow at a 6.8% CAGR.
4Who are the leading providers in the baby sensory classes market?
Leading providers include Gymboree Play & Music, Baby Sensory (WOW World Group), The Little Gym, My Gym, and Kindermusik. Franchise-based models account for 52% of global revenue, followed by independent studios at 38%.
5What are the main challenges facing the baby sensory classes industry?
High operational costs and real estate dependence, a fragmented competitive landscape with low entry barriers, cross-jurisdiction safety compliance complexities, and digital substitution from at-home sensory kits are the primary challenges. Annual churn rates average 28–35% in the sector.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 1,200+ in-depth interviews and surveys across 14 countries, representing 70–80% of total research input, with franchise headquarters, independent studio owners, franchisees, early-childhood educators, and pediatric development specialists.
Interviewed stakeholders including Franchise Development Directors, Early Childhood Education Consultants, Studio Operations Managers, and Pediatric Occupational Therapists to validate demand drivers and pricing dynamics.
Engaged with industry associations including the International Play Association (IPA), National Association for the Education of Young Children (NAEYC), and Early Childhood Australia for regulatory and standards verification.
Primary data collection focused on facility-level enrollment volumes, average fee per term, class capacity utilization, and customer acquisition costs to build bottom-up market estimates.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Franchise Development Director
30%
Studio Operations Manager
28%
Early Childhood Education Consultant
22%
Pediatric Occupational Therapist
12%
Procurement & Supply Chain Lead
8%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Franchise Headquarters & Brand Owners
35%
Independent Studio Operators
25%
Early Childhood Educators & Curriculum Specialists
20%
Equipment & Materials Suppliers
12%
Pediatric Development & Healthcare Professionals
8%
Secondary Research & Industry Benchmarking
Analyzed official multilateral and governmental datasets, including UN Comtrade (for play equipment trade flows), World Bank (for birth rate and urbanization trends), and OECD (for early childhood education spending and policy benchmarks).
Reviewed recognized non-profit technical standards and trade association publications from the U.S. Consumer Product Safety Commission (CPSC), European Committee for Standardization (CEN), and International Toy Industry Association (ICTI).
Benchmarked operational and financial metrics against publicly available franchise disclosure documents (FDDs) and corporate filings, ensuring 20–30% of research input was derived from secondary validation.
Utilized standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for company-level financial and ownership data; official .gov and .org sources were prioritized for all regulatory and demographic inputs.
Demand Modeling & Market Estimation
Applied simultaneous top-down and bottom-up methodologies, with multi-level data triangulation: top-down leveraged global early-childhood enrichment spend and service sector GDP contributions; bottom-up aggregated facility-level enrollment data, average term fees, and class frequency.
Key quantitative metrics included number of active sensory class facilities per capita, average annual enrollment per facility (120–200 infants), average fee per term (USD 180–350), and term-to-term retention rates (65–72%).
Developed a proprietary demand index incorporating birth cohort size, maternal employment rates, urban household disposable income, and penetration of organized early-childhood enrichment services.
Regional market shares were validated through cross-referencing facility counts, franchise disclosure data, and expert panel estimates; forecasts were stress-tested against alternative economic scenarios.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, achieved through multi-stage validation: initial model outputs were reviewed by internal sector specialists, then cross-validated with independent expert panels and select primary respondents.
Every report is updated to the date of purchase, incorporating the latest available trade statistics, demographic updates, and company developments.
Data triangulation protocols required at least three independent sources for any market size or growth rate figure, with discrepancies resolved through weighted averaging and expert adjudication.
Final quality assurance included outlier detection, consistency checks across regional and segment totals, and sensitivity analysis on key assumptions (birth rates, fee inflation, churn).