1What is the projected market size of AI home appliances by 2035?
Our proprietary research projects the market to reach USD 520.93 Billion by 2035, up from USD 185.14 Billion in 2025, representing a 10.9% CAGR over the forecast period.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Growth Strategies in AI Home Appliances Market
 by Product Type (Refrigerator, Dishwasher, Washing Machine & Dryer, Air Conditioner, Smart Cookware & Cooktops), by Connectivity Technology (Wi-Fi, Thread, ZigBee, Bluetooth, Cellular, RFID), by Distribution Channel (Offline, Online), by End-User (Residential, Commercial), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia-Pacific (China, India, Japan), by South America (Brazil), by Middle East & Africa (UAE, Saudi Arabia) Forecast 2026-2034

Senior Research Analyst


 Related Reports

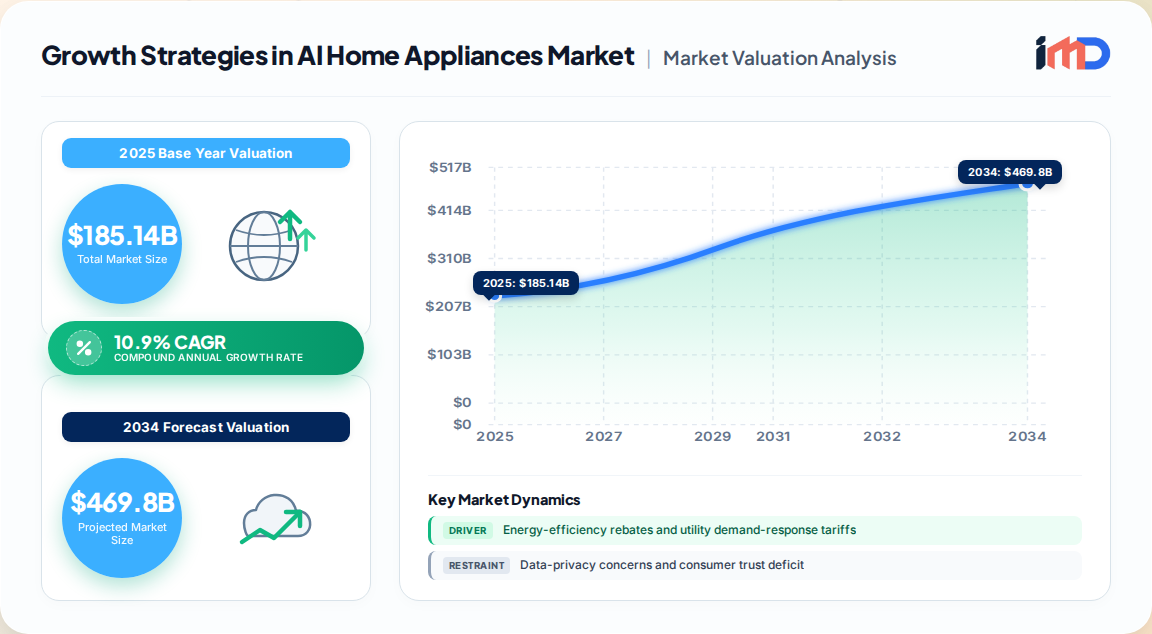
The AI home appliances market is undergoing a structural transformation. Our proprietary research estimates the global smart appliance revenue pool at USD 185.14 Billion in 2025, advancing to USD 205.34 Billion in 2026 and USD 520.93 Billion by 2035, a 10.9% CAGR. Growth strategies in this market are no longer about bolting connectivity onto legacy white goods; they are about monetizing intelligence across the product lifecycle.
Three forces define the strategic agenda. First, policy-driven replacement — the U.S. Inflation Reduction Act's Home Energy Rebate programs (over USD 9 billion allocated) and the EU Ecodesign for Sustainable Products Regulation mandating digital product passports after 2027 — is pulling forward upgrade cycles. Second, protocol consolidation through Matter lowers multi-ecosystem engineering costs by an estimated 30%, inviting mid-tier brands into the arena. Third, edge-AI and on-device generative assistance shift value from hardware margin to recurring service revenue.
Strategically, the winners will be those who treat the appliance as a grid-interactive, data-generating asset rather than a one-time sale.
Our driver impact modeling, built from primary interviews with OEM strategy leads and utility program administrators, quantifies each growth lever's contribution to the 10.9% CAGR.
| Growth Driver | ~% Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Energy-efficiency rebates & time-of-use tariffs | 18–22% | North America, Europe | Short-term (≤2 yr) |
| Matter protocol & multi-ecosystem interoperability | 14–18% | Global | Medium-term (2–4 yr) |
| AI-powered predictive maintenance & personalization | 12–15% | North America, Asia-Pacific | Medium-term (2–4 yr) |
| Urbanization & smart-city housing mandates | 10–13% | Asia-Pacific, MEA | Long-term (≥4 yr) |
| 5G / Wi-Fi 6E broadband expansion | 8–11% | Global | Medium-term (2–4 yr) |
| Cybersecurity compliance & data-privacy regulation | 6–9% | Europe, North America | Short-term (≤2 yr) |
| Semiconductor cost reduction & supply normalization | 5–8% | Global | Short-term (≤2 yr) |
Energy-efficiency rebates are the single largest near-term accelerator. Utilities in California, Texas, and New York now offer time-of-use tariffs that turn connected washers and dryers into revenue-generating assets for households.
AI predictive maintenance is the highest-margin strategic lever. Embedded machine learning detects component degradation weeks before failure; OEMs deploying it report double-digit reductions in warranty claim rates for connected versus non-connected products.
Restraints center on data-privacy trust deficits, high upfront cost premiums (typically 15–25% over non-connected equivalents), and fragmented connectivity in legacy installations.
Growth strategy must be segment-specific. Our segmentation data reveals where to allocate capital.
By Product Type: Smart washing machines and dryers held ~26% of 2025 revenue. Smart cookware and cooktops are the fastest-growing category at a 13.7% CAGR, driven by induction platforms with integrated recipe guidance — a high-value white space for premiumization.
By Connectivity Technology: Wi-Fi captured ~63% of 2025 revenue, but Thread-based devices are advancing at a 13.9% CAGR as Matter certification favors low-power mesh protocols. Strategy: transition new SKUs to Thread/Matter dual-stack.
By Distribution Channel: Offline retail generated ~66% of 2025 revenue, with experiential showrooms decisive for high-ticket items. Online is growing at 12.6% CAGR; investment in augmented-reality kitchen planners is the key differentiator.
By End-User: Residential represented ~71% of 2025 revenue; commercial is expanding at 12.2% CAGR led by hospitality and co-living operators standardizing connected kitchenettes.
White-space opportunities identified through our primary interviews: (1) Appliance-as-a-Service and subscription models; (2) Edge-AI and on-device generative assistance; (3) Emerging-market expansion through localized manufacturing in India and Southeast Asia.
| Region | 2025 Share | Strategic Priority | Growth Strategy Focus |
|---|---|---|---|
| North America | ~35% | Defend & monetize | Utility demand-response partnerships; premium AI features |
| Europe | ~26.5% | Compliance-led upgrade | Ecodesign digital passports; energy-label premiumization |
| Asia-Pacific | ~28% | Scale & localize | 12.0% CAGR; localized manufacturing via India PLI (~USD 800M) |
| Middle East & Africa | ~4.5% | Infrastructure bet | Smart-city housing mandates; leapfrog to Matter-native SKUs |
| South America | ~6% | Selective entry | Mid-tier brand partnerships; 5G FWA-enabled adoption |
Asia-Pacific is the fastest-growing region at a projected 12.0% CAGR through 2035, fueled by urbanization across China, India, and Southeast Asia. North America's 35% share reflects high broadband penetration and aggressive retail promotions. Europe's strict energy-labeling directives continue to drive replacement demand.
The market is led by Samsung Electronics, LG Electronics, Whirlpool Corporation, Haier Smart Home, BSH Home Appliances, and Midea Group. Strategic positioning varies by archetype:
Our primary research indicates that OEMs adopting Matter reduce per-unit software engineering costs by an estimated 30%, materially widening addressable margins for mid-tier brands entering the market for the first time.
Global semiconductor investment earmarked for IoT-grade chipsets exceeded USD 14 billion in 2024, reflecting OEM confidence that embedded intelligence is becoming table stakes. This upstream capacity build-out is de-risking the AI appliance value chain.
Key supply chain risks we flag:
Utility demand-response programs introduce a new value-chain participant — the aggregator — that sits between the appliance OEM and the grid operator, creating a recurring-revenue channel and a new basis for competitive differentiation.
Applying an Ansoff lens, our recommended growth strategies for AI home appliances are:
The unifying principle: shift revenue mix from one-time hardware margin toward recurring, data-enabled service revenue, anchored by policy-driven replacement cycles and Matter-enabled interoperability.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.9% from 2020-2034 |
| Segmentation |
|
By Connectivity Technology
By Distribution Channel
By End-User
| By Geography |
|
Our proprietary research projects the market to reach USD 520.93 Billion by 2035, up from USD 185.14 Billion in 2025, representing a 10.9% CAGR over the forecast period.
Asia-Pacific is the fastest-growing region at a projected 12.0% CAGR through 2035, driven by urbanization across China, India, and Southeast Asia. North America currently leads with roughly a 35% market share.
AI predictive maintenance contributes an estimated 12–15% to the CAGR by reducing warranty claim rates by double digits for connected appliances. OEMs like Samsung (Bespoke AI) and LG (ThinQ) monetize this through subscription services.
Matter certification reduces per-unit software engineering costs by an estimated 30% and contributes 14–18% to the CAGR by enabling multi-ecosystem compatibility across Amazon Alexa, Google Home, and Apple HomeKit.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Strategy Officer | 30% |
| VP of Product Management | 30% |
| Director of Connected Devices | 25% |
| Head of Sustainability & Regulatory Affairs | 15% |
| Company Type | Representation (%) |
|---|---|
| Appliance OEMs & Brand Owners | 35% |
| IoT Semiconductor & Connectivity Module Suppliers | 25% |
| Utility Demand-Response Aggregators | 15% |
| Retail & Experiential Showroom Operators | 15% |
| Firmware & Standards Compliance Providers | 10% |