1What is the size of the global corporate workforce development training market?
The market is estimated at USD 285.68 billion in 2026 and is projected to reach USD 402.13 billion by 2031, growing at a CAGR of 7.08%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Global Corporate Workforce Development Training Market
 by Training Type (Technical and Digital Skills, Leadership, Compliance, Sales, Professional, Interpersonal, Culture and Well-being), by Learning Format (Online, Instructor-Led, Blended), by Organization Size (Large Enterprises, SMEs), by Industry Vertical (IT/Telecom, BFSI, Healthcare and Life Sciences, Manufacturing, Retail, and More), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia-Pacific (China, Japan, India), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034

Senior Analyst


 Related Reports

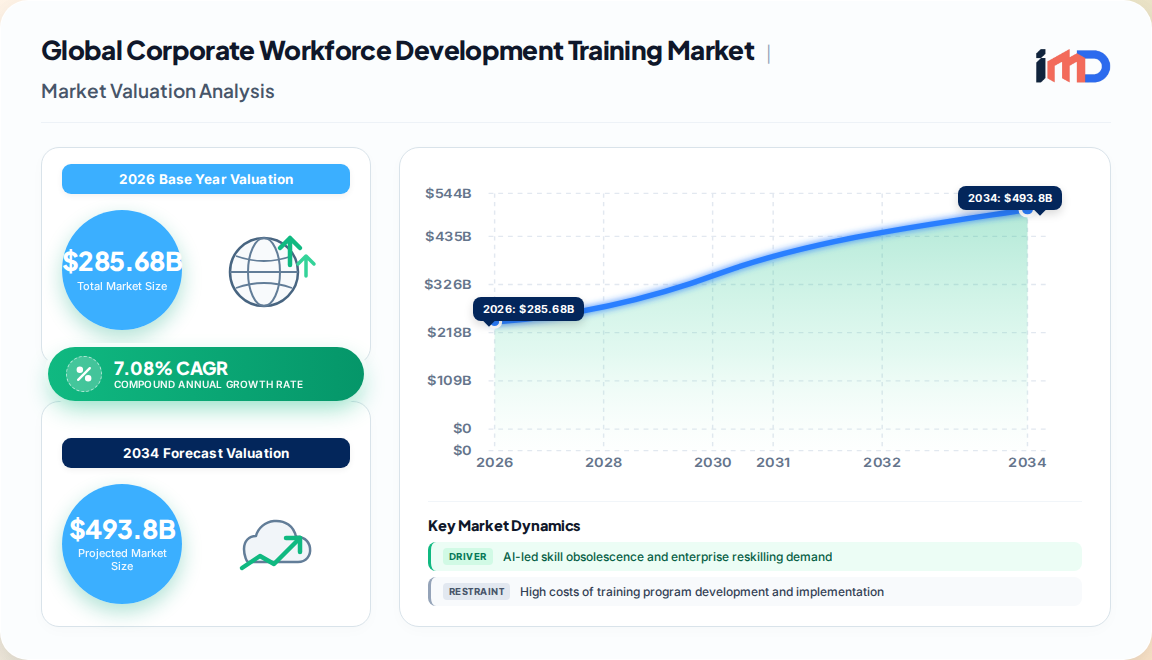
The global corporate workforce development training market is undergoing a structural transformation. No longer a discretionary HR line item, workforce development is now a continuous operating requirement tied directly to role redesign, compliance, productivity, and enterprise risk management. Our proprietary primary research estimates the market at USD 285.68 billion in 2026, rising to USD 402.13 billion by 2031 at a CAGR of 7.08% over the forecast period. This expansion reflects a fundamental revaluation of learning investment: employers face shorter skill-relevance cycles, and the cost of capability gaps—measured in execution delays, audit findings, and attrition—now outweighs the cost of training.
The World Economic Forum projects that 39% of workers' core skills will change by 2030, up from a 35% disruption threshold recorded in 2016. That compression leaves organizations with less time to respond to learning needs, and it explains why budgets are migrating from periodic HR allocations to continuous operating lines. AI literacy obligations and sector-specific regulatory training are further anchoring spend in legal, risk, and operations budgets, reducing exposure to discretionary cuts.
The competitive environment remains moderately fragmented, with learning platforms, HCM vendors, and managed service providers all pursuing multi-year enterprise contracts. Differentiation is shifting from content breadth to skills mapping, outcome measurement, and the ability to deliver measurable productivity gains.
Drivers
Restraints
Our segmentation framework draws on primary interviews with enterprise learning leaders, platform vendors, and managed service providers. The market is segmented by training type, learning format, organization size, industry vertical, and geography. The table below summarizes revenue shares and growth outlook by segment.
| Segment | Category | 2025 Share / Value | CAGR Outlook |
|---|---|---|---|
| Training Type | Technical and Digital Skills | 28.33% of revenue | — |
| Training Type | Interpersonal, Culture, and Well-being | — | 8.56% (through 2031) |
| Learning Format | Instructor-Led Training | 42.91% of revenue | — |
| Learning Format | Blended Training | — | 7.48% (through 2031) |
| Organization Size | Large Enterprises | 67.33% of revenue | — |
| Organization Size | SMEs | — | 7.92% (through 2031) |
| Industry Vertical | IT and Telecom | 22.46% share | — |
| Industry Vertical | Healthcare and Life Sciences | — | 8.19% (through 2031) |
Technical training remains the largest training-type segment, valued at USD 66.91 billion in 2024, driven by rapid technological evolution and the adoption of virtual instructor-led training and experiential learning. The technical segment is central to the market because it directly addresses critical skill gaps in AI, cloud, cybersecurity, and data analytics. Interpersonal, culture, and well-being training is the fastest-growing training type, reflecting employer focus on retention, engagement, and manager capability.
Instructor-led training retains the largest format share, but blended learning is gaining rapidly as organizations combine virtual simulations, microlearning, and in-person workshops. By organization size, large enterprises dominate current spend, while SMEs are the faster-growing cohort as platform pricing and modular content lower barriers to adoption. IT and telecom is the largest vertical, with healthcare and life sciences posting the strongest growth due to compliance intensity and clinical workforce needs.
North America remains the largest regional market, accounting for 35.74% of global revenue in 2025 by our estimates, supported by high adoption of corporate eLearning, leadership development, and AI-related reskilling. The U.S. is the single largest country market, with 43.9% contribution to regional growth during the forecast period.
Asia-Pacific is the fastest-growing region, projected to expand at 8.84% CAGR through 2031. Growth is driven by a massive need for upskilling, mobile-first microlearning preferences, and blended learning models. China, Japan, and India are key markets, with India showing particular strength in IT and business process management training.
Europe prioritizes soft skills development, diversity and inclusion programs, and regulatory compliance. The EU AI Act is creating a new recurring training demand layer across member states. Germany, the UK, and France are the largest European markets.
South America and the Middle East & Africa are smaller but growing regions, with demand concentrated in large enterprises and government-supported workforce readiness programs. The table below summarizes regional market shares and growth outlook.
| Region | 2025 Share (Est.) | Growth Outlook |
|---|---|---|
| North America | 35.74% | Moderate, led by U.S. |
| Europe | 24.0% | Moderate, regulatory-driven |
| Asia-Pacific | 28.0% | Fastest, 8.84% CAGR |
| South America | 5.0% | Emerging |
| Middle East & Africa | 7.26% | Emerging |
The market is moderately fragmented, with learning platforms, HCM vendors, and managed service providers competing for multi-year enterprise contracts. Major players include Udemy Business, Skillsoft Corporation, Coursera for Business, Docebo Inc., and NIIT Learning Systems Limited, among others. Competition is shifting toward skills mapping, outcome measurement, AI-driven personalization, and integration with HR and performance management systems.
Vendors are expanding content libraries, adding adaptive learning paths, and building scenario-based and interactive video capabilities to move training from passive consumption to active participation. Multinational logistics firms, for example, are implementing blended learning models that combine virtual simulations for drivers with microlearning platforms for dispatchers, aiming to improve route efficiency and reduce delivery times.
For investors and providers, Asia-Pacific offers the strongest growth opportunity, driven by workforce scale, mobile-first learning preferences, and rapid digital transformation. North America remains the highest-value market for premium enterprise contracts, particularly in AI reskilling, leadership development, and compliance training. Europe presents a stable, regulation-driven opportunity, with the EU AI Act creating a new recurring demand layer for AI literacy and governance training. South America and the Middle East & Africa offer early-stage opportunities in government-supported workforce readiness and vocational training.
Our assessment suggests that providers with modular, AI-enabled platforms and strong outcome measurement capabilities are best positioned to capture share across regions. The ability to localize content and deliver in blended formats is a key success factor in Asia-Pacific and Europe.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.08% from 2020-2034 |
| Segmentation |
|
By Learning Format
By Organization Size
By Industry Vertical
| By Geography |
|
The market is estimated at USD 285.68 billion in 2026 and is projected to reach USD 402.13 billion by 2031, growing at a CAGR of 7.08%.
Asia-Pacific is the fastest-growing region, projected to expand at 8.84% CAGR through 2031, driven by large-scale upskilling needs and mobile-first learning adoption.
Key drivers include AI-led skill obsolescence and reskilling demand, non-discretionary compliance and risk training budgets, career development programs improving retention, and EU AI literacy obligations.
Major players include Udemy Business, Skillsoft Corporation, Coursera for Business, Docebo Inc., and NIIT Learning Systems Limited, among others.
Technical and digital skills training accounted for 28.33% of revenue in 2025, while interpersonal, culture, and well-being training is forecast to grow at 8.56% CAGR through 2031.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Learning Officer | 30% |
| VP of Talent Development | 25% |
| Compliance Director | 20% |
| Procurement Manager | 15% |
| HR Business Partner | 10% |
| Company Type | Representation (%) |
|---|---|
| Corporate Learning & Development Leaders | 35% |
| HR & Talent Executives | 25% |
| Compliance & Risk Officers | 15% |
| Platform Vendors & EdTech Providers | 15% |
| Managed Service Providers & Consultants | 10% |