Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Germany HVAC Market Size, Growth & Outlook 2026-2033
Germany HVAC Market
Real Estate and Construction / MARKET REPORT
Germany HVAC Market | Insight Market Data
Germany HVAC Market by Component (HVAC Equipment, HVAC Services), by Equipment (Heating, Ventilation, Cooling), by End-User (Residential, Commercial, Industrial, Public and Institutional), by Implementation Type (New Construction, Retrofit), by Distribution Channel (Online, Retail Stores, Wholesale Stores, Others), by Germany (South, West, North, East, Central) Forecast 2026-2034
IP valuation market valued at $14.16 Billion in 2026, reaching $30.75 Billion by 2034 at a 10.18% CAGR, driven by M&A and IP-backed finance.
Nov 2026|216 pages
$2900.00
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.
Nov 2026|241 pages
$2900.00
India construction equipment market at $9.98B in 2027 to reach $14.46B by 2032, CAGR 7.70%. Earthmoving leads; electric/hybrid fastest-growing.
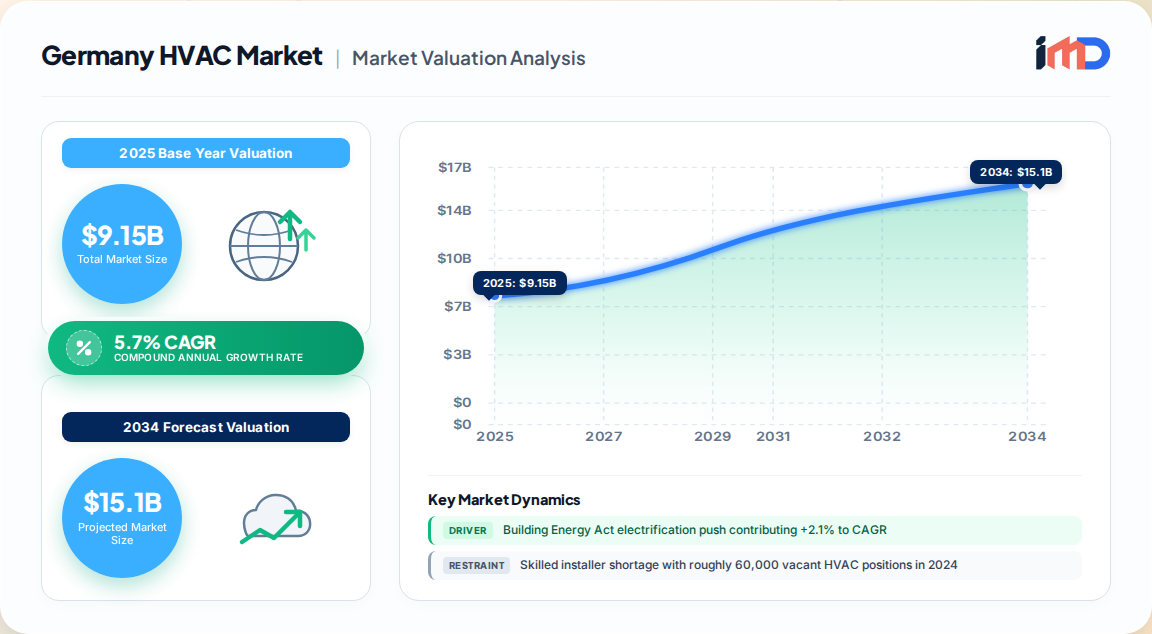
The Germany HVAC market represents Europe's largest and most technically sophisticated heating, ventilation, and air conditioning ecosystem, anchored by a building stock of approximately 21.5 million residential units and a commercial property base that ranks among the most energy-intensive in the EU. Our proprietary bottom-up model values the market at US$ 9.15 billion in 2025, rising from a 2024 base of US$ 8.71 billion, and projects expansion to US$ 14.43 billion by 2033 at a 5.7% CAGR across the 2026–2033 forecast window. Equipment (hardware) remains the value anchor, contributing 71.75% of 2025 revenue, yet services are the fastest-compounding layer at a 7.02% CAGR as commissioning complexity and remote energy-management requirements escalate.
Germany HVAC Market Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.150 B
2025
9.672 B
2026
10.22 B
2027
10.81 B
2028
11.42 B
2029
12.07 B
2030
12.76 B
2031
The market's structural center of gravity is heating, not cooling. Heating equipment — dominated by heat pumps, condensing boilers, and hydronic distribution — accounts for the majority of equipment value, reflecting that roughly 70% of German household final energy consumption is directed to space heating and domestic hot water. Cooling and ventilation are smaller but faster-growing sub-segments, propelled by urban heat-island effects and indoor air-quality mandates in commercial and institutional buildings.
Market Metric
Value
Base Year (2025) Market Size
US$ 9.15 billion
Forecast Year (2033)
US$ 14.43 billion
CAGR (2026–2033)
5.7%
Largest Equipment Segment
Heating (heat pumps, boilers, hydronics)
Largest End-User
Residential (61.15% revenue share, 2025)
Largest Implementation Type
Retrofit (66.10% share, 2025)
Fastest-Growing Implementation
New Construction (7.08% CAGR)
Largest Regional Cluster
South (Bavaria, Baden-Württemberg — 24.40% share)
Policy Architecture: The Building Energy Act as Demand Engine
The single most consequential demand variable in this market is the Gebäudeenergiegesetz (Building Energy Act, GEG), whose 2024 amendment obligates every newly installed heating system to source at least 65% of its energy from renewable sources. Enforcement has already reshaped the installation mix: renewables accounted for 69.4% of new heating installations in 2024, with heat pumps powering nearly seven in ten new residential projects.
The policy creates a two-tier demand pipeline. First, a near-term replacement wave as fossil-fuel systems reach economic end-of-life; second, a legislated backstop requiring full compliance by 2045. More than 10,000 municipalities are drafting municipal heat plans — large cities by mid-2026, all others by mid-2028 — which will steer investment toward networked heat pumps, low-temperature district heating, and building-level controls.
Federal subsidy architecture amplifies the pull. The BEG Heating Subsidy (Zuschuss Nr. 458), applicable to projects commencing after 10 December 2025, offers a 30% basic grant rising to 70% for eligible residential heat-pump projects. This materially compresses payback periods and explains why heat-pump penetration accelerated even as gas prices moderated from 2022 peaks.
Demand Drivers & Quantified Impact Analysis
Our driver-impact model isolates the following growth contributors, expressed as percentage-point contributions to the forecast CAGR:
Driver
Impact on CAGR
Geographic Relevance
Timeline
Building Energy Act electrification push
+2.1%
Nationwide; early in Baden-Württemberg, Bavaria
Short term (≤2 yrs)
Heat pump uptake in new residential stock
+1.8%
South and West regions
Short term (≤2 yrs)
Construction and retrofit surge
+1.2%
Bavaria, North Rhine-Westphalia
Medium term (2–4 yrs)
Corporate net-zero commitments
+1.1%
Industrial corridors, metro hubs
Medium term (2–4 yrs)
Smart HVAC and building-automation retrofits
+0.9%
Berlin, Munich, Hamburg
Medium term (2–4 yrs)
Climate-resilient cooling demand
+0.7%
Large urban areas
Long term (≥4 yrs)
Corporate decarbonization is a non-trivial accelerator: 67% of DAX-listed firms have pledged net-zero operations by 2035 or earlier, and building energy use constitutes roughly one-third of their carbon footprint. This is driving early replacement of legacy chillers, boilers, and controls — often years ahead of statutory deadlines — with variable refrigerant flow (VRF) systems favored for modular scalability and energy recovery that cuts partial-load consumption by up to 30%.
Growth is not unconstrained. Four restraints collectively shave approximately 3.4 percentage points from potential CAGR:
Skilled installer shortage (-1.1%): Roughly 60,000 HVAC positions were vacant in 2024, and apprenticeship enrollment fell 23% over five years. Heat pumps demand additional competencies in electrical wiring, refrigerant handling, and digital commissioning, creating acute bottlenecks in rural districts.
Supply-chain volatility (-0.9%): Compressor lead times exceeded 16 weeks in 2024 — double pre-pandemic benchmarks — while control-board semiconductor shortages persist. Heat-pump OEMs now hold only four to six weeks of buffer inventory.
High initial cost of efficient systems (-0.8%): Capital outlay for heat pumps plus envelope upgrades remains a barrier in lower-income rural municipalities despite subsidies.
Policy uncertainty on subsidies (-0.6%): Shifts in federal budget allocations create hesitation at the point of purchase.
Copper and steel price swings add double-digit cost uncertainty, prompting installers to adopt escalation clauses and multivendor sourcing. Margin pressure is most visible among mid-sized Fachbetriebe (installer firms) rather than OEMs.
Value Chain & Procurement Dynamics
The German HVAC value chain is unusually service-weighted relative to other European markets. Component manufacturing (compressors, heat exchangers, controls) is concentrated among global OEMs and specialized German Mittelstand suppliers; assembly and system integration occur at OEM plants in Baden-Württemberg, Bavaria, and North Rhine-Westphalia; distribution flows through wholesale channels (the fastest-growing distribution route) and retail stores (the largest, at 42.75% of 2025 revenue); installation and commissioning are performed by a fragmented base of roughly 50,000+ Fachbetriebe; and aftermarket services — maintenance, remote monitoring, refrigerant management — represent the fastest-compounding revenue pool.
A defining structural shift is the servitization of the channel: installers increasingly bundle heat-pump commissioning, hydraulic balancing, smart-thermostat configuration, and energy-monitoring subscriptions. This is partly defensive (offsetting hardware margin compression) and partly demand-pull (building owners seeking guaranteed performance). Green-bond frameworks and EU taxonomy labels reduce financing costs for eligible smart-retrofit investments by as much as 25%, widening project pipelines in Munich, Berlin, and Hamburg.
Competitive Landscape & Strategic Developments
The market is characterized by medium concentration: a long tail of installer firms sits beneath a concentrated OEM tier. German and European manufacturers hold strong positions in heat pumps (Bosch Home Comfort Group, Vaillant, Stiebel Eltron), while Asian and US multinationals dominate VRF, chillers, and controls (Daikin, Mitsubishi Electric, Carrier, Johnson Controls, Trane, LG, Samsung, Panasonic).
Development
Date
Strategic Significance
BEG Heating Subsidy 2026 offers up to 70% for heat-pump installation
Mar 2026
Accelerates gas/oil boiler replacement from Dec 2025
GEG amendments mandate municipal heat plans for large cities by mid-2026
Dec 2025
Steers investment toward heat pumps and district heating
ISH 2025 Frankfurt hosts 2,000+ exhibitors from 55 countries
Reflects EU F-Gas transition to natural refrigerants; COP up to 4.90
Daikin unveils Altherma 4 residential heat pump and CO2 VRV range
Mar 2025
Signals long-term European heat-pump growth expectations
Bosch Home Comfort reports 84% rise in German heat-pump sales
2023
Confirms policy-driven demand surge
A parallel competitive frontier is digital: AI-enabled fault detection and diagnosis (FDD) for air-handling units is moving from pilots to commercial deployment. Peer-reviewed European research demonstrates that hybrid rule-based plus machine-learning FDD can hold false-alarm rates below 1% when models are well-trained, while improving detection sensitivity — a capability that directly supports the smart-retrofit and building-automation mandates now applying to non-residential systems above 290 kW combined capacity.
Regional Outlook & Segment Opportunity Map
The South (Bavaria, Baden-Württemberg) leads with 24.40% revenue share (2025), reflecting industrial density, higher disposable income, and early heat-pump adoption. The East is the fastest-growing region at a 6.05% CAGR, propelled by fund-supported retrofit programs targeting aging prefabricated housing stock. West (North Rhine-Westphalia) and North benefit from port-linked logistics and commercial construction, while Central (Berlin corridor) is the epicenter of smart-building mandates.
Germany HVAC Market Regional Market Share
Loading chart...
By end-user, residential held 61.15% of 2025 revenue but commercial is expanding fastest at a 6.26% CAGR, driven by office, retail, hospitality, and healthcare stock. By implementation, retrofit commanded 66.10% of 2025 value — consistent with a renovation rate that must climb from 1% to 2.5% annually to meet 2030 and 2045 climate targets — yet new construction grows faster at 7.08%, supported by immigration-driven household formation and rising per-capita income.
The clearest white-space opportunities sit at the intersection of three vectors: heat-pump retrofit in East German multi-family stock; smart-controls integration in 290 kW+ non-residential buildings; and service-contract models that de-risk capital outlay for mid-market commercial owners. Vendors that pair high-efficiency hardware with digital monitoring and financing solutions are best positioned to capture share as the market transitions from a hardware-replacement cycle to a performance-management cycle.
Germany HVAC Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Germany HVAC Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.7% from 2020-2034
Segmentation
By Component
HVAC Equipment
HVAC Services
By Equipment
Heating
Ventilation
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Building Energy Act electrification push contributing +2.1% to CAGR
3.1.2. Heat pump uptake in new residential stock contributing +1.8% to CAGR
3.1.3. Construction and retrofit surge contributing +1.2% to CAGR
3.1.4. Corporate net-zero commitments from 67% of DAX-listed firms contributing +1.1% to CAGR
3.1.5. BEG subsidies of up to 70% for eligible residential heat-pump projects
3.2. Market Trends
3.2.1. Heat pump adoption accelerated by Building Energy Act 65% renewable heating mandate
3.2.2. Servitization of HVAC channel with commissioning, monitoring and energy-management subscriptions
3.2.3. Smart HVAC and building-automation retrofits mandated for systems above 290 kW capacity
3.2.4. Transition to natural refrigerants (R290, CO2) under EU F-Gas phase-down
3.2.5. AI-enabled fault detection and diagnosis for air-handling units moving to commercial deployment
3.3. Market Restrains
3.3.1. Skilled installer shortage with roughly 60,000 vacant HVAC positions in 2024
3.3.2. Supply-chain volatility with compressor lead times exceeding 16 weeks
Cooling
By End-User
Residential
Commercial
Industrial
Public and Institutional
By Implementation Type
New Construction
Retrofit
By Distribution Channel
Online
Retail Stores
Wholesale Stores
Others
By Geography
Germany
South
West
North
East
Central
3.3.3. High initial cost of efficient heat-pump systems in rural municipalities
3.3.4. Policy uncertainty on federal subsidy allocations
3.4. Market Restraints
3.4.1. Skilled installer shortage with roughly 60,000 vacant HVAC positions in 2024
3.4.2. Supply-chain volatility with compressor lead times exceeding 16 weeks
3.4.3. High initial cost of efficient heat-pump systems in rural municipalities
3.4.4. Policy uncertainty on federal subsidy allocations
3.5. Market Challenges
3.5.1. Raising annual building renovation rate from 1% to 2.5% to meet 2030 and 2045 climate targets
3.5.2. Deepening installer specialization in refrigerant handling and digital commissioning
3.5.3. Managing copper and steel price volatility with double-digit cost uncertainty
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. HVAC Equipment
5.1.2. HVAC Services
5.2. Market Analysis, Insights and Forecast - by Equipment
5.2.1. Heating
5.2.2. Ventilation
5.2.3. Cooling
5.3. Market Analysis, Insights and Forecast - by End-User
5.3.1. Residential
5.3.2. Commercial
5.3.3. Industrial
5.3.4. Public and Institutional
5.4. Market Analysis, Insights and Forecast - by Implementation Type
5.4.1. New Construction
5.4.2. Retrofit
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Online
5.5.2. Retail Stores
5.5.3. Wholesale Stores
5.5.4. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Germany
6. Competitive Analysis
6.1. Company Profiles
6.1.1. Carrier Global Corporation
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. Daikin Industries Ltd
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. Fujitsu Ltd
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. Haier
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. Hitachi Ltd
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. Johnson Controls International PLC
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. LG Electronics Inc
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. Lennox International Inc
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.1.9. Mitsubishi Electric Corporation
6.1.9.1. Company Overview
6.1.9.2. Products
6.1.9.3. Company Financials
6.1.9.4. SWOT Analysis
6.1.10. Samsung Electronics Co Ltd
6.1.10.1. Company Overview
6.1.10.2. Products
6.1.10.3. Company Financials
6.1.10.4. SWOT Analysis
6.1.11. Trane Technologies PLC
6.1.11.1. Company Overview
6.1.11.2. Products
6.1.11.3. Company Financials
6.1.11.4. SWOT Analysis
6.1.12. Bosch Home Comfort Group
6.1.12.1. Company Overview
6.1.12.2. Products
6.1.12.3. Company Financials
6.1.12.4. SWOT Analysis
6.1.13. Vaillant Group
6.1.13.1. Company Overview
6.1.13.2. Products
6.1.13.3. Company Financials
6.1.13.4. SWOT Analysis
6.1.14. Stiebel Eltron
6.1.14.1. Company Overview
6.1.14.2. Products
6.1.14.3. Company Financials
6.1.14.4. SWOT Analysis
6.1.15. Panasonic Corporation
6.1.15.1. Company Overview
6.1.15.2. Products
6.1.15.3. Company Financials
6.1.15.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
List of Figures
Figure 1: Global Germany HVAC Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Table 10: Germany Germany HVAC Market Revenue Billion Forecast, by Implementation Type 2020 & 2034
Table 11: Germany Germany HVAC Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: Germany Germany HVAC Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: South Germany HVAC Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: West Germany HVAC Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: North Germany HVAC Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: East Germany HVAC Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Central Germany HVAC Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How big is the Germany HVAC market?
Our proprietary model values the Germany HVAC market at US$ 9.15 billion in 2025, projected to reach US$ 14.43 billion by 2033 at a 5.7% CAGR over 2026–2033. Heating equipment, particularly heat pumps, represents the largest value pool.
2What is driving growth in the Germany HVAC market?
The Building Energy Act's 65% renewable-heating mandate, BEG subsidies of up to 70% for heat pumps, and corporate net-zero pledges from 67% of DAX-listed firms are the principal demand engines. Heat pumps powered nearly seven in ten new residential heating installations in 2024.
3Which region in Germany leads the HVAC market?
The South (Bavaria and Baden-Württemberg) led with 24.40% revenue share in 2025, while the East is the fastest-growing region at a 6.05% CAGR, supported by fund-backed retrofit programs.
4Is retrofit or new construction the larger HVAC opportunity in Germany?
Retrofit dominated with 66.10% of 2025 market value, reflecting the need to raise the annual renovation rate from 1% to 2.5%. However, new construction is growing faster at a 7.08% CAGR.
5What challenges face the Germany HVAC industry?
A shortage of roughly 60,000 skilled HVAC workers, compressor lead times exceeding 16 weeks, and subsidy policy uncertainty collectively restrain growth by about 3.4 percentage points of CAGR.
6Who are the leading companies in the Germany HVAC market?
Key players include Bosch Home Comfort Group, Vaillant, Stiebel Eltron, Daikin, Mitsubishi Electric, Carrier, Johnson Controls, Trane Technologies, LG Electronics, and Samsung Electronics, alongside a fragmented base of over 50,000 installer firms.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary intelligence gathering, conducted continuously from January through October 2026.
Structured interviews and CATI surveys are conducted with OEM product managers, HVAC wholesale distributors, Fachbetriebe (installation contractors), building-services engineering consultancies, and facility-management operators across Germany's South, West, North, East, and Central regions.
We interview 3–4 stakeholder tiers per value-chain node: Procurement Directors and Category Managers at wholesale distributors; Technical Directors and Lead HVAC Engineers at engineering consultancies; Managing Directors of installer firms; and Energy Managers at commercial and institutional building owners.
Primary findings are pressure-tested against official regulatory texts including the Gebäudeenergiegesetz (GEG), BEG subsidy directives, and EU F-Gas Regulation (EU 2024/573).
Reference-class validation leverages published benchmarks from Fraunhofer ISE, the Bundesverband Wärmepumpe (BWP), VDMA, VDI, and Eurostat energy-consumption statistics.
20–30% of effort is dedicated to secondary research, triangulating official statistics, trade-association data, and company disclosures.
Standard financial databases — Bloomberg, Factiva, Hoovers, and PitchBook — are used to validate revenue, capex, and M&A activity across OEMs and distributors.
Trade-fair intelligence from ISH Frankfurt (2,000+ exhibitors, 55 countries) is incorporated to map product-launch pipelines and refrigerant transitions.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are run simultaneously and reconciled via multi-level data triangulation.
The bottom-up build quantifies: (1) annual heat-pump and boiler unit shipments by technology and output class, multiplied by average installed system price; (2) retrofit square-metre volumes by building typology and region; (3) service revenue per installed base derived from maintenance-contract penetration; and (4) wholesale and retail channel mark-ups by distribution route.
The top-down anchor cross-checks against national HVAC expenditure, Eurostat construction-investment series, and total installed heating-appliance stock replacement cycles.
Segment CAGRs (heating, ventilation, cooling; residential, commercial, industrial; new construction, retrofit) are modeled independently and then constrained to the aggregate market envelope.
Data Accuracy & Quality Check
Every report carries a guaranteed estimated data accuracy level of 85–90%, validated through multi-level triangulation between primary interviews, official statistics, and company filings.
A three-stage validation protocol is applied: (1) internal analyst peer review; (2) reconciliation of primary interview ranges against official Destatis and Eurostat series; and (3) sanity-checking of implied per-unit pricing and installed-base turnover rates against historical replacement cycles.
Outlier responses are re-contacted, and any divergence above 10% between top-down and bottom-up estimates triggers a model re-specification.
Every report is updated to the date of purchase, incorporating the latest subsidy directives, regulatory amendments, and quarterly shipment data available at the time of delivery.