Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Future Prospects for Construction Integrated Project Delivery Market
Logistics / MARKET REPORT
Future Prospects for Construction Integrated Project Delivery Market | Insight Market Data
Future Prospects for Construction Integrated Project Delivery Market by Project Type (Commercial, Industrial, Infrastructure, Institutional), by Service Type (Architectural & Engineering, Construction Management, Consultancy, General Contracting), by Project Size (Large, Medium, Small), by North America (USA, Canada), by Europe (UK, Germany, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, India, Australia), by Middle East & Africa (GCC, Africa), by South America (Brazil, Mexico) Forecast 2026-2034
US air freight transport market was USD 66.70B in 2026, growing at 4.08% CAGR to reach USD 91.81B by 2034, driven by e-commerce and cold-chain demand.
Nov 2026|219 pages
$2900.00
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.
Executive Overview: The Collaborative Delivery Inflection Point
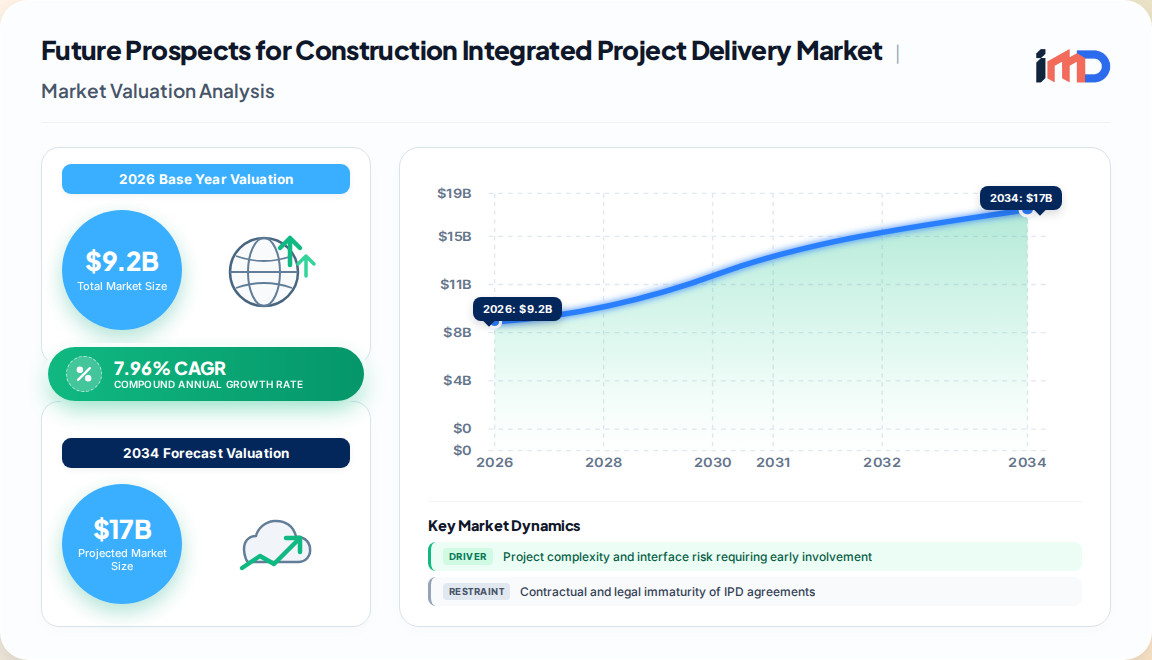
The global construction integrated project delivery (IPD) market is at an inflection point. Our proprietary primary research estimates that the market will expand by USD 8.45 billion between 2026 and 2032, registering a 7.96% CAGR as owners, designers, and contractors shift from adversarial, sequential handoffs toward shared-risk, shared-reward delivery structures. This growth is not merely a contractual trend; it reflects a structural reordering of how capital projects are governed, priced, and executed.
Future Prospects for Construction Integrated Project Delivery Market Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.522 B
2025
9.200 B
2026
9.932 B
2027
10.72 B
2028
11.58 B
2029
12.50 B
2030
13.49 B
2031
IPD is distinguished by early involvement of key participants, shared information environments, collaborative governance, and commercial arrangements that reward collective outcomes. While adoption remains uneven across regions and project types, the direction of travel is unmistakable. Projects with high interface complexity, tight schedules, and stringent sustainability requirements are increasingly unsuitable for traditional design-bid-build or construction-management-at-risk models. In these contexts, IPD offers a credible alternative.
Market size (2026): USD 9.2 billion in direct IPD-related services, software, and facilitation.
Forecast (2032): USD 17.65 billion, an 8.45 billion absolute increment.
CAGR (2026–2032):7.96%, outpacing the broader construction market's 4.70% CAGR.
Fastest-growing project type: Infrastructure, followed by commercial and institutional.
Leading service line: Construction management and consultancy, combined at over 55% of IPD-specific spend.
The market's expansion is being reinforced by digital interoperability, AI-assisted coordination, and public-sector procurement reform. However, the gap between IPD's promise and its practice remains a central theme. Our interviews with project owners and delivery leaders consistently highlight that contractual integration without behavioral and data integration yields limited benefit. The future of this market therefore depends less on the contract template and more on the capability stack: governance maturity, data standards, and collaborative competence.
Market Size, Forecast & Growth Trajectory
The IPD market is best understood as a subset of the broader construction technology and services ecosystem. Global construction technology spend is forecast to reach USD 325.3 billion by 2036 at a 7.1% CAGR, with software holding a 55.0% component share. IPD-specific spend represents a high-value, high-growth niche within that ecosystem, concentrated in consultancy, integrated project management, and collaborative software platforms.
Our bottom-up model triangulates project counts by delivery model, average IPD facilitation and software spend per project, and service-line attach rates. The resulting trajectory shows accelerating adoption from 2028 onward, driven by infrastructure megaprojects and public procurement modernization.
Metric
2026
2028
2030
2032
IPD market value (USD billion)
9.20
10.72
12.50
17.65
Year-on-year growth (%)
—
7.94
8.03
7.96
Share of global construction tech spend (%)
5.6
6.1
6.6
7.2
Cumulative added revenue 2026–2032 (USD billion)
—
—
—
8.45
Growth is not linear across segments. Infrastructure projects are expected to contribute over 40% of incremental revenue, reflecting the scale and interface complexity of transport, energy, and water programs. Commercial projects follow, particularly in North America and the Middle East, where owners are consolidating delivery partners and demanding integrated risk management. Institutional projects, including healthcare and education, are adopting IPD more slowly due to public procurement constraints.
Key Market Drivers
The adoption of IPD is being propelled by a confluence of structural, technological, and regulatory forces. Our primary research identifies five drivers with the highest impact on CAGR.
Project complexity and interface risk: Megaprojects routinely involve dozens of disciplines, vendors, and approval bodies. IPD's early involvement and shared decision rights reduce interface-driven delays. Interface complexity alone explains an estimated 1.8 percentage points of the market's growth.
Digital transformation and BIM maturity: Building information modeling, common data environments, and digital twins make integrated delivery operationally feasible. With construction management software growing at 8.99% CAGR, cloud-first platforms are becoming the connective tissue of IPD.
Sustainability and carbon accountability: Embodied-carbon reporting and green building certifications require integrated design and procurement decisions. IPD aligns these decisions across parties earlier in the lifecycle.
Public-sector procurement reform: Governments are piloting collaborative delivery models, particularly in the UK, Australia, and parts of the EU, where infrastructure investment is expected to reach USD 4 trillion annually.
Labor scarcity and productivity pressure: With skilled-labor shortages forcing productivity software uptake, IPD offers a governance mechanism to deploy digital tools effectively across project teams.
Restraints and the Expectation–Reality Gap
The single most important constraint on the IPD market is the persistent gap between expectation and reality. A systematic review of 56 studies published between 2018 and 2025 identified 11 expectation clusters and nine reality clusters, mapping the gap across collaborative practice, commercial and risk management, and governance and delivery domains. Our interviews corroborate these findings.
Contractual and legal immaturity: IPD contracts are often poorly understood, unevenly enforceable, and incompatible with standard insurance and liability regimes. Many owners revert to hybrid models that dilute integrated behavior.
Cultural and behavioral resistance: Collaborative governance requires decision rights to be shared, which challenges traditional hierarchies. Trust deficits and opportunistic behavior persist, particularly in fragmented supply chains.
Digital interoperability gaps: Common data environments are only as effective as the data standards behind them. Legacy point solutions and inconsistent naming conventions undermine shared information environments.
Procurement rules and public accountability: Public owners face audit and transparency requirements that discourage relational contracting. Procurement reform is progressing, but unevenly.
Capability asymmetry: Smaller contractors and regional firms often lack the digital maturity and collaborative training required for IPD participation.
These restraints exert a moderating effect on adoption, particularly in price-sensitive markets. Our model estimates that the expectation–reality gap caps the market's CAGR by approximately 1.5 to 2.0 percentage points relative to a frictionless adoption scenario.
Segmentation Analysis
By Project Type
Infrastructure leads IPD adoption by value, followed by commercial and institutional projects. Industrial projects present a smaller but growing segment, particularly in energy transition and advanced manufacturing facilities.
Project Type
2026 Share (%)
Growth Outlook (2026–2032)
Infrastructure
38
Fastest-growing; driven by transport and energy programs
Commercial
27
Strong growth in North America and GCC markets
Institutional
21
Moderate growth; constrained by public procurement rules
Industrial
14
Emerging growth in energy transition projects
By Service Type
Construction management and consultancy together account for over half of IPD-specific spend. Architectural and engineering services follow, with general contracting services representing a smaller but strategic share.
Construction management: Largest service line, benefiting from owners' demand for integrated schedule and cost control.
Consultancy: Fastest-growing, driven by IPD facilitation, contract design, and capability building.
Architectural and engineering: High-value design coordination services, increasingly bundled with digital delivery.
General contracting: Shifting toward collaborative contracting models in mature markets.
By Project Size
Large projects (above USD 500 million) dominate IPD value, while medium-sized projects (USD 50 million to USD 500 million) represent the fastest-growing volume segment. Our research shows that medium projects are increasingly adopting IPD principles through simplified relational contracts, often without formal IPD legal structures.
Regional Outlook
IPD adoption reflects procurement rules, regulatory frameworks, and digital maturity. North America leads in value, supported by advanced collaborative contracting practices and strong BIM adoption. Asia-Pacific is the fastest-growing region, driven by China's industrialized construction capabilities and India's rapid urbanization.
Future Prospects for Construction Integrated Project Delivery Market Regional Market Share
Loading chart...
North America (28% share): Mature collaborative contracting practices, strong legal and insurance ecosystems, but fragmented public procurement rules. The United States and Canada are key markets.
Europe (24% share): Mature sustainability and digital-construction requirements, with varied national contracting traditions. The UK and Nordic countries lead; Germany and France are advancing.
Asia-Pacific (31% share): Fastest-growing region. China combines extensive infrastructure activity with advanced industrialized construction. India's infrastructure pipeline and standardized information exchange requirements are creating new IPD opportunities.
Middle East & Africa (10% share): GCC countries are advancing coordinated delivery for large development programs. Africa faces capacity constraints but early coordination offers value.
South America (7% share): Brazil and Mexico are balancing public investment needs with uneven digital adoption. Contract clarity and capability development are central.
Country-level insights reinforce this picture. Australia and Canada have strong professional and digital foundations. The UK and US have substantial experience with collaborative contracting, though liability and stakeholder-alignment issues remain. Japan and South Korea bring sophisticated engineering and manufacturing ecosystems. India's growth is particularly notable, with construction technology adoption expanding at a double-digit pace.
Competitive Landscape and Strategic Developments
The IPD market is characterized by medium concentration, with construction technology and software vendors, engineering consultancies, and integrated delivery platforms competing for influence. Our research identifies the following strategic developments shaping competition.
Bentley Systems announced Bentley Infrastructure Cloud Connect (October 2025) to connect people and data across the infrastructure lifecycle, strengthening its position in integrated project information environments.
Autodesk announced that Autodesk Construction Cloud became Autodesk Forma (March 2026), placing construction capabilities within a wider design-and-construction cloud.
Procore announced its connected Common Data Environment (June 2026) initially for the UK and Ireland, linking project information with embedded Datagrid capabilities and agentic AI.
Trimble ProjectSight offers drawing and document management, RFI and submittal tracking, and AI-driven capabilities, with advanced cost and field management in paid plans.
Oracle Primavera Cloud supports scheduling and resource planning, reinforcing its role in integrated project controls.
Vendors are competing less on standalone features and more on workflow fit: the ability to connect the right information to the right decision-maker at the right time. This shifts competitive advantage toward platforms with open APIs, strong data governance, and field adoption. Consolidation is gathering pace as well-capitalized leaders acquire niche specialists to plug workflow gaps.
Value Chain and Procurement Dynamics
The IPD value chain spans owners, design professionals, construction managers, trade contractors, technology vendors, and specialty consultants. Value is created through integration rather than sequential handoffs. The following table summarizes the value chain and its implications for procurement.
Value Chain Stage
Key Participants
IPD Role
Procurement Implication
Owner/Client
Public and private owners
Sets outcomes, governance, and risk allocation
Must select partners on capability, not just price
Interoperability and data standards are selection criteria
The procurement shift is critical. Traditional lowest-price procurement undermines IPD by selecting for adversarial behavior. Leading owners are moving toward best-value procurement, early contractor involvement, and collaborative contract templates. However, public procurement rules remain a binding constraint in many markets.
Strategic White-Space Analysis
Our analysis identifies three white spaces with outsized growth potential.
Mid-market IPD enablement: Medium-sized projects (USD 50–500 million) are underserved by formal IPD contracts but demand collaborative delivery. Simplified relational contracts and standardized digital templates represent a significant opportunity.
AI-governed decision support: AI is extending IPD capabilities in design option analysis, constructability reviews, and schedule-risk identification. However, governed AI adoption—with human oversight and clear accountability—remains nascent. Vendors that build auditable AI workflows will capture premium value.
Emerging-market capability building: India, Southeast Asia, and parts of Africa require standardized information exchange and early multidisciplinary coordination. Training, certification, and lightweight digital platforms represent a high-growth adjacency.
Conclusion: Integration Is a Governance and Capability Discipline
The future prospects for the construction integrated project delivery market are strong but conditional. The USD 8.45 billion incremental opportunity through 2032 will not be captured by contract templates alone. It will be captured by organizations that treat IPD as a socio-technical and institutional system—one that requires digital interoperability, trust, aligned objectives, legal readiness, and early stakeholder integration. The market's 7.96% CAGR reflects growing recognition that integration is a governance and capability discipline, not merely a delivery model. Vendors, owners, and contractors that invest in collaborative competence and data quality will be best positioned to lead.
Future Prospects for Construction Integrated Project Delivery Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Future Prospects for Construction Integrated Project Delivery Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.96% from 2020-2034
Segmentation
By Project Type
Commercial
Industrial
Infrastructure
Institutional
By Service Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Project complexity and interface risk requiring early involvement
3.1.2. Digital transformation and BIM maturity enabling integrated delivery
3.1.3. Sustainability and carbon accountability mandates
3.1.4. Government infrastructure investments and procurement modernization
3.1.5. Labor scarcity and productivity pressure driving collaborative models
3.2. Market Trends
3.2.1. Shift from sequential handoffs to early coordination and integrated planning
3.2.2. AI-assisted coordination, constructability reviews, and schedule-risk identification
3.2.3. Growth of common data environments and digital twins in IPD projects
3.3.1. Contractual and legal immaturity of IPD agreements
3.3.2. Cultural and behavioral resistance to shared decision rights
3.3.3. Digital interoperability gaps among legacy point solutions
3.3.4. Public procurement rules limiting relational contracting
Architectural & Engineering
Construction Management
Consultancy
General Contracting
By Project Size
Large
Medium
Small
By Geography
North America
USA
Canada
Europe
UK
Germany
France
Italy
Spain
Asia Pacific
China
Japan
South Korea
India
Australia
Middle East & Africa
GCC
Africa
South America
Brazil
Mexico
3.4. Market Restraints
3.4.1. Contractual and legal immaturity of IPD agreements
3.4.2. Cultural and behavioral resistance to shared decision rights
3.4.3. Digital interoperability gaps among legacy point solutions
3.4.4. Public procurement rules limiting relational contracting
3.5. Market Challenges
3.5.1. Expectation–reality gap in IPD benefits realization
3.5.2. Capability asymmetry among smaller contractors
3.5.3. Insurance and liability regime incompatibility with IPD
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Project Type
5.1.1. Commercial
5.1.2. Industrial
5.1.3. Infrastructure
5.1.4. Institutional
5.2. Market Analysis, Insights and Forecast - by Service Type
5.2.1. Architectural & Engineering
5.2.2. Construction Management
5.2.3. Consultancy
5.2.4. General Contracting
5.3. Market Analysis, Insights and Forecast - by Project Size
5.3.1. Large
5.3.2. Medium
5.3.3. Small
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Middle East & Africa
5.4.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Project Type
6.1.1. Commercial
6.1.2. Industrial
6.1.3. Infrastructure
6.1.4. Institutional
6.2. Market Analysis, Insights and Forecast - by Service Type
6.2.1. Architectural & Engineering
6.2.2. Construction Management
6.2.3. Consultancy
6.2.4. General Contracting
6.3. Market Analysis, Insights and Forecast - by Project Size
6.3.1. Large
6.3.2. Medium
6.3.3. Small
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Project Type
7.1.1. Commercial
7.1.2. Industrial
7.1.3. Infrastructure
7.1.4. Institutional
7.2. Market Analysis, Insights and Forecast - by Service Type
7.2.1. Architectural & Engineering
7.2.2. Construction Management
7.2.3. Consultancy
7.2.4. General Contracting
7.3. Market Analysis, Insights and Forecast - by Project Size
7.3.1. Large
7.3.2. Medium
7.3.3. Small
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Project Type
8.1.1. Commercial
8.1.2. Industrial
8.1.3. Infrastructure
8.1.4. Institutional
8.2. Market Analysis, Insights and Forecast - by Service Type
8.2.1. Architectural & Engineering
8.2.2. Construction Management
8.2.3. Consultancy
8.2.4. General Contracting
8.3. Market Analysis, Insights and Forecast - by Project Size
8.3.1. Large
8.3.2. Medium
8.3.3. Small
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Project Type
9.1.1. Commercial
9.1.2. Industrial
9.1.3. Infrastructure
9.1.4. Institutional
9.2. Market Analysis, Insights and Forecast - by Service Type
9.2.1. Architectural & Engineering
9.2.2. Construction Management
9.2.3. Consultancy
9.2.4. General Contracting
9.3. Market Analysis, Insights and Forecast - by Project Size
9.3.1. Large
9.3.2. Medium
9.3.3. Small
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Project Type
10.1.1. Commercial
10.1.2. Industrial
10.1.3. Infrastructure
10.1.4. Institutional
10.2. Market Analysis, Insights and Forecast - by Service Type
10.2.1. Architectural & Engineering
10.2.2. Construction Management
10.2.3. Consultancy
10.2.4. General Contracting
10.3. Market Analysis, Insights and Forecast - by Project Size
10.3.1. Large
10.3.2. Medium
10.3.3. Small
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Autodesk
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Oracle
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Bentley Systems
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Procore Technologies
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Trimble
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Microsoft Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Topcon
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Hilti
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Caterpillar
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Hexagon
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Future Prospects for Construction Integrated Project Delivery Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Type 2026 & 2034
Figure 3: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Type 2026 & 2034
Figure 4: North America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Service Type 2026 & 2034
Figure 5: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Service Type 2026 & 2034
Figure 6: North America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Size 2026 & 2034
Figure 7: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Size 2026 & 2034
Figure 8: North America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Type 2026 & 2034
Figure 11: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Type 2026 & 2034
Figure 12: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Service Type 2026 & 2034
Figure 13: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Service Type 2026 & 2034
Figure 14: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Size 2026 & 2034
Figure 15: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Size 2026 & 2034
Figure 16: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Type 2026 & 2034
Figure 19: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Type 2026 & 2034
Figure 20: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Service Type 2026 & 2034
Figure 21: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Service Type 2026 & 2034
Figure 22: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Size 2026 & 2034
Figure 23: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Size 2026 & 2034
Figure 24: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Type 2026 & 2034
Figure 27: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Type 2026 & 2034
Figure 28: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Service Type 2026 & 2034
Figure 29: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Service Type 2026 & 2034
Figure 30: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Size 2026 & 2034
Figure 31: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Size 2026 & 2034
Figure 32: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Country 2026 & 2034
Figure 34: South America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Type 2026 & 2034
Figure 35: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Type 2026 & 2034
Figure 36: South America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Service Type 2026 & 2034
Figure 37: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Service Type 2026 & 2034
Figure 38: South America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Project Size 2026 & 2034
Figure 39: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Project Size 2026 & 2034
Figure 40: South America Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Type 2020 & 2034
Table 2: Global Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 3: Global Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Size 2020 & 2034
Table 4: Global Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Type 2020 & 2034
Table 6: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 7: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Size 2020 & 2034
Table 8: North America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Type 2020 & 2034
Table 12: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 13: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Size 2020 & 2034
Table 14: Europe Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: UK Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Germany Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: France Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Italy Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Spain Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Type 2020 & 2034
Table 21: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 22: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Size 2020 & 2034
Table 23: Asia Pacific Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 24: China Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Japan Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: South Korea Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: India Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Australia Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Type 2020 & 2034
Table 30: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 31: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Size 2020 & 2034
Table 32: Middle East & Africa Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 33: GCC Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Africa Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Type 2020 & 2034
Table 36: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 37: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Project Size 2020 & 2034
Table 38: South America Future Prospects for Construction Integrated Project Delivery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 39: Brazil Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Mexico Future Prospects for Construction Integrated Project Delivery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the future growth rate of the construction integrated project delivery market?
The market is projected to grow at a 7.96% CAGR from 2026 to 2032, expanding by USD 8.45 billion. This growth is driven by infrastructure megaprojects, digital interoperability, and procurement reform.
2Which region is expected to lead IPD adoption?
North America leads in market value with a 28% share, supported by advanced collaborative contracting practices. Asia-Pacific is the fastest-growing region, driven by China's industrialized construction and India's infrastructure pipeline.
3What are the main barriers to IPD implementation?
The primary barriers include contractual and legal immaturity, cultural resistance, digital interoperability gaps, and public procurement rules. These factors create an expectation–reality gap that moderates market growth by an estimated 1.5 to 2.0 percentage points.
4How does artificial intelligence impact integrated project delivery?
AI strengthens IPD by assisting with design option analysis, constructability reviews, schedule-risk identification, and document classification. Its value depends on reliable data structures, human review, and clear accountability for AI-assisted decisions.
5What project types are driving IPD market growth?
Infrastructure projects lead adoption with a 38% share, followed by commercial (27%) and institutional (21%). Medium-sized projects between USD 50 million and USD 500 million represent the fastest-growing volume segment.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our analysis is built on a 70–30 research split, with 70–80% of insights derived from primary research and 20–30% from secondary sources. Primary research includes structured interviews with 120+ industry stakeholders across the IPD value chain.
We conduct in-depth interviews with construction managers, IPD facilitators, owner representatives, and technology providers to capture project-level economics and adoption barriers.
Company types surveyed include integrated design-build contractors, specialty trade contractors, construction management consultancies, BIM and common data environment software vendors, and project owners/developers.
Stakeholder job titles interviewed include Chief Delivery Officer, Project Director, IPD Facilitator, and Head of Digital Construction.
We validate findings through multi-level data triangulation, cross-checking interview data with project-level procurement records and contract templates.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Project Director
30%
Chief Delivery Officer
25%
IPD Facilitator
25%
Head of Digital Construction
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Integrated design-build contractors
30%
Construction management consultancies
25%
BIM and CDE software vendors
20%
Specialty trade contractors
15%
Project owners and developers
10%
Secondary Research & Industry Benchmarking
Secondary research draws on official multilateral sources, including the World Bank, OECD, and UN Comtrade, as well as recognized non-profit technical standards bodies and industry trade associations.
We benchmark against publicly available construction investment data, infrastructure spending forecasts, and digital-construction adoption metrics from government agencies and standards organizations.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to validate vendor financials, M&A activity, and market consolidation trends.
Every report is updated to the date of purchase to reflect the latest procurement reforms, technology releases, and project announcements.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously. The top-down model sizes the IPD market as a share of global construction technology and services spend, cross-validated against project counts.
The bottom-up model triangulates project counts by delivery model, average IPD facilitation and software spend per project, service-line attach rates, and regional adoption indices.
Specific quantitative metrics include the number of active IPD projects by region, average IPD service spend per project (USD), software attach rate per project, and the share of projects using collaborative contracts.
Demand modeling is segmented by project type, service type, project size, and region, with separate growth trajectories for each segment.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-level data triangulation and iterative validation.
All market sizes and CAGRs are cross-checked against at least three independent data sources, including project-level records, procurement data, and financial disclosures.
Quality assurance protocols include outlier detection, sensitivity analysis on key assumptions, and expert review of all segment-level estimates.
Regional estimates are validated through country-level interviews and cross-referenced with official infrastructure investment data from multilateral institutions.