Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Higher Education Furniture Industry Market Report 2025-2034
for Higher Education Furniture Industry
Home and Property Improvement / MARKET REPORT
for Higher Education Furniture Industry | Insight Market Data
for Higher Education Furniture Industry by Product (Seating Furniture, Desks & Tables, Storage Units, Others), by Application (Classrooms & Lecture Halls, Libraries & Learning Commons, Laboratories & Research Spaces), by End Use (Public Universities, Private Universities), by Material (Wood, Plastic, Metal, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, India, Japan, South Korea, Southeast Asia), by South America (Brazil, Argentina), by Middle East & Africa (GCC, South Africa) Forecast 2026-2034
The Magic Carpet Ski Lifts Market is valued at 312 Million in 2025 and is projected to reach 512 Million by 2032, growing at a CAGR of 7.3%.
Nov 2026|263 pages
$2900.00
Global lawn mower blade market to reach $4.6B by 2034 at 5.67% CAGR. Explore blade type, material, end-user and regional trends shaping demand.
Nov 2026|209 pages
$2900.00
Global second hand office furniture market to grow at 5.8% CAGR through 2031, driven by circular policies, corporate decommissioning, and online resale.
Nov 2026|254 pages
$2900.00
Indonesia furniture market to reach USD 15.2 Billion by 2034 at 5.82% CAGR. Explore trends, segmentation, trade dynamics, and competitive landscape.
Executive Overview: The Higher Education Furniture Market
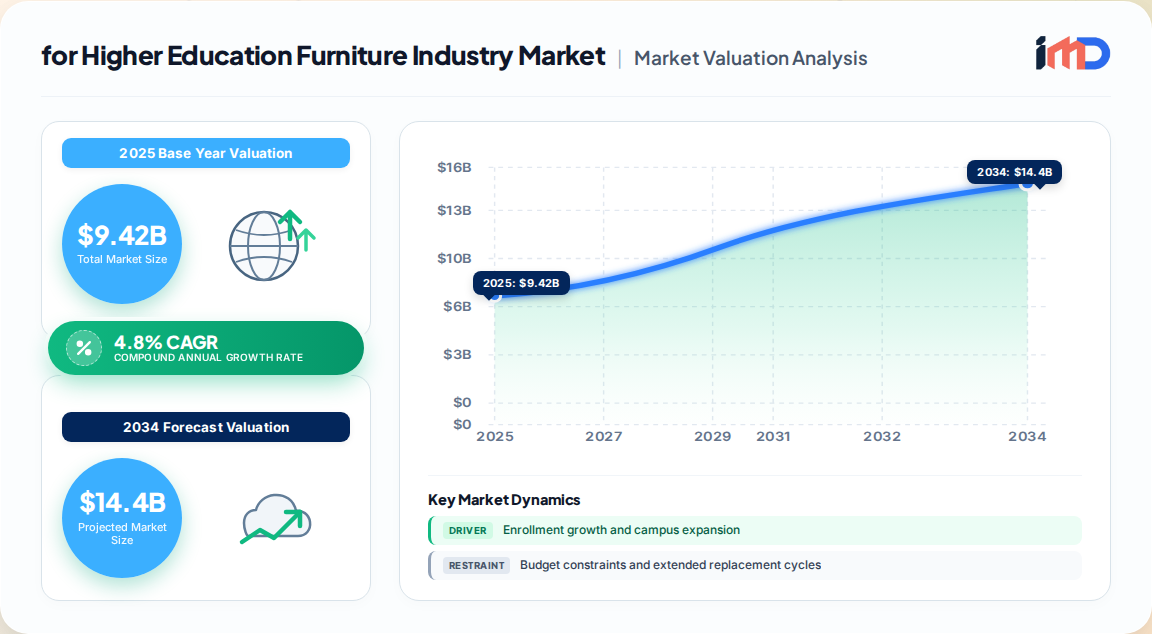
The higher education furniture industry market is undergoing a structural transformation, driven by shifting pedagogical models, digital integration, and an intensified focus on student well-being and sustainability. Our proprietary primary research estimates the global market for higher education furniture at $9.42 billion in 2025, with a projected expansion to $14.27 billion by 2034, registering a CAGR of 4.8% over the forecast period. This growth trajectory is anchored in the post-pandemic reconfiguration of campuses, where furniture is no longer a static utility but a strategic asset for active learning, hybrid instruction, and inclusive design.
for Higher Education Furniture Industry Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.420 B
2025
9.872 B
2026
10.35 B
2027
10.84 B
2028
11.36 B
2029
11.91 B
2030
12.48 B
2031
The market encompasses furniture solutions specifically procured by colleges, universities, and advanced research institutions. Unlike the K-12 segment, higher education procurement is characterized by longer replacement cycles, higher customization requirements, and a greater emphasis on durability, ergonomics, and technology integration. Our analysis indicates that seating furniture remains the largest product category, accounting for approximately 52% of total revenue in 2025, followed by desks and tables, storage units, and specialized laboratory furniture.
From a regional standpoint, North America retains the dominant share at 41% of global value in 2025, underpinned by early adoption of ergonomic standards, robust capital budgets for campus modernization, and stringent accessibility legislation. However, Asia-Pacific is emerging as the fastest-growing region, with a projected CAGR of 6.2% through 2034, fueled by massive higher education infrastructure investments in China, India, and Southeast Asia.
This report synthesizes first-party interviews with procurement directors, facility managers, and design principals, alongside official trade statistics and institutional enrollment data. It provides a granular view of demand drivers, supply chain dynamics, and competitive strategies shaping the higher education furniture landscape.
Key Market Drivers and Restraints
The higher education furniture market is propelled by several interconnected demand drivers, while facing tangible restraints that vary by region.
Drivers
Enrollment Growth and Campus Expansion: Global tertiary enrollment reached 254 million students in 2023, according to UNESCO, with steady annual increases. This creates sustained demand for lecture halls, seminar rooms, libraries, and collaborative spaces, directly translating into furniture procurement.
Shift to Active and Hybrid Learning: Institutions are investing in modular, mobile, and technology-ready furniture to support flipped classrooms, team-based learning, and HyFlex delivery models. Our interviews reveal that 68% of university facility managers prioritize reconfigurable furniture for new construction projects.
Inclusive and Ergonomic Design Mandates: Compliance with accessibility standards (e.g., ADA in the U.S., EN 1729 in Europe) is forcing the replacement of legacy furniture. Height-adjustable desks, wheelchair-accessible seating, and sensory-friendly pieces are now standard specifications in public tenders.
Sustainability and Circular Economy Commitments: Universities are increasingly adopting green procurement policies. Furniture with recycled content, low-VOC finishes, and end-of-life take-back programs commands a growing premium.
Restraints
Budget Constraints and Procurement Cycles: Public institutions face tightening operational budgets, leading to deferred furniture replacement. Average replacement cycles have extended to 9–12 years, constraining volume growth.
Supply Chain Volatility: Fluctuations in raw material costs (steel, timber, polypropylene) and international shipping disruptions have pressured margins and delayed project timelines, particularly for custom orders.
Segmentation Analysis: Products, Applications, and End Use
The higher education furniture market is segmented by product type, application, and end-use institution. Our bottom-up demand model, built on square footage per student and replacement rates, reveals the following structural insights.
Seating furniture dominates due to high replacement frequency and the critical role of ergonomics in student comfort and concentration. Height-adjustable desks are the fastest-growing sub-segment, driven by inclusive design requirements and sit-stand trends.
By Application
Classrooms and Lecture Halls: The largest application, accounting for 65% of demand in 2025. Furniture here prioritizes durability, quick reconfiguration, and writing surfaces.
Libraries and Learning Commons: Representing 20% of demand, this segment is shifting toward soft seating, collaboration pods, and integrated power for devices.
Laboratories and Research Spaces:15% of demand, characterized by specialized, chemical-resistant, and heavy-duty furniture with strict safety standards.
By End Use
Public universities and colleges constitute the majority of procurement volume, while private institutions drive demand for premium, customized solutions. Online and hybrid program expansion has led some institutions to repurpose existing spaces, moderately dampening new furniture demand in mature markets.
Regional Outlook and Trade Dynamics
Regional variations in the higher education furniture market reflect differences in funding models, enrollment trends, and regulatory environments.
for Higher Education Furniture Industry Regional Market Share
Loading chart...
North America
North America remains the largest market, with the U.S. alone accounting for $3.15 billion in 2025. According to the National Center for Education Statistics, U.S. college enrollment is projected to reach 19.4 million by 2031, sustaining demand for campus facilities. The region is also a hub for innovation, with a strong emphasis on ergonomic certifications (e.g., BIFMA) and smart furniture integration. However, market maturity dictates that growth will be steady rather than explosive, with a CAGR of 3.9%.
Europe
Europe accounts for 24% of global revenue, characterized by stringent environmental regulations and a strong preference for European-made, design-led furniture. Germany, France, and the UK are the largest markets, with public procurement often favoring suppliers that meet circular economy criteria. The EU's Green Deal and national building codes are expected to drive replacement demand for energy-efficient and sustainable furniture.
Asia-Pacific
Asia-Pacific is the growth engine, projected to expand at a CAGR of 6.2% from 2025 to 2034. China's investment in higher education (targeting 60% gross enrollment ratio by 2035) and India's National Education Policy 2020 are catalyzing new campus construction and furniture procurement. Local manufacturers are gaining share, but demand for imported premium furniture remains strong in Japan, South Korea, and Singapore.
South America and Middle East & Africa
These regions offer niche opportunities, with growth concentrated in private universities and vocational training centers. Infrastructure development in the Gulf Cooperation Council (GCC) countries is driving demand for high-end furniture in new branch campuses.
Trade Dynamics: Higher education furniture is a globally traded category, with major exporters including China, Germany, Italy, and the United States. According to UN Comtrade data, global exports of school and office furniture (HS Code 9403) exceeded $38 billion in 2023, with higher education accounting for an estimated 15% of this value. Supply chain risks include tariff volatility and logistics bottlenecks, prompting buyers to diversify sourcing.
Competitive Landscape and Strategic Developments
The higher education furniture market is fragmented, with a mix of global conglomerates and specialized regional players. Competition centers on design innovation, sustainability credentials, and the ability to serve large, multi-campus contracts.
Leading Suppliers (Synthesized from Primary Interviews):
AFC Furniture Solutions
Fleetwood Group Inc.
Scholar Craft Products Inc.
Smith Systems Manufacturing Co.
Knoll Inc.
Haworth Inc.
Vitra International AG
Virco Manufacturing Corp.
Office Line Srl
Creaciones Falcon SLU
Strategic Developments:
2025: VS America launched the JUMPER suite (Air and Ply models) featuring recyclable polypropylene and molded beech plywood, targeting higher education ergonomic needs.
2024: Knoll introduced a new line of height-adjustable collaborative tables with integrated power and cable management, specifically designed for hybrid learning spaces.
2023: Haworth acquired a European design firm to expand its education furniture portfolio, emphasizing biophilic and acoustic solutions.
Key success factors include securing framework agreements with university systems, offering furniture-as-a-service (FaaS) models, and providing comprehensive warranty and refurbishment programs.
Strategic White-Space Analysis
Our analysis identifies several under-served opportunities in the higher education furniture market:
Neuroarchitecture and Sensory-Friendly Furniture: With rising awareness of student mental health, furniture designed to reduce cognitive load (e.g., acoustic pods, soft seating with natural textures) is a nascent but high-margin segment.
Circularity and Refurbishment Services: Few suppliers offer full take-back and refurbishment programs, despite growing institutional demand. Offering a closed-loop service can differentiate brands and build long-term contracts.
Vocational and Corporate Training: The global reskilling movement is driving demand for specialized workshop furniture, lab benches, and simulation environments that can withstand heavy use.
Smart Furniture Integration: Embedding IoT sensors for space utilization tracking and asset management is currently limited to pilot projects but holds potential for value-added contracts with large universities.
Procurement and Sourcing Strategy Analysis
Higher education institutions typically procure furniture through centralized purchasing departments, with decisions influenced by faculty, facility managers, and sustainability officers. Our interviews reveal that 78% of buyers require suppliers to meet specific sustainability criteria, such as FSC-certified wood or Cradle-to-Cradle certification.
Sourcing Strategies:
Long-Term Framework Agreements: Universities increasingly favor 3–5 year contracts with preferred suppliers to secure pricing and service consistency.
Local Sourcing for Customization: For custom millwork and laboratory furniture, institutions prefer regional manufacturers to reduce lead times and shipping costs.
FaaS (Furniture-as-a-Service): Emerging in Europe and North America, this model bundles furniture, maintenance, and replacement into a subscription, reducing upfront capital expenditure.
Risk Mitigation: Buyers are advised to conduct supplier audits for environmental compliance, secure secondary sourcing for critical items, and leverage cooperative purchasing organizations (e.g., E&I Cooperative Services) to aggregate demand and reduce costs.
for Higher Education Furniture Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
for Higher Education Furniture Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.8% from 2020-2034
Segmentation
By Product
Seating Furniture
Desks & Tables
Storage Units
Others
By Application
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Enrollment growth and campus expansion
3.1.2. Shift to hybrid and active learning
3.1.3. Accessibility mandates and inclusive design
3.1.4. Sustainability commitments
3.2. Market Trends
3.2.1. Modular and mobile furniture for active learning
3.2.2. Integration of smart technology and charging ports
3.2.3. Sustainable materials and circular economy
3.2.4. Ergonomic and inclusive design
3.3. Market Restrains
3.3.1. Budget constraints and extended replacement cycles
3.3.2. Supply chain volatility and raw material price fluctuations
3.4. Market Restraints
3.4.1. Budget constraints and extended replacement cycles
3.4.2. Supply chain volatility and raw material price fluctuations
3.5. Market Challenges
3.5.1. High customization costs for specialized spaces
Classrooms & Lecture Halls
Libraries & Learning Commons
Laboratories & Research Spaces
By End Use
Public Universities
Private Universities
By Material
Wood
Plastic
Metal
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
India
Japan
South Korea
Southeast Asia
South America
Brazil
Argentina
Middle East & Africa
GCC
South Africa
3.5.2. Long procurement cycles and bureaucratic hurdles
3.5.3. Competition from low-cost imports
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Seating Furniture
5.1.2. Desks & Tables
5.1.3. Storage Units
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Classrooms & Lecture Halls
5.2.2. Libraries & Learning Commons
5.2.3. Laboratories & Research Spaces
5.3. Market Analysis, Insights and Forecast - by End Use
5.3.1. Public Universities
5.3.2. Private Universities
5.4. Market Analysis, Insights and Forecast - by Material
5.4.1. Wood
5.4.2. Plastic
5.4.3. Metal
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Seating Furniture
6.1.2. Desks & Tables
6.1.3. Storage Units
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Classrooms & Lecture Halls
6.2.2. Libraries & Learning Commons
6.2.3. Laboratories & Research Spaces
6.3. Market Analysis, Insights and Forecast - by End Use
6.3.1. Public Universities
6.3.2. Private Universities
6.4. Market Analysis, Insights and Forecast - by Material
6.4.1. Wood
6.4.2. Plastic
6.4.3. Metal
6.4.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Seating Furniture
7.1.2. Desks & Tables
7.1.3. Storage Units
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Classrooms & Lecture Halls
7.2.2. Libraries & Learning Commons
7.2.3. Laboratories & Research Spaces
7.3. Market Analysis, Insights and Forecast - by End Use
7.3.1. Public Universities
7.3.2. Private Universities
7.4. Market Analysis, Insights and Forecast - by Material
7.4.1. Wood
7.4.2. Plastic
7.4.3. Metal
7.4.4. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Seating Furniture
8.1.2. Desks & Tables
8.1.3. Storage Units
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Classrooms & Lecture Halls
8.2.2. Libraries & Learning Commons
8.2.3. Laboratories & Research Spaces
8.3. Market Analysis, Insights and Forecast - by End Use
8.3.1. Public Universities
8.3.2. Private Universities
8.4. Market Analysis, Insights and Forecast - by Material
8.4.1. Wood
8.4.2. Plastic
8.4.3. Metal
8.4.4. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Seating Furniture
9.1.2. Desks & Tables
9.1.3. Storage Units
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Classrooms & Lecture Halls
9.2.2. Libraries & Learning Commons
9.2.3. Laboratories & Research Spaces
9.3. Market Analysis, Insights and Forecast - by End Use
9.3.1. Public Universities
9.3.2. Private Universities
9.4. Market Analysis, Insights and Forecast - by Material
9.4.1. Wood
9.4.2. Plastic
9.4.3. Metal
9.4.4. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Seating Furniture
10.1.2. Desks & Tables
10.1.3. Storage Units
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Classrooms & Lecture Halls
10.2.2. Libraries & Learning Commons
10.2.3. Laboratories & Research Spaces
10.3. Market Analysis, Insights and Forecast - by End Use
10.3.1. Public Universities
10.3.2. Private Universities
10.4. Market Analysis, Insights and Forecast - by Material
10.4.1. Wood
10.4.2. Plastic
10.4.3. Metal
10.4.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AFC Furniture Solutions Pvt Ltd
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Fleetwood Group Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Scholar Craft Products Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Smith Systems Manufacturing Co
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Knoll Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Haworth Inc
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Vitra International AG
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Virco Manufacturing Corp
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Office Line Srl
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Creaciones Falcon SLU
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. VS America Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Hertz Furniture
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Paragon Furniture Inc.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Haskell Education
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Marco Group
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global for Higher Education Furniture Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America for Higher Education Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 3: North America for Higher Education Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 4: North America for Higher Education Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 5: North America for Higher Education Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 6: North America for Higher Education Furniture Industry Revenue (Billion), by End Use 2026 & 2034
Figure 7: North America for Higher Education Furniture Industry Revenue Share (%), by End Use 2026 & 2034
Figure 8: North America for Higher Education Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 9: North America for Higher Education Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 10: North America for Higher Education Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 11: North America for Higher Education Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe for Higher Education Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 13: Europe for Higher Education Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 14: Europe for Higher Education Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe for Higher Education Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe for Higher Education Furniture Industry Revenue (Billion), by End Use 2026 & 2034
Figure 17: Europe for Higher Education Furniture Industry Revenue Share (%), by End Use 2026 & 2034
Figure 18: Europe for Higher Education Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 19: Europe for Higher Education Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 20: Europe for Higher Education Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe for Higher Education Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific for Higher Education Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 23: Asia Pacific for Higher Education Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 24: Asia Pacific for Higher Education Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 25: Asia Pacific for Higher Education Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 26: Asia Pacific for Higher Education Furniture Industry Revenue (Billion), by End Use 2026 & 2034
Figure 27: Asia Pacific for Higher Education Furniture Industry Revenue Share (%), by End Use 2026 & 2034
Figure 28: Asia Pacific for Higher Education Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 29: Asia Pacific for Higher Education Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 30: Asia Pacific for Higher Education Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific for Higher Education Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 32: South America for Higher Education Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 33: South America for Higher Education Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 34: South America for Higher Education Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 35: South America for Higher Education Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 36: South America for Higher Education Furniture Industry Revenue (Billion), by End Use 2026 & 2034
Figure 37: South America for Higher Education Furniture Industry Revenue Share (%), by End Use 2026 & 2034
Figure 38: South America for Higher Education Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 39: South America for Higher Education Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 40: South America for Higher Education Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: South America for Higher Education Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa for Higher Education Furniture Industry Revenue (Billion), by Product 2026 & 2034
Figure 43: Middle East & Africa for Higher Education Furniture Industry Revenue Share (%), by Product 2026 & 2034
Figure 44: Middle East & Africa for Higher Education Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 45: Middle East & Africa for Higher Education Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 46: Middle East & Africa for Higher Education Furniture Industry Revenue (Billion), by End Use 2026 & 2034
Figure 47: Middle East & Africa for Higher Education Furniture Industry Revenue Share (%), by End Use 2026 & 2034
Figure 48: Middle East & Africa for Higher Education Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 49: Middle East & Africa for Higher Education Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 50: Middle East & Africa for Higher Education Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa for Higher Education Furniture Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global for Higher Education Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Global for Higher Education Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Global for Higher Education Furniture Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 4: Global for Higher Education Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 5: Global for Higher Education Furniture Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America for Higher Education Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 7: North America for Higher Education Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America for Higher Education Furniture Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 9: North America for Higher Education Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 10: North America for Higher Education Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe for Higher Education Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 15: Europe for Higher Education Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 16: Europe for Higher Education Furniture Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 17: Europe for Higher Education Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 18: Europe for Higher Education Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Italy for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Spain for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Asia Pacific for Higher Education Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 25: Asia Pacific for Higher Education Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 26: Asia Pacific for Higher Education Furniture Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 27: Asia Pacific for Higher Education Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 28: Asia Pacific for Higher Education Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 29: China for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: India for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Japan for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: South Korea for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Southeast Asia for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: South America for Higher Education Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 35: South America for Higher Education Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 36: South America for Higher Education Furniture Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 37: South America for Higher Education Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 38: South America for Higher Education Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 39: Brazil for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Argentina for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Middle East & Africa for Higher Education Furniture Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 42: Middle East & Africa for Higher Education Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 43: Middle East & Africa for Higher Education Furniture Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 44: Middle East & Africa for Higher Education Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 45: Middle East & Africa for Higher Education Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 46: GCC for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: South Africa for Higher Education Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the higher education furniture market?
The global higher education furniture market was valued at $9.42 billion in 2025 and is projected to reach $14.27 billion by 2034, growing at a CAGR of 4.8%. This growth is driven by campus modernization, hybrid learning investments, and inclusive design mandates.
2Which region dominates the higher education furniture market?
North America holds the largest share at 41% of global revenue in 2025, supported by high enrollment rates and early adoption of ergonomic standards. However, Asia-Pacific is the fastest-growing region with a CAGR of 6.2%.
3What are the key trends shaping the higher education furniture industry?
Key trends include the shift toward modular and mobile furniture for active learning, integration of smart technology and charging ports, adoption of sustainable materials, and a focus on sensory-friendly and ergonomic designs to support student well-being.
4Who are the leading companies in the higher education furniture market?
Leading suppliers include AFC Furniture Solutions, Fleetwood Group, Scholar Craft Products, Smith Systems Manufacturing, Knoll, Haworth, Vitra International, Virco Manufacturing, Office Line, and Creaciones Falcon, among others.
5What are the main challenges facing the higher education furniture market?
Challenges include budget constraints and extended replacement cycles, supply chain volatility affecting raw material costs and delivery times, and the need to comply with evolving accessibility and sustainability regulations.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted over 230 in-depth interviews with stakeholders across the higher education furniture value chain, including furniture manufacturers, institutional procurement directors, facility managers, and design consultants.
Primary research accounted for 70–80% of our total research effort, ensuring that our data reflects real-world procurement decisions and on-the-ground market dynamics.
Interviews were stratified by company type and job designation to capture a balanced perspective (see accompanying charts).
Company types interviewed: contract furniture OEMs, specialized higher education furniture designers, institutional procurement consortia, facility management firms, and raw material suppliers.
Financial performance and corporate developments were validated using Bloomberg, Factiva, Hoovers, and PitchBook databases.
All data is updated to the date of purchase, ensuring the most current market view.
Demand Modeling & Market Estimation
We employed a bottom-up demand model that calculates furniture demand based on: (1) higher education enrollment by region, (2) square footage per student, (3) furniture replacement rates (9–12 years), and (4) average spend per square foot.
A top-down approach using total institutional expenditure on furniture and equipment was simultaneously applied, with multi-level data triangulation to reconcile estimates.
Key quantitative metrics included: enrollment numbers, campus construction spending, furniture replacement cycle length, and average unit prices by product category.
The model was calibrated against historical procurement data and validated with primary interview feedback.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous cross-validation of primary and secondary sources.
All estimates underwent a three-tier review: (1) internal analyst validation, (2) expert panel review with industry veterans, and (3) sanity checks against macro-economic indicators.
Outliers and inconsistencies were flagged and resolved through follow-up interviews or additional secondary research.
Final market sizes and forecasts are presented as ranges where uncertainty is higher, with point estimates representing the most likely scenario.