1What is the fire fighting aircraft market size in 2026?
Our proprietary research values the global fire fighting aircraft market at USD 5.16 billion in 2026, up from USD 4.80 billion in 2025, and projects it to reach USD 9.80 billion by 2035.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Fire Fighting Aircraft Market
 by Aircraft Type (Fixed-Wing Air Tankers, Amphibious Scoopers, Rotorcraft/Helicopters, Multi-Mission Aircraft, UAS), by Water Tanking Capacity (Less than 10, 000 liters, 10, 000 to 30, 000 liters, More than 30, 000 liters), by Maximum Take-off Weight (Less than 8, 000 kg, 8, 000 to 30, 000 kg, More than 30, 000 kg), by Range (Less than 1, 000 km, 1, 000 to 3, 000 km, More than 3, 000 km), by Application (Fire Suppression, Surveillance and Fire Mapping, Search and Rescue, Logistics Support), by End User (Government and Forestry Agencies, Private Aerial Firefighting Operators, Military Forces), by Ownership and Operation Model (Public Fleet, Contractor-Operated, Leasing, Mixed Availability Contract), by North America (USA, Canada, Mexico), by Europe (Germany, France, Spain, Italy, Greece, Portugal), by Asia Pacific (China, Japan, Australia, Indonesia, India), by Latin America (Brazil, Chile, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034


Research Associate
 Related Reports

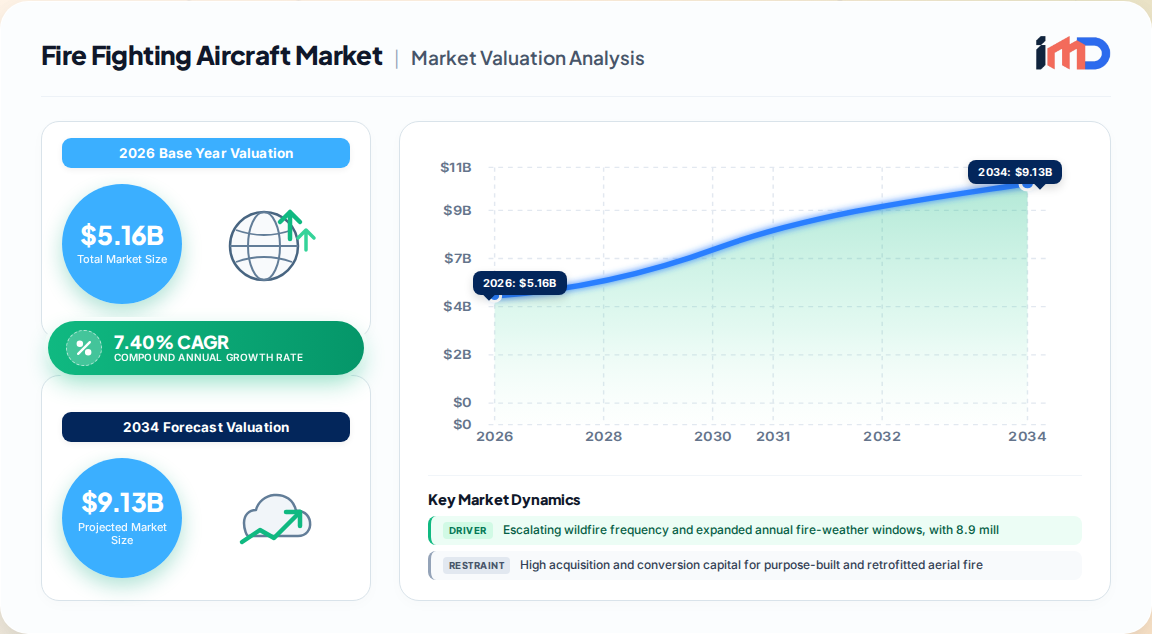
The global fire fighting aircraft market has crossed an inflection point from a seasonal, call-when-needed emergency procurement model into a year-round aviation-readiness system built around pre-positioned capacity, detection, suppression, and post-fire assessment. Our proprietary primary research and expert interviews place the market at USD 5.16 billion in 2026, expanding to USD 9.80 billion by 2035 at a 7.40% CAGR (2026–2035).
The most consequential signal is not headline growth but the change in what buyers are purchasing. Agencies increasingly contract availability — maintenance, crew retention, and deployability — rather than sortie completions alone. This re-prices fleet-planning economics and widens the addressable service base beyond peak suppression activity.
Demand fundamentals are unambiguous. In 2024, 64,897 wildfires burned 8.9 million acres across the United States, above both the five- and ten-year averages, according to National Interagency Fire Center statistics. Sustained baseline uplift in suppression contract values is expected through 2027, with UAS-assisted early-detection contracts growing fastest through 2030.
On the public-procurement side, the European Union allocated €600 million in March 2024 to purchase 12 new firefighting aircraft for its rescEU strategic reserve, distributed across six member states, with first deliveries expected in 2026–2027. This locks in long-cycle demand for amphibious scoopers and fixed-wing surveillance platforms and strengthens leasing and conversion services demand through 2028.
Supply cannot respond at the same velocity:
| Driver | Evidence Signal | Forecast Implication |
|---|---|---|
| Expanded fire-weather windows | 8.9 million U.S. acres burned in 2024, above 5- and 10-year averages | Sustained suppression contract value uplift through 2027 |
| Committed government procurement | €600M rescEU allocation for 12 aircraft (March 2024) | Above-average European growth through 2028 |
| Autonomous UAS certification | FAA Part 107/Part 135 and EASA 2018/1139 opt-in pathways | UAS share rises materially by 2030 |
| Capital and crew constraints | Conversion financing complexity; pilot shortage | Top-five concentration unlikely to ease before 2030 |
Fixed-wing platforms lead the market at approximately 54–62% share, reflecting superior payload capacity and single-mission area coverage. Amphibious scoopers represent the fastest-growing airframe category because water-body refill capability eliminates return-to-base turnaround. Rotorcraft hold a durable role in wildland-urban interface precision drops and confined-space operations.
| Segment | Leading Category | Share / Growth Signal |
|---|---|---|
| Aircraft Type | Fixed-wing air tankers | ~54–62% share; scooper fastest-growing |
| Water Tanking Capacity | Above 10,000 liters | ~42–47% share; 5,000–10,000 L fastest-growing |
| Maximum Take-off Weight | 8,000–30,000 kg medium | ~53% share |
| Range | Under 1,000 km | ~44% share; decentralized strategy driven |
| Application | Fire suppression | ~50–62% share; surveillance and mapping fastest-growing |
| End User | Government and forestry agencies | ~59–65% share; private operators fastest-growing |
| Ownership Model | Public fleet plus contractor | Multi-year availability contracting rising |
Multi-role modularity is the emerging segmentation theme: airframes configured to switch between firefighting, search and rescue, and disaster relief improve year-round asset utilization and underwrite operator capital recovery.
North America remains the dominant theater at roughly 42–47% of global value, supported by federal and state fleet modernization, an entrenched contractor base, and the highest historical wildfire loss exposure. The U.S. alone represents a substantial majority of regional spend.
Europe is the most policy-driven growth region outside North America. The rescEU reserve, bilateral government-to-government transactions, and national fleet recapitalization create a durable forward pipeline for amphibious aircraft, plus associated conversion, training, and maintenance demand.
Asia-Pacific is the fastest-growing region, expanding at a high-single-digit pace as Australia, Indonesia, and Southeast Asian markets formalize aerial fire programs. Latin America and the Middle East & Africa remain project-driven, with oil and gas, mining, and industrial fire response representing a distinct demand pocket alongside forestry.
| Region | Position | Structural Characteristic |
|---|---|---|
| North America | Largest, ~42–47% | Contractor-heavy, multi-year contracting, highest loss exposure |
| Europe | Above-average growth | Public reserve build-out, G2G procurement, amphibious bias |
| Asia-Pacific | Fastest growing | Program formalization, fragmented fleet base, high conversion runway |
| Latin America | Project-driven | Seasonal leasing, agricultural and industrial fire demand |
| Middle East & Africa | Niche growth | Oil and gas infrastructure protection, industrial response |
The operator landscape is moderately fragmented at the platform level but highly concentrated in large airtanker and scooper capability. The leading five operators collectively held approximately 37% of market share in 2025, with the market leader holding over 11%. Concentration is unlikely to ease before 2030 given capital and crew barriers.
Winning strategies we observe in primary interviews cluster into four archetypes:
Partnerships between airframe OEMs and fire management agencies are increasingly shaping regional variant design, while eco-friendly retardant formulations and lower-emission propulsion compliance emerge as procurement differentiators.
The value chain is capital-weighted upstream and availability-weighted downstream. Airframe OEMs and conversion houses control supply; mission-system suppliers set capability differentiation; operators monetize through availability contracts; agencies and insurers ultimately fund the chain.
Procurement is shifting toward performance-based availability awards. Buyers increasingly score bidders on guaranteed response time, pre-positioned basing, and verified crew depth rather than unit pricing alone.
Three white spaces stand out for investors and operators over the forecast horizon:
Risk remains weighted to financing conditions, certification pace, and airframe delivery slippage. Operators with committed multi-year backlogs and diversified mission portfolios are best positioned to compound returns through 2035.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.40% from 2020-2034 |
| Segmentation |
|
By Water Tanking Capacity
By Maximum Take-off Weight
By Range
By Application
By End User
By Ownership and Operation Model
| By Geography |
|
Our proprietary research values the global fire fighting aircraft market at USD 5.16 billion in 2026, up from USD 4.80 billion in 2025, and projects it to reach USD 9.80 billion by 2035.
The market is forecast to expand at a 7.40% CAGR between 2026 and 2035, driven by expanded fire-weather windows, multi-year government procurement, and UAS-enabled detection demand.
North America holds the largest share at roughly 42–47% of global value, anchored by U.S. federal and state fleet modernization and a mature contractor base, while Asia-Pacific is the fastest-growing region.
Fixed-wing air tankers lead with approximately 54–62% share due to payload capacity and area coverage, while amphibious scoopers are the fastest-growing category because they refill directly from water bodies.
Leading operators and OEMs include Conair Group, Erickson Inc., Coulson Aviation, Babcock International, 10 Tanker Air Carrier, Bombardier, Airbus, Lockheed Martin, Textron Aviation, De Havilland Canada, ShinMaywa, Kaman, and Leonardo; the top five operators held about 37% share in 2025.
High acquisition and conversion capital, aircraft delivery delays, and a specialized pilot shortage cap how quickly contracted capacity can be activated, keeping operator concentration elevated through 2030.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Fleet Operations Director | 30% |
| Government Procurement Officer | 25% |
| Chief Pilot / Wildland Training Lead | 25% |
| Mission Systems Engineering Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Aerial Firefighting Operators and Contractors | 30% |
| Aircraft OEMs and Conversion Houses | 22% |
| Mission Systems and Avionics Integrators | 18% |
| Government and Forestry Procurement Agencies | 20% |
| UAS and Sensor Solution Providers | 10% |