1What is the market size of the Film and Television Stage Lights Market in 2025?
The market is estimated at USD 1.90 Billion in 2025, and it is projected to reach USD 3.43 Billion by 2035, growing at a CAGR of 6.1%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Film and Television Stage Lights Market
 by Light Source (LED, Laser, Discharge, Halogen), by Product Type (Moving Head Lights, Spotlights, Floodlights, Strip Lights, PAR Can Lights, Lighting Consoles and Controllers), by Application (Television and Film Studios, Concerts and Live Events, Theaters, Nightclubs and Venues, Architectural and Retail), by Distribution Channel (Direct Sales, Distributors and Dealers, Online), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Australia, Rest of APAC), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (GCC, South Africa, Rest of MEA) Forecast 2026-2034
Research Associate


 Related Reports

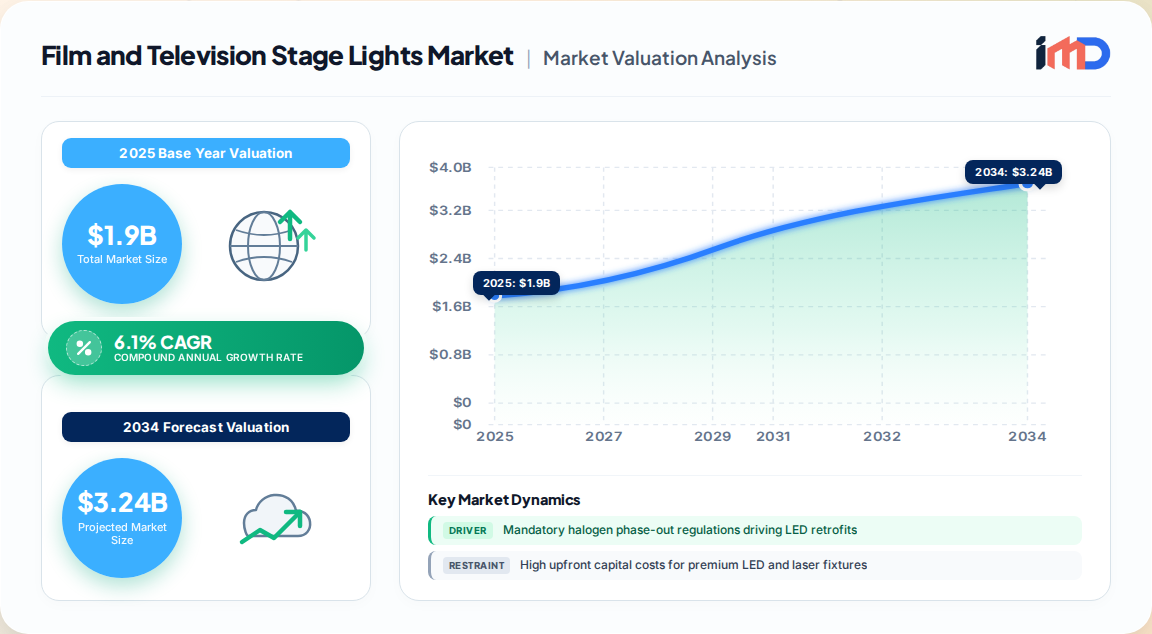
The global Film and Television Stage Lights Market represents a critical, high-value segment within the broader professional lighting industry, defined by fixtures engineered for the rigorous, color-critical, and high-output demands of broadcast studios, film sets, and virtual production stages. Our proprietary primary research estimates the market at USD 1.90 Billion in 2025, with a clear trajectory to reach USD 3.43 Billion by 2035, advancing at a CAGR of 6.1%. This growth is not merely a function of volume; it is driven by a fundamental technology migration from legacy halogen and discharge sources to tunable, networked, and software-defined LED and laser luminaires. The market's center of gravity is shifting from simple illumination toward data-driven, camera-ready light engines that integrate seamlessly with on-set ecosystems and virtual production volumes.
The market's expansion is anchored by two structural engines that are fundamentally reshaping procurement strategies for studios, rental houses, and broadcasters.
Despite the compelling growth narrative, the market faces tangible headwinds that moderate the pace of adoption.
The Film and Television Stage Lights Market is segmented by light source, product type, application, and distribution channel. Our analysis reveals distinct growth differentials within each category.
| Light Source | Market Share (2025) | CAGR (2026-2035) | Outlook |
|---|---|---|---|
| LED | 62.00% | 7.4% | Dominant and growing; tunable white and RGBL engines are the new standard for film/TV. |
| Laser | ~5.00% | 8.7% | Fastest-growing niche; used for long-throw follow spots and high-intensity beam effects. |
| Discharge | ~18.00% | 2.1% | Still used for high-output follow spots but declining as LED brightness improves. |
| Halogen | ~15.00% | -0.6% | Declining rapidly due to regulations; retaining residual demand in archival and legacy setups. |
Moving head lights are the largest product category, accounting for 34.00% of total market value in 2025. Their growth is driven by the versatility and programmability required for dynamic film sets and multi-camera television shows. Lighting consoles and controllers represent the second-largest segment by value and are growing at 6.4% CAGR, reflecting the increasing complexity of lighting programming and the need for integrated control over networked fixtures. Strip lights and PAR cans, while smaller in value, are essential for cyclorama washes and soft key lighting.
Television and Film Studios represent a distinct and high-value application, growing from USD 418.00 Million in 2025 to USD 764.76 Million by 2035. This growth is outpacing the broader market due to the massive investment in new soundstages and virtual production facilities. Unlike concerts and live events, which prioritize spectacle and beam effects, film and TV lighting prioritizes color accuracy, silent operation, and controllable softness—features that command a premium.
The market exhibits a distinct geographic hierarchy based on production infrastructure and investment cycles.
The competitive environment is shaped by a mix of established lighting manufacturers and specialized technology providers. ETC (Electronic Theatre Controls), Robe Lighting s.r.o., Ayrton Lighting, Elation Professional, and Chauvet & Sons are among the key players driving innovation. Recent developments illustrate the strategic direction of the market:
These developments underscore a competitive race toward higher output, greater precision, and tighter integration with digital production workflows. Suppliers that offer open protocols, robust service networks, and clear upgrade paths are best positioned to win long-term fleet contracts.
While the hardware market is competitive, significant white space exists in the software and services layer. Studios and rental houses are increasingly seeking:
These service-oriented offerings command higher margins and foster stickier customer relationships, representing a key strategic frontier for market participants.
The Film and Television Stage Lights Market is globally integrated, with manufacturing concentrated in Asia and demand centers in North America and Europe. According to official trade statistics, China is the largest exporter of stage lighting equipment, followed by Germany and the United States. The supply chain for critical components—LED engines, optics, and driver ICs—is heavily reliant on a small number of Asian foundries, creating a concentration risk that manufacturers are actively managing through dual-sourcing and strategic inventory buffers. The United States and European Union remain net importers of finished fixtures, while also exporting high-value, specialized luminaires and control systems. Tariffs and trade agreements are a key variable affecting procurement costs, particularly for large rental fleet orders.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.1% from 2020-2034 |
| Segmentation |
|
By Application
By Distribution Channel
| By Geography |
|
The market is estimated at USD 1.90 Billion in 2025, and it is projected to reach USD 3.43 Billion by 2035, growing at a CAGR of 6.1%.
LED is the dominant light source, accounting for 62.00% of the market value in 2025, driven by its energy efficiency, tunable color, and silent operation.
Asia-Pacific is the fastest-growing region, expanding at a CAGR of 7.4% from 2026 to 2035, driven by massive studio construction in countries like China, South Korea, and India.
Key drivers include the LED upgrade cycle, the rise of virtual production and XR stages, growth in streaming content production, and energy-efficiency regulations phasing out halogen fixtures.
Major companies include ETC (Electronic Theatre Controls), Robe Lighting s.r.o., Ayrton Lighting, Elation Professional, Chauvet & Sons, Martin Professional, and Claypaky, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Lighting Directors & Directors of Photography | 30% |
| Procurement & Purchasing Managers | 25% |
| Studio Operations Managers | 20% |
| Technical Directors & Gaffers | 15% |
| Product Managers & R&D Engineers | 10% |
| Company Type | Representation (%) |
|---|---|
| Lighting Fixture OEMs | 35% |
| Rental Houses & Production Resource Groups | 25% |
| Studio & Broadcast Facility Operators | 20% |
| Component & Control System Suppliers | 15% |
| Distributors & Dealers | 5% |