1What is the Fashion Blind Box Market size in 2024?
Our first-party research values the global fashion blind box segment at USD 2.14 Billion in 2024, embedded within the broader USD 13.53 Billion blind box economy.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Fashion Blind Box Market
 by Product Type (Wearable Accessories, Bags & Mini Bags, Plush & Textile Charms, Apparel & Streetwear Capsules, Footwear & Mini Collectibles), by Price Range (Budget Segment, Mid-Range Segment, Premium Segment, Luxury Segment), by Distribution Channel (Online Retail, Specialty Stores, Supermarkets and Hypermarkets, Vending Machines, Direct-to-Consumer), by End User (Children, Teenagers, Adult Collectors, Gift Buyers), by Material (Plastic and Vinyl, Plush and Textile, Resin, Metal, Sustainable Materials), by Licensing Type (Entertainment Franchises, Anime & Manga, Gaming, Luxury Brands, Independent Artists), by Asia Pacific (China, Japan, South Korea, Southeast Asia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by South America (Brazil, Argentina, Chile), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034

Research Analyst


 Related Reports

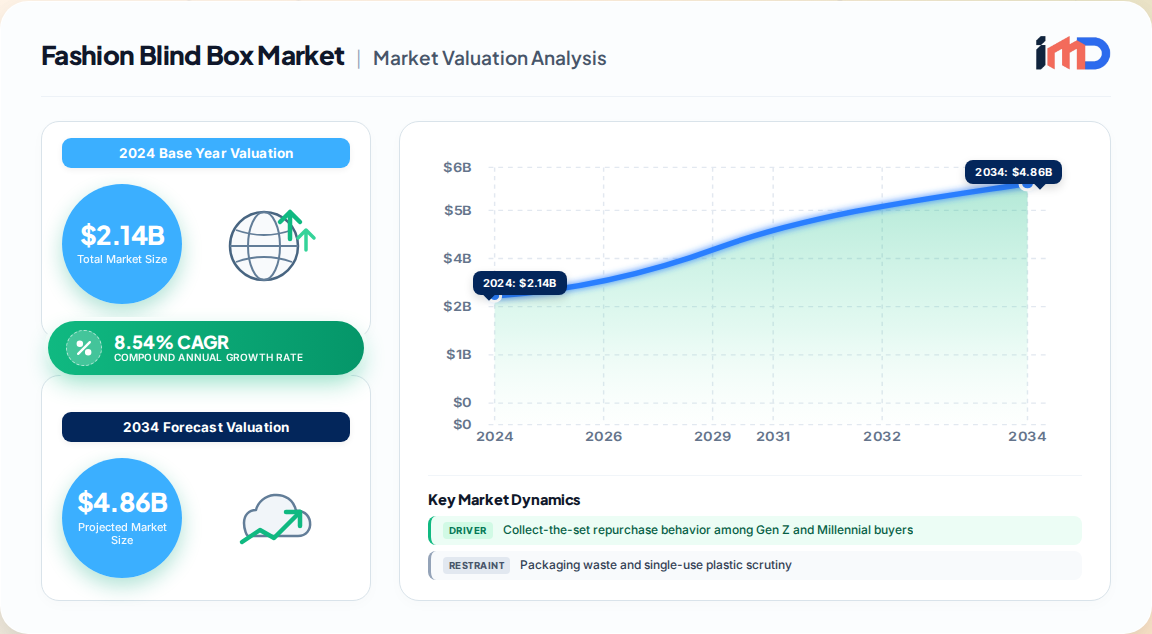
The Fashion Blind Box Market represents one of the most dynamic convergence zones in global consumer goods — the intersection of mystery-retail psychology, designer aesthetics, and accessible luxury. Our proprietary first-party research estimates the global fashion blind box segment at USD 2.14 Billion in 2024, embedded within a broader blind box economy valued at roughly USD 13.53 Billion. We project the fashion-specific segment to reach USD 4.86 Billion by 2034, expanding at a CAGR of 8.54% — materially outpacing the overall blind box category's 6.14% trajectory.
This premium growth differential is structural, not cyclical. Fashion blind boxes — sealed packages containing randomized apparel accessories, jewelry, bags, plush charms, wearable art pieces, and licensed designer collectibles — command higher average selling prices, attach to fast-moving style cycles, and benefit from repeat-purchase behavior driven by "complete-the-set" wardrobe logic.
Fashion blind boxes convert accessories into serialized collectibles. A single series may contain 8–12 designs plus a low-odds "secret" chase piece, compelling buyers to repurchase until the set is complete. Our primary interviews with specialty retailers indicate that over 60% of fashion blind box buyers make three or more purchases within a single series cycle.
TikTok, Instagram Reels, and livestream shopping have made the fashion reveal a shareable event. Influencer unboxing content acts as organic top-of-funnel marketing, and algorithm-driven discovery exposes new cohorts to accessory collectibles. Live-selling hosts opening fashion blind boxes generate real-time conversion at scale.
Licensing partnerships with anime franchises, gaming IPs, luxury houses, museums, and independent artists lend fashion blind boxes cultural legitimacy. Crossover drops — plush charms tied to entertainment releases, designer bag charms tied to runway seasons — create urgency and secondary-market pricing power.
The typical fashion blind box sits in the mid-range price band (USD 10–40), delivering designer-adjacent excitement at an accessible entry point. This positions the format favorably against rising prices in traditional accessible-luxury categories.
The fashion blind box value chain is IP-led at the top and logistics-intensive at the base.
| Stage | Key Activities | Value Capture |
|---|---|---|
| IP & Design | Character licensing, artist collaboration, trend forecasting | High (licensor royalties 8–15% of wholesale) |
| Manufacturing | Vinyl, plush, resin, textile accessory production | Moderate |
| Packaging & Randomization | Sealed packaging, rarity-assortment, authentication tagging | Moderate |
| Distribution | DTC e-commerce, specialty retail, vending, livestream | High (DTC margin advantage) |
| Secondary Market | Resale, trading, grading | Emerging, largely informal |
Key structural insight: brands that own both IP and DTC channels capture the largest share of margin, which explains the aggressive vertical integration among category leaders.
Fashion blind boxes are manufactured predominantly in East and Southeast Asia and shipped globally as finished consumer goods. Trade flow analysis anchored in UN Comtrade and national customs data reveals clear patterns:
| Segment | Positioning | Growth Outlook |
|---|---|---|
| Wearable Accessories (jewelry, hair, charms) | Core fashion expression | Fastest growth |
| Bags & Mini Bags | High AOV, strong gifting | Strong |
| Plush & Textile Charms | Licensed IP crossover | Strong |
| Apparel & Streetwear Capsules | Limited drops | Emerging |
| Footwear & Mini Collectibles | Niche collector appeal | Moderate |
The mid-range segment (USD 10–40) dominates volume, while the premium tier (USD 40–100+) is projected to capture sizeable incremental revenue as designer collaborations mature.
Teenagers and young adults (Gen Z and Millennials) form the demand core; adult collectors drive premium and chase-piece economics; gift buyers represent a seasonally significant pool.
| Region | Market Share | Growth Profile |
|---|---|---|
| Asia Pacific | 43% | Largest and fastest; deep collectible culture, dense retail, strong IP ecosystem |
| North America | 24% | Rapid retail expansion; strong social commerce adoption |
| Europe | 21% | Premium and designer-led; strict sustainability standards shaping packaging innovation |
| South America | 6% | Emerging high-growth; rising e-commerce and anime/gaming fandom |
| Middle East & Africa | 6% | Early-stage; mall retail and gifting demand |
Asia Pacific's leadership is anchored in mature collector communities and vertically integrated brands. North America's growth is being propelled by aggressive specialty retail rollouts and kiosk networks. Europe skews premium and regulation-conscious, favoring eco-certified packaging and limited-edition luxury formats. Latin America is the fastest-emerging frontier, supported by expanding middle-class consumption and localized franchise partnerships.
Our competitive benchmarking identifies a concentrated leadership tier alongside a fragmented long tail of licensed and independent labels. Strategic activity in 2026 has been intense:
Strategic imperatives for incumbents and entrants alike: secure durable IP pipelines, build DTC and livestream capability, invest in authentication, and design packaging for regulatory resilience.
Three under-served opportunity zones stand out from our demand modeling:
The fashion blind box market is a structurally advantaged sub-segment of the broader collectible economy. With a 8.54% CAGR through 2034, premiumization, IP depth, and social commerce will determine winners. Brands that pair design credibility with supply-chain agility and regulatory foresight are positioned to compound share in a market projected to approach USD 4.86 Billion by 2034.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.54% from 2020-2034 |
| Segmentation |
|
By Price Range
By Distribution Channel
By End User
By Material
By Licensing Type
| By Geography |
|
Our first-party research values the global fashion blind box segment at USD 2.14 Billion in 2024, embedded within the broader USD 13.53 Billion blind box economy.
The fashion blind box segment is projected to grow at a CAGR of 8.54% from 2025 to 2034, outpacing the overall blind box category's roughly 6.14% trajectory.
Asia Pacific leads with approximately 43% of global market share, driven by deep collectible culture and vertically integrated brands, followed by North America at about 24%.
Online retail leads overall, with livestream and social commerce as the fastest-growing sub-channel due to influencer-driven unboxing content and real-time conversion.
Teenagers and young adults aged 15–35 form the demand core, while adult collectors drive premium chase-piece economics and gift buyers create seasonal demand spikes.
Sustainability and packaging-waste scrutiny, regulatory review of randomized-selling mechanics, counterfeit exposure, and complex multi-SKU inventory management are the primary restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Merchandising Officer / Category Director | 30% |
| Product Development & Design Manager | 28% |
| Licensing and IP Portfolio Manager | 24% |
| Supply Chain & Procurement Lead | 18% |
| Company Type | Representation (%) |
|---|---|
| Designer toy and fashion accessory brands | 32% |
| Licensing and IP holders (entertainment, anime, gaming) | 22% |
| Specialty and omnichannel retailers | 20% |
| Manufacturers and packaging suppliers | 16% |
| Independent artists and boutique labels | 10% |