1What is the fan-out packaging market size in 2025?
Our proprietary research estimates the global fan-out packaging market at USD 2.98 billion in 2025, projected to reach USD 8.52 billion by 2035 at an 11.1% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Fan-out Packaging Technology Growth
 by Fan-out Type (Fine Pitch Fanout, Wide Fanout), by Substrate Material (Organic Resin, Polyimide, Silicon Interposer, Rigid Organic Laminate), by Packaging Type (Fan-Out Wafer Level Packages, Fan-Out Panel Level Packages, Fan-Out Chip-on-Wafer Packages, Fan-Out Chip-on-Substrate Packages), by Device Architecture (Stacked Die, 2.5D Chip Integration, 3D Chip Integration), by Density (Core Fan-Out, High-Density Fan-Out, Ultra High-Density Fan-Out), by Carrier Type (200mm, 300mm, Panel), by Business Model (OSAT, Foundry, IDM), by Application (High-Performance Computing, AI/ML, Networking and Telecom Infrastructure, Wireless Communication Devices, Consumer Electronics, Automotive, Industrial, Healthcare, Aerospace & Defense), by Asia-Pacific (Taiwan, South Korea, China, Japan), by North America (United States, Canada, Mexico), by Europe (Germany, France, United Kingdom, Netherlands), by South America (Brazil, Argentina), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034

Research Associate

 Related Reports

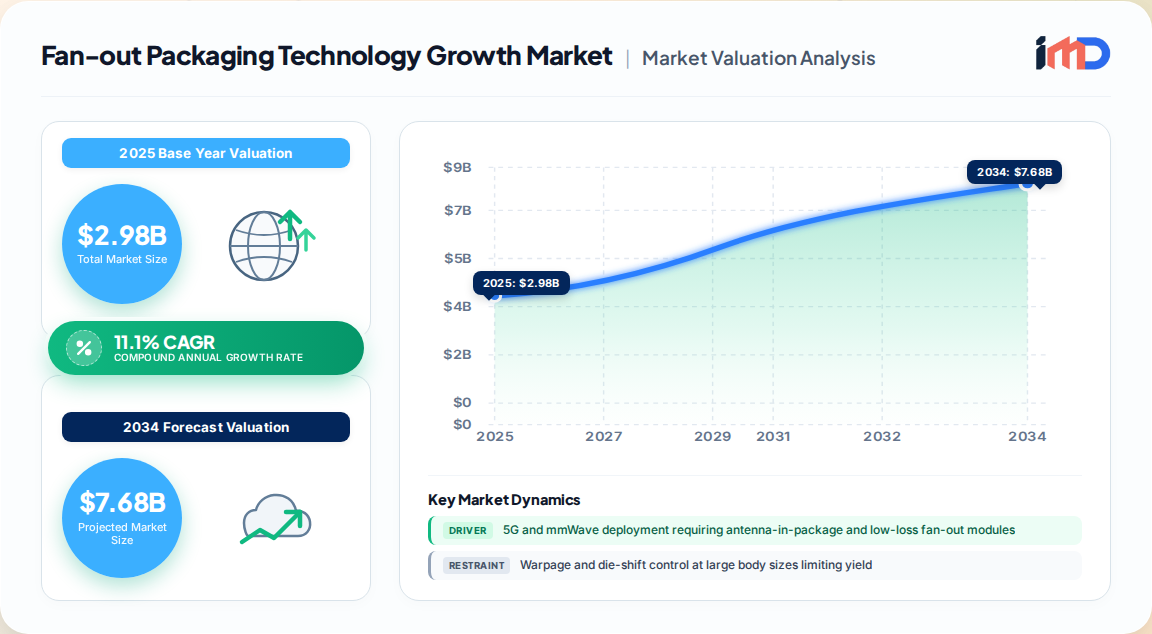
The global fan-out packaging technology market is undergoing a structural re-rating as semiconductor value migrates from front-end node scaling to advanced packaging. Our proprietary primary research and expert interviews place the market at USD 2.98 billion in 2025, expanding to USD 8.52 billion by 2035 at an 11.1% CAGR. This trajectory is underwritten by three converging forces: the slowing of Moore's Law economics, the explosion of AI/HPC workloads requiring high-bandwidth die-to-die interconnect, and the mainstreaming of chiplet architectures across mobile, networking, and automotive silicon.
Fan-out packaging has evolved from a niche wafer-level technique into the backbone of heterogeneous integration. Unlike traditional laminate or flip-chip packages, fan-out enables sub-10-micron redistribution layer (RDL) line/spacing, superior thermal resistance, and a smaller footprint — critical attributes as system-level performance becomes packaging-limited rather than transistor-limited. Our demand modeling indicates that fan-out packaging now represents approximately 15% of the advanced packaging market and 32% of the wafer-level packaging market, with its share rising as 2.5D and 3D integration displace conventional interposers.
The growth engine is multi-cyclical, not dependent on a single end-market.
Restraints remain non-trivial:
The market segments along three axes that determine both performance envelope and competitive dynamics.
| Segment Axis | Leading Segment (2025) | Fastest-Growing Segment | Share / Growth Signal |
|---|---|---|---|
| Fan-out Type (Density) | Fine Pitch / Standard-Density (~48%) | Ultra-High-Density (UHD FO) | UHD FO ~49% of revenue; ~22% CAGR |
| Carrier Type | 300mm Wafer | Panel-Level | Panel offers carrier utilization up to 95% |
| Business Model | OSAT (~41%) | Foundry | Foundry holds ~77% of total FO revenue via TSMC |
| Substrate Material | Organic Resin | Polyimide | Polyimide favored for fine-pitch RDL |
| Packaging Type | FO-WLP | FO-Chip-on-Substrate (FOCOS) | FOCOS enables larger body sizes |
| Device Architecture | Stacked Die | 3D Chip Integration | 3D integration driven by HPC/AI |
Ultra-high-density fan-out is the strategic prize. It is the only packaging class capable of replacing silicon interposers at competitive cost for chiplet-based AI accelerators. High-density fan-out remains the revenue workhorse, anchored in smartphone application processors and wearables, with expansion into AR/VR headsets and pluggable optical transceivers. Core fan-out holds roughly 15% of the market and serves cost-sensitive RF, power management, and automotive applications.
Panel-level packaging represents the most significant manufacturing inflection. The industry's first 600mm x 600mm panel-level fan-out demonstration in December 2021 validated the path to step-function cost reduction. Our supply-chain interviews indicate that panel-level capacity is being qualified for high-volume production, with the primary gating factors being warpage control and die-attach placement accuracy.
Asia-Pacific dominates both production and consumption, accounting for approximately 48% of global fan-out packaging revenue. Taiwan is the undisputed epicenter, hosting the largest fan-out foundry capacity and a dense ecosystem of OSATs, substrate suppliers, and equipment vendors. South Korea, China, and Japan contribute specialized capability in memory integration, OSAT capacity, and materials respectively.
North America holds 26% of the market, driven by fabless design houses, IDMs, and a policy-backed push to onshore advanced packaging capacity. Europe accounts for 16%, with strength in automotive and industrial semiconductor packaging and a growing focus on chiplet research consortia. South America and the Middle East & Africa each represent approximately 5%, primarily as import-dependent end-markets with limited domestic packaging capability.
Trade flows are heavily asymmetric. Fan-out packages and the wafers that feed them move predominantly from Taiwan, South Korea, and China into North America and Europe. The primary import/export dynamic is not in finished packages but in RDL-equipped wafers, mold compounds, and polyimide precursors. Supply-chain risk is concentrated at the Taiwan Strait and at a handful of RDL tooling suppliers.
Competition is bifurcated between foundries and OSATs.
Key recent developments include:
The fan-out packaging value chain is vertically deep and geographically concentrated.
Procurement strategy is shifting from lowest-cost-per-unit toward total cost per I/O, cycle time, and test coverage. Our interviews with packaging procurement directors indicate that suppliers with material depth, RDL design-rule maturity, and EDA co-design partnerships are capturing a disproportionate share of design wins.
The highest-value white-space opportunities in fan-out packaging include:
Investment risk is concentrated in capacity timing: panel-level lines require multi-hundred-million-dollar commitments ahead of demand visibility. Firms that secure anchor customers and co-development agreements will de-risk the transition. The market's 11.1% CAGR to 2035 is not a smooth line — it is back-loaded, with acceleration expected after 2027 as AI-driven UHD FO demand and panel-level cost curves intersect.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.1% from 2020-2034 |
| Segmentation |
|
By Packaging Type
By Device Architecture
By Density
By Carrier Type
By Business Model
By Application
| By Geography |
|
Our proprietary research estimates the global fan-out packaging market at USD 2.98 billion in 2025, projected to reach USD 8.52 billion by 2035 at an 11.1% CAGR.
Asia-Pacific accounts for approximately 48% of global fan-out packaging revenue, with Taiwan hosting the largest foundry and OSAT capacity, including TSMC which held about 77% of the fan-out market in 2023.
AI and HPC workloads require I/O densities above 18 per square millimeter, driving UHD FO growth at roughly 22% annually. UHD FO represented about 49% of fan-out revenue in 2024.
Key players include TSMC, ASE Technology Holding, Amkor Technology, JCET Group, Samsung Electro-Mechanics, Powertech Technology, and Siliconware Precision Industries, with TSMC holding roughly 77% market share in 2023.
Panel-level fan-out uses large panels (up to 600mm x 600mm) instead of wafers, enabling carrier utilization up to 95% and significant cost reductions. Nepes Laweh demonstrated the first 600mm panel-level fan-out in December 2021.
Key challenges include warpage and die-shift control at large body sizes, high capital intensity for RDL and panel tooling, supply concentration with one foundry holding 77% share, and known-good-die availability for multi-die packages.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Vice President of Advanced Packaging | 30% |
| Director of Packaging R&D | 25% |
| Procurement Director for Semiconductor Materials | 25% |
| Senior Process Integration Engineer | 20% |
| Company Type | Representation (%) |
|---|---|
| Fan-out Foundries and OSATs | 35% |
| Semiconductor IDMs and Fabless Design Houses | 25% |
| RDL and Dielectric Material Suppliers | 15% |
| Advanced Packaging Equipment Vendors | 15% |
| System OEMs (Mobile, HPC, Automotive) | 10% |